

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Automotive Air Intake Manifold Market: Decoding the 5.2% CAGR and $318M Trajectory to 2032

The Automotive Air Intake Manifold Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The global automotive air intake manifold market has demonstrated steady expansion, moving from approximately 175.5 million USD in 2020 to an estimated 223.0 million USD in 2025. The trajectory points toward continued growth through the end of the decade, with the market projected to reach roughly 318.4 million USD by 2032, supported by a compound annual growth rate of 5.2 percent. This expansion reflects a mature but resilient component segment that sits at the intersection of engine performance, emissions compliance, and vehicle lightweighting. While the absolute revenue figures may appear modest compared to powertrain or battery markets, the intake manifold plays a disproportionately important role in determining airflow efficiency, thermal management, and acoustic behavior across both passenger and commercial vehicle platforms.
The market structure remains moderately fragmented. The top three participants account for roughly a quarter of total revenue, while the top five collectively capture about 35 percent. This concentration level suggests that no single supplier dominates the value chain, leaving room for differentiated positioning based on material expertise, integration capability, and regional manufacturing footprints. At the same time, the moderate consolidation level indicates that scale advantages are still being built, particularly in regions where OEM sourcing strategies favor multi-sourcing and localized supply.
Several structural challenges are reshaping how suppliers and buyers approach this market. First, the transition toward higher-efficiency internal combustion engines, hybridization, and alternative fuels is changing manifold design requirements. Higher thermal loads, tighter packaging constraints, and the need to manage complex airflow paths for turbocharged, direct-injection, and multifuel engines place greater demands on material durability and geometric precision. Second, raw material volatility and sustainability expectations are pressuring both cost structures and product specifications. Aluminum, engineering plastics, and composite formulations each carry distinct cost, weight, and recycling trade-offs, and buyers increasingly expect suppliers to demonstrate credible pathways toward lower-carbon and recycled content without compromising performance. Third, platform consolidation and longer development cycles in the passenger car segment are tightening justification thresholds for specialized component variants. Suppliers must balance the need for standardized architectures with the requirement to support engine-specific tuning, which compresses margins on highly customized builds.
These challenges are not merely operational headaches. They represent strategic inflection points that separate suppliers who can integrate material science, validation rigor, and flexible manufacturing from those who remain locked into legacy designs. The question for decision-makers is whether to treat the intake manifold as a commoditized engine component or as a value-adding subsystem that can contribute to fuel efficiency, emissions performance, and vehicle refinement.
Key Drivers Reshaping the Market
Technological Innovation and Material Breakthroughs
Material innovation is one of the most visible forces driving change in this segment. The shift from traditional aluminum to advanced polymers and composite materials is accelerating where weight reduction and integration benefits justify the transition. Plastic intake manifolds can offer substantial weight savings compared with aluminum equivalents, which matters increasingly for overall vehicle mass targets and downstream fuel or energy consumption. Beyond simple substitution, the real value lies in multi-material design strategies that match material properties to functional zones, such as high-temperature regions near the turbocharger or exhaust-adjacent passages versus lower-stress inlet sections.
A notable example of this trajectory is the development of a fully recycled nylon intake manifold molded from RadiciGroup Renycle and recognized with an Automotive Innovation Award in the Power Train Category from the Society of Plastics Engineers. The design and manufacturing work, associated with Marelli, demonstrates that recycled polyamide can move from concept to validated automotive application. The component was validated through burst pressure, thermal cycling, vibration, and NVH tests, signaling that sustainability-driven material choices are no longer limited to secondary or non-critical parts. In parallel, industry data indicates that recycled polyamide manifolds have been adopted in automotive applications, including by Volkswagen, while glass fiber reinforced polypropylene is also in use for intake manifolds in certain applications. These developments point to a broader normalization of recycled and reinforced polymers within the component mix.
Policy and Regulatory Environment
Regulatory pressure continues to shape engine calibration requirements and component design priorities. Emissions limits, fuel economy standards, and Real-Driving Emissions frameworks push manufacturers toward more precise air management, faster response, and improved thermal stability. In this context, the intake manifold is not simply a duct; it is part of the air path strategy that supports combustion efficiency, torque delivery, and emissions compliance.
Validation and durability requirements are becoming more stringent, particularly for new materials and integrated designs. The broader trend is toward earlier and more comprehensive testing of airflow behavior, pressure integrity, vibration resistance, and NVH performance. Suppliers that can document robust validation results for recycled or composite-based manifolds gain a meaningful advantage in qualification cycles, especially with OEMs that are cautious about introducing material changes into high-temperature or high-cycle engine environments.
Demand-Side Shifts in Vehicle Platforms
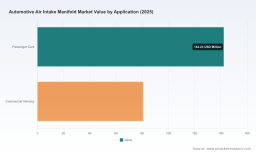
Demand patterns are evolving as OEMs adjust their powertrain roadmaps. Passenger cars remain the dominant application arena, but the composition of that demand is changing as turbocharged downsized engines, hybrid-electric assist systems, and multifuel variants become more common. In commercial vehicles, the requirement for durable, high-volume air management solutions continues to support steady demand for both aluminum and engineered plastic solutions, particularly where service life, thermal resistance, and cost predictability are priorities.
Another demand-side signal is the increasing expectation that intake manifolds contribute to packaging efficiency and system integration. Modern engine bays are tightly packed, and the manifold is often expected to accommodate integrated sensors, throttle bodies, and in some cases intercooling functions. This integration reduces part count and assembly complexity, but it also raises the bar for design coordination across airflow, thermal, and acoustic requirements.
Competitive Landscape and Leading Strategies
The supplier base reflects a mix of global Tier-1 integrators and specialized material-focused manufacturers. Several companies illustrate distinct strategic approaches.
Marelli positions itself around complete air intake manifold modules, integrating throttle bodies, valves, EGR, intercoolers, and injection system elements for natural aspirated and turbo gasoline, diesel, LPG, CNG, and multifuel engines. This integration-heavy approach is well aligned with OEM preferences for fewer interfaces and coordinated performance tuning across the air and fuel management chain. The company's recognition for a 100 percent recycled nylon manifold also signals an explicit link between sustainability and performance credibility.
Röchling Group focuses on lightweight suction manifold systems in PA66, PP, and PA6 materials, with integrated sensors, throttle bodies, seals, optional intercoolers, and variable intake length or flap systems. The emphasis on material variety and dynamic airflow features suggests a strategy built around design flexibility and application-specific tuning rather than a single standardized offering.
MAHLE GmbH manufactures both plastic and aluminum manifolds for passenger cars, commercial vehicles, and performance applications. A dual-material portfolio allows the company to match material choice to engine architecture and thermal conditions, which can be especially valuable as platforms span multiple powertrain configurations.
Aisin Seiki produces resin and aluminum-type manifolds for global OEM vehicles, indicating a scale-oriented approach that supports broad model coverage and cross-region supply. Toyota Boshoku provides intake manifold systems for Toyota and other OEM vehicles across resin and aluminum variants, reflecting strong alignment with integrated OEM ecosystems and model-specific engineering relationships. MANN+HUMMEL supplies plastic manifolds with modular design and acoustic optimization for passenger cars and light commercial vehicles, highlighting noise, vibration, and harshness refinement as a differentiator rather than just structural function.
Medical Manifolds Market
These profiles reveal a market where differentiation is increasingly tied to integration, material credibility, and system-level value rather than simple part fabrication. The strategic positioning that stands out is the move toward modules that reduce assembly complexity, support multifuel or hybrid-related calibration needs, and demonstrate validated performance for advanced materials.
Market evolution is likely to continue along two parallel paths. In one direction, integration will deepen as suppliers compete on module completeness, validation reliability, and material sustainability credentials. In the other, specialization will persist where regional OEM sourcing, commercial vehicle durability requirements, or performance applications reward focused material or acoustic expertise. New entry remains difficult because qualification cycles, validation evidence, and OEM relationship depth create meaningful barriers, but selective entry can still occur where a supplier brings a clearly differentiated material solution or an attractive cost-and-integration proposition.
Future Trends and Commercial Opportunities
Material normalization and circular content adoption
The most probable near-term trend is broader acceptance of recycled and reinforced polymers in intake manifold applications, especially where validation evidence has already been demonstrated and cost or weight targets justify the shift. As more OEMs gain confidence in recycled polyamide and glass fiber reinforced polypropylene, the conversation will move from pilot adoption to mainstream specification in appropriate engine environments. For suppliers, this creates an opportunity to build material qualification portfolios that can be reused across multiple programs, reducing the incremental cost of introducing sustainable content. For buyers, the opportunity lies in securing supply commitments that balance sustainability goals with durability, thermal performance, and price stability.
Integration as a value multiplier
A second trend is the continued push toward integrated manifold modules that incorporate throttle control, sensing, valve functions, and in some cases intercooling or variable intake features. The commercial logic is straightforward: integration can reduce assembly steps, lower interface variability, and simplify calibration coordination. From a commercial standpoint, this favors suppliers that can manage multi-component design and validation holistically rather than those offering only the molded duct. The opportunity is strongest where platform strategies require quick adaptation across engine variants or where packaging constraints reward compact, multifunctional assemblies.
Air Intake Resonator Market
Regional and application divergence
A third trend is the growing divergence between regions and vehicle segments in material and design preferences. In some areas, aluminum may remain preferred for specific high-temperature or high-duty applications, while in others, engineered plastics and composites will capture more share where weight and integration advantages are prioritized. Passenger cars and commercial vehicles will continue to impose different demands on durability, cost, and acoustic behavior, meaning that a single product strategy is unlikely to fit all contexts. The opportunity here is for suppliers and buyers alike to segment their portfolios more deliberately, rather than treating the manifold market as uniform.
PW Consulting
These trends carry uncertainty. Materials may face cost or supply constraints if recycled feedstock availability or reinforcement supply becomes tight. Validation requirements may slow adoption if OEMs demand additional testing for new material combinations, especially in high-stress engine locations. Platform volatility, particularly around electrification timing and multifuel strategy, can also change demand patterns faster than supply chains can adapt. Decision-makers should plan for a market where the winning position is not just low cost, but verifiable performance, flexible material choices, and credible integration capability.
Strategic Actions for Decision-Makers
For manufacturers and component suppliers
Invest in material validation as a strategic asset, not a compliance exercise. Evidence from burst pressure, thermal cycling, vibration, and NVH testing is increasingly central to qualification, especially for recycled or composite-based solutions. Build modular design capabilities that allow rapid adaptation across engine variants without sacrificing performance or increasing assembly complexity. Where possible, develop dual-material strategies that preserve aluminum options for demanding applications while capturing polymer and composite share where weight and integration benefits are strongest. Align product roadmaps with OEM sustainability expectations, but ground those roadmaps in validated durability rather than marketing claims.
For investors evaluating exposure in this space
Assess suppliers on material credibility, integration depth, and regional supply resilience rather than on revenue scale alone. The market's moderate concentration means that leadership is often earned through differentiated engineering and validation performance, not purely through volume. Look closely at whether a company can translate recycled or advanced material adoption into repeatable program wins, and whether its portfolio is positioned for multifuel, turbocharged, or hybrid-related air management needs. Be mindful of raw material volatility and the risk that sustainability-driven specifications could compress margins if cost structures are not managed actively.
For procurement and sourcing leaders
Use qualification criteria that reward both performance and material strategy. Where weight, packaging, and acoustic performance matter, give explicit weight to modular integration and validated NVH outcomes. Where sustainability commitments are part of the broader program, request documented test evidence for recycled or reinforced content and confirm that the chosen material path has been qualified for the expected thermal and pressure environment. Maintain a balanced sourcing approach that preserves aluminum options for higher-stress applications while opening the door to engineered polymer solutions where the application profile supports them.
The automotive air intake manifold market is entering a phase where material innovation, integration, and validation discipline will separate long-term winners from passive participants. Suppliers and buyers who treat the component as part of a broader air management and sustainability strategy are better positioned to capture value as the market moves toward greater complexity and higher expectations. For readers seeking more detailed segmentation breakdowns, regional nuance, application-level dynamics, and tailored procurement or investment scenarios, the full market research report provides a deeper dataset and structured decision support beyond the strategic overview presented here.
For detailed analysis of this topic, please visit the official page: Automotive Air Intake Manifold Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com