

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Cone Crushers Market: How Standard Hydraulics and Mining Demand Shape the 4.44% CAGR to 2032

The Cone Crushers Market: Strategic Shifts and Commercial Opportunities in a Data-Driven Landscape
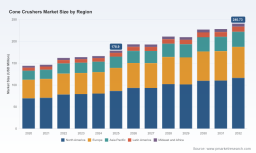
The global cone crushers market has moved through a decisive phase of structural transformation over the past five years. From a baseline of roughly 144.0 million USD in 2020, total market size expanded to 178.9 million USD by 2025, reflecting a compound annual growth rate of 4.44%. Looking ahead, the trajectory points to 240.73 million USD by 2032, with sustained mid-single-digit expansion. On the surface, this represents steady, predictable growth. Beneath it, however, the industry is navigating a set of interlocking pressures: tightening energy and emissions mandates, fragmented geographic demand patterns, and a competitive landscape where scale alone no longer guarantees advantage. For operators, manufacturers, and capital allocators, the question is no longer whether the market will grow, but how the winners will capture value as the rules of competition shift.
PW Consulting Automotive & Machinery Research Center
The base year 2025 figure of 178.9 million USD sits at a critical inflection point. Historical progression from 2020 to 2024 shows a market that weathered commodity cycle volatility, pandemic-era supply disruptions, and regional demand swings without losing long-term momentum. The forecast horizon from 2026 through 2032, extending to 240.73 million USD, implies continued expansion, though the path will not be linear. Short-term fluctuations in capital expenditure cycles, currency exposure, and regulatory adjustments will create pockets of volatility even as the underlying demand foundation holds. Revenue throughout this period is tracked in USD millions, a convention that aligns with cross-border procurement and financing practices, but it also underscores the importance of managing cost structures and export controls with precision.
Three core challenges define the current market moment. First, the industry is balancing throughput expectations with increasingly stringent energy efficiency and emissions standards. Cone crushers are no longer evaluated purely on break-even tonnage or wear part life; buyers expect measurable reductions in specific energy consumption and downtime. Second, regional demand is diverging rather than converging. Aging quarry fleets in developed markets create replacement-driven demand, while emerging construction and mining corridors generate new unit sales, but the product specifications, service expectations, and procurement cycles differ materially across geographies. Third, regulatory and trade complexity is reshaping how equipment moves across borders. Export controls, sanctions-related compliance, and tariff uncertainty on key producing regions have moved from back-office concerns to strategic planning inputs. These forces are not insurmountable, but they raise the bar for manufacturers and buyers who must coordinate technology roadmaps, supply continuity, and compliance posturing simultaneously.
Key Drivers Shaping Market Trajectory
Technology Innovation and the Push Toward Automation and Efficiency
The pace of product development in recent years signals that technology differentiation has become a primary battleground. In March 2025, Metso Corporation launched three next-generation Nordberg HPe series cone crushers featuring a head anti-spin brake, designed for mining and aggregates applications with a clear emphasis on advanced automation and energy efficiency. That launch followed Sandvik's April 2025 introduction of the QH443E electric tracked cone crusher for heavy-duty mining and quarry applications, extending the availability of electrified options into mobile and semi-mobile configurations. By March 2026, Sandvik had further advanced the CH400 and CH600 lineage with new CH442 and CH662 models unveiled at ConExpo, positioning them as the next evolution in secondary and tertiary crushing performance.
The common thread across these releases is not merely incremental improvement, but a deliberate narrowing of design priorities around control, energy draw, and serviceability. Automation assists are increasingly integrated to reduce operator variability, while electric and hybrid platform options expand the toolkit for operators seeking to lower operating costs and align with decarbonization targets. For the broader market, this matters because it shifts procurement decisions from a narrow comparison of upfront price and rated capacity toward total cost of ownership across a multi-year horizon. Manufacturers that can demonstrate repeatable gains in uptime, wear management, and power efficiency are gaining leverage in competitive tenders, particularly in mining and aggregate production where margin pressure is most acute.
Policy, Regulatory Environment, and Export Compliance as Strategic Variables
Regulatory dynamics have become a substantive driver of market behavior, influencing everything from product roadmap timing to channel strategy. In September 2025, the BIS expanded its Entity List and Military End-User List restrictions to cover affiliates with 50% or greater ownership, altering international export controls and supply chains for mining equipment. This change reverberates through the cone crushers market because global manufacturers and their distribution networks must now map ownership structures, end-use declarations, and destination risk with greater rigor. In January 2026, Cleary TradeWatch noted that U.S. reciprocal tariffs and potential Supreme Court challenges to 2026 trade measures affect equipment imports from major producing regions, adding cost and timing uncertainty to cross-border sourcing. At the same time, the EU updated compliance expectations tied to Council Regulation No 833/2014 and Russia-related implementation FAQs as of January 2026, requiring mining sector suppliers to refresh their compliance posture. The BIS also revised its license review policy for advanced computing commodities to China effective January 2026, a shift that may indirectly influence digital mining and automation technologies embedded in modern crusher systems.
For operators and suppliers, the implication is that regulatory fluency is now a competitive asset. Companies that have institutionalized export classification, end-user due diligence, and scenario planning around tariff or sanctions changes are better positioned to protect margins and avoid shipment disruptions. For buyers, especially those procuring from multinational manufacturers, understanding how trade policy affects lead times and configuration availability is increasingly essential. This environment does not halt demand, but it redistributes advantage toward organizations that can navigate complexity without sacrificing operational continuity.
Demand-Side Behavior and Structural Application Trends
Demand patterns across core applications reveal a market with distinct end-use profiles and different purchasing behaviors. Mining applications account for the largest share of demand at 91.2 in the segmentation split, followed by construction at 54.11, aggregate production at 26.74, and the chemical industry at 6.85. This distribution underscores that cone crushers are anchored in high-volume mineral processing and aggregate supply chains, where throughput, liner life, and configuration flexibility carry outsized weight. In mining, the emphasis is on reliable secondary and tertiary reduction under variable feed conditions and stringent reliability requirements. In construction and aggregate production, buyers prioritize throughput consistency, mobility options, and rapid changeover to match production schedules.
What is changing on the demand side is not the ranking of applications, but the nature of the purchasing decision. Operators are increasingly treating equipment selection as a multi-year asset management choice rather than a transactional purchase. The rise of mobile and semi-mobile crushing solutions, service contract expectations, and digital monitoring interfaces reflects a broader shift toward minimizing unplanned downtime and aligning capacity planning with project-based demand. In aggregate and recycling-oriented operations, shorter campaign cycles and tighter space constraints favor compact, reconfigurable configurations. In mining, more rigorous site conditions and higher utilization targets push buyers toward platforms that can integrate with broader site automation and condition-monitoring ecosystems. This behavioral shift rewards suppliers who can deliver not just hardware, but integrated support, remote diagnostics, and predictable consumables economics.
Supply Chain and Cost Structure Evolution
The supply chain backdrop shapes both product design and market access. Recent trade measures, licensing reviews, and ownership-based export restrictions have prompted manufacturers to reassess sourcing, assembly, and distribution footprints. For operators that depend on imported components or complete units from major producing regions, tariff exposure and compliance checks affect landed cost and delivery certainty. Simultaneously, the push for electrification and advanced control systems introduces new dependencies on power electronics, sensors, and software integration, which in turn require supplier qualification and quality assurance discipline.
This environment favors manufacturers that have diversified critical sourcing, standardized modular components, and built regional service capability. It also rewards buyers who structure procurement with enough lead time to accommodate customs and compliance steps, and who evaluate total cost rather than unit price in isolation. The supply chain is not merely a logistics function; it is now a determinant of competitive responsiveness and margin protection. Companies that treat supply chain strategy as part of product strategy are better equipped to sustain performance as policy and input cost conditions shift.
Competitive Landscape and Leading Strategies
The market exhibits meaningful concentration, with the top three firms holding approximately 55% of share and the top five reaching roughly 70%. This concentration points to the strategic importance of scale, brand recognition, technology portfolios, and global service reach. Yet concentration does not equate to uniformity. Leading firms are distinguishing themselves through targeted product families, electrification and automation roadmaps, mobile capabilities, and wear-part ecosystems that extend value beyond the initial sale.
Metso Corporation, headquartered in Finland, anchors its offering in the Nordberg HP, GP, and HPe series for mining and aggregates, with a profile that emphasizes advanced automation and energy efficiency. Its March 2025 launch of three next-generation HPe series crushers with head anti-spin brake illustrates a strategy of incremental performance gains that translate into operational reliability and lower energy intensity. Sandvik AB, based in Sweden, builds on the CH400, CH600, and CH600e series for secondary and tertiary crushing, while expanding into electrified mobile configurations such as the QH443E launched in April 2025 and the CH442 and CH662 introduced in March 2026. The trajectory suggests a dual focus: high-performance stationary and semi-stationary platforms plus electrified, track-mounted options for flexible site deployment.
Impact Crusher Market
Terex Corporation, headquartered in the United States, contributes through the Cedarapids TC1300X, TG120, and Finlay mobile cone crushers targeting quarry, recycling, and construction aggregates. Its May 2026 exhibition of the TG120 at ICE Expo with dealer Quarry and Recycling Solutions reflects a channel-oriented go-to-market approach that leverages dealer networks for regional reach. Astec Industries Inc., also U.S.-based, offers the Kodiak and Titan cone crushers for coarse and fine crushing applications with on-the-fly adjustability, a capability that appeals to operations requiring frequent product-size changes and operational flexibility. Keestrack NV from Belgium focuses on mobile cone crushers for high-capacity aggregate production in quarry and recycling operations, aligning with the broader market move toward mobility and rapid deployment.
In Europe, Thyssenkrupp AG and The Weir Group Plc maintain strong positions through industrial-grade solutions. The Weir Group's ENDURON EP and EC series support secondary, tertiary, and pebble crushing, while Thyssenkrupp provides cone crushers for mining and aggregates industrial applications. FLSmidth & Co. A/S from Denmark adds the Raptor XL series alongside cone crushers for mining and aggregates processing, reinforcing its presence in mineral processing ecosystems. In the compact and mobile segment, McCloskey International from the United Kingdom offers the C2C Compact Cone Crusher and mobile cone crushers for recycling and aggregates, while Quarry Manufacturing & Supplies (QMS), also U.K.-based, supplies B3 and B-Series cone crushers to mining and quarry operations. In China, Shanghai Shibang Machinery Co., Ltd. offers hydraulic cone crushers for construction, mining, and aggregate applications, and Jiangxi Duma Machinery Manufacturing Co., Ltd. provides wear parts including mantles, bowl liners, and concaves compatible with cone crushers, contributing to the aftermarket and component ecosystem.
The strategic differentiation among these firms is not about a single capability, but about the alignment of product families with customer operations. Some emphasize stationary performance and automation for mining; others prioritize electrification and mobility for quarry and recycling; others compete on adjustability, wear-part compatibility, or dealer-led deployment. The market is evolving along two complementary axes: consolidation among scale players who can amortize technology investment and global service networks, and continued presence of focused players who compete on niche operational fit, mobile configurations, or regional support. New entrants face meaningful barriers in brand trust, application specificity, and service coverage, but opportunities remain for firms that address underserved mobility needs, compact configurations, or aftermarket component availability with clear performance differentiation.
Forward-Looking Trends for the Next 3–5 Years
Accelerated Electrification and Automation Integration
The sequence of product launches and the emphasis on energy efficiency point to a multi-year trend toward electrified and increasingly automated platforms. Electric tracked and hybrid configurations are expanding beyond niche applications into heavy-duty mining and quarry settings, while automation aids are moving from premium options to expected features in competitive tenders. This trend creates commercial opportunities for manufacturers that can offer integrated power, control, and condition-monitoring architectures, as well as for buyers who can reduce operating costs and align with site-level decarbonization goals. The risk lies in execution: electrification must be paired with robust service networks, spare part availability, and grid or generator compatibility planning to avoid gaps between specification and field performance.
Heightened Trade and Compliance Complexity as a Persistent Factor
Export controls tied to entity and military end-user restrictions, reciprocal tariff measures, and sanctions-related compliance expectations are likely to remain active variables through the forecast horizon. For global manufacturers and cross-border buyers, this means that trade compliance will increasingly influence product configuration choices, sourcing decisions, and channel design. Companies that embed compliance into procurement planning and supply chain mapping can reduce disruption risk, while those that treat it as an afterthought may face cost overruns and delivery delays. The opportunity for disciplined operators is to secure supply with longer lead times, diversified sourcing, and documented end-use diligence, thereby insulating projects from policy shocks.
Service and Wear-Part Economics as a Value Driver
As throughput expectations rise and energy costs remain a focal concern, the economics of consumables and service will weigh more heavily in total cost of ownership calculations. Wear parts, liner life, on-the-fly adjustability, and remote diagnostics are becoming differentiators because they directly affect uptime and operating cost. Manufacturers with strong aftermarket ecosystems, clear consumables roadmaps, and service integration are likely to capture more of the lifecycle value, while buyers that evaluate proposals through a lifecycle lens can negotiate better outcomes and reduce volatility. The uncertainty here is that rapid product iteration can outpace aftermarket standardization if not managed carefully, potentially complicating parts compatibility and service planning.
Mobile Crushers and Screeners Market
Actionable Implications for Decision Makers
For Manufacturers
- Align product roadmaps with electrification, automation, and serviceability rather than throughput alone, because buyers are increasingly scoring proposals on total cost of ownership and operational continuity.
- Invest in regional service capacity and parts availability to convert technology advantages into field reliability, especially as mobile and electrified configurations expand across quarry and recycling sites.
- Strengthen export classification, end-user due diligence, and scenario planning around tariffs and sanctions so that supply chain decisions support, rather than constrain, market reach.
For Investors
- Assess exposure to automation, electrification, and aftermarket ecosystems as indicators of resilience, since these areas are shaping procurement behavior across mining, construction, and aggregate production.
- Monitor trade and compliance developments as valuation-sensitive variables, because tariff changes, export control expansions, and licensing reviews can affect margins, lead times, and geographic mix.
- Look for firms that combine scale with focused application fit and service depth, because concentration alone does not guarantee competitive advantage without the operational capabilities to sustain it.
For Procurement and Operations Leaders
- Structure equipment evaluations around lifecycle economics, including wear-part life, energy draw, downtime risk, and service coverage, rather than headline capacity and initial price.
- Build procurement lead times that accommodate compliance checks, customs steps, and configuration verification, especially when sourcing from multinational manufacturers or cross-border channels.
- Require clear documentation on automation features, electrification compatibility, and consumables roadmaps to ensure that field operations can realize the promised performance improvements.
The cone crushers market is growing with a clear compound annual rate and a forecast trajectory that extends through the early 2030s, but the strategic contest is being decided on the details: how efficiently equipment converts power into throughput, how reliably manufacturers support mobile and stationary configurations, and how well organizations navigate an increasingly complex trade and compliance environment. For leaders seeking detailed segmentation data, regional revenue breakdowns, type-level dynamics, application-specific demand patterns, and tailored scenario planning, the full analytical dataset is available through PW Consulting's comprehensive market report. That resource provides the deeper quantitative structure and customized recommendations needed to translate these strategic trends into concrete procurement, investment, and product decisions.
For detailed analysis of this topic, please visit the official page: Cone Crushers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com