

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Coverslipper Market 2026: Beyond the 5.2% CAGR Story to 344.8M

Coverslipper Market: Strategic Trends and Commercial Opportunities Through 2032
The coverslipper market has moved from a largely commoditized equipment segment into a strategically consequential space driven by laboratory automation, regulatory scrutiny, and shifting materials preferences. With total market revenue projected to expand from approximately $215 million in 2025 to roughly $345 million by 2032, the sector is positioned for moderate but durable growth. The implied compound annual growth rate of 5.2 percent across the 2026–2032 forecast period reflects a market that is not experiencing explosive demand expansion, but rather steady modernization efforts within histology, cytology, and anatomic pathology workflows. This trajectory matters because it signals where value is being created: not simply in selling more units, but in enabling throughput gains, reducing consumable complexity, and aligning equipment with evolving compliance and operational expectations.
The historical record from 2020 to 2025 shows a market that recovered from a flat 2022 and then accelerated through 2023 and 2024 before reaching its current base year. That pattern indicates a demand environment that is increasingly tied to capital equipment cycles in diagnostic laboratories and manufacturing modernization programs, rather than to cyclical or discretionary spending alone. At the same time, the market structure remains relatively fragmented at the top tier, with the three largest participants holding a combined share near 24.6 percent and the top five firms accounting for about 26.2 percent. Such concentration levels are low enough to permit regional specialization and product differentiation, yet high enough to suggest that leading vendors have begun consolidating workflow advantages rather than competing purely on price.
Core Challenges and Inflection Points
Despite the steady outlook, the coverslipper market faces a set of structural challenges that are reshaping competitive priorities. The first challenge is the tension between throughput efficiency and operational cost management. Laboratories under pressure to reduce turnaround times are seeking automation that integrates coverslipping with upstream staining, handling, and quality control steps. Yet automation investments are evaluated against total cost of ownership, including consumables, workflow disruption during implementation, and the need for staff retraining. As a result, buyers are no longer treating coverslippers as standalone instruments; they are evaluating them as components of broader slide preparation ecosystems. This changes the basis of competition from instrument features alone to integrated operational outcomes.
The second challenge is regulatory and materials sensitivity. Coverslipping workflows in human and animal tissue diagnostics must align with device classification, mounting medium chemistry, and adhesive performance requirements. Particular attention is being paid to xylene exposure management, adhesive compatibility, and the consistency of film or glass placement on standard microscope slide formats. Equipment that can offer customizable programs, reduced solvent exposure, or adhesive-backed film solutions without sacrificing slide quality is gaining strategic relevance because it addresses both compliance comfort and workflow reliability. This is not a marginal concern; it shapes purchasing decisions in regulated environments where reproducibility and safety take precedence over incremental speed improvements.
A third inflection point is the growing relevance of material choices between polyolefin film, polyester film, and other types. The market’s current material split shows that polyolefin film remains dominant, while polyester and other materials serve more specialized needs. This distribution matters strategically because material selection influences adhesive behavior, mounting consistency, thermal tolerance, and downstream compatibility with microscopy and archival storage. Equipment and consumable strategies that are locked into a single material class can limit flexibility, whereas platforms designed to accommodate multiple film types or glass workflows can better serve labs with mixed specimen pipelines. The implication is that product architecture, not just instrument speed, is becoming a competitive differentiator.
Key Drivers of Market Change
Automation and Workflow Integration
The most prominent driver is the push toward integrated histology and cytology workflows. Rather than adding a coverslipper at the end of a linear process, laboratories are increasingly seeking systems that coordinate staining, rinsing, handling, and coverslipping in a combined station or synchronized line. This driver is visible in recent product introductions that pair robotic coverslipping with automated staining functions, allowing laboratories to reduce manual handling and standardize slide preparation steps. The commercial value of this trend lies in repeatability: integrated systems can reduce variability across batches, support higher sample volumes, and simplify operator oversight. More importantly, they align with the broader shift in diagnostic laboratories toward platform-based purchasing, where equipment is evaluated by its contribution to an end-to-end workflow rather than by isolated performance metrics.
Regulatory Alignment and Safety-Conscious Mounting Practices
Regulatory expectations and safety-conscious laboratory practices are another decisive factor shaping demand. Devices and consumables used in coverslipping for human and animal tissue specimens are increasingly scrutinized for device classification, reagent exposure, and procedural consistency. Equipment designed with adjustable programs, reduced solvent usage, or alternatives to traditional mounting approaches can offer a meaningful advantage in settings where occupational exposure, environmental handling, and procedural documentation matter. At the same time, the growing relevance of adhesive-backed film solutions compatible with standard microscope slide dimensions illustrates how consumable design and equipment design are becoming interdependent. The practical effect is that vendors able to demonstrate both regulatory alignment and practical usability are better positioned to gain trust in regulated environments, while buyers are increasingly factoring supply compliance into procurement decisions rather than treating it as a separate administrative step.
Demand-Side Shifts in Diagnostic and Manufacturing Workflows
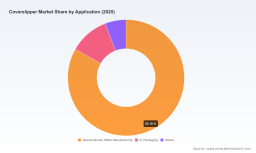
On the demand side, the most influential change is the continuing expansion of semiconductor wafer manufacturing applications alongside core histology and IC packaging uses. The application breakdown shows semiconductor wafer manufacturing as the largest demand segment, with IC packaging and other applications representing smaller but meaningful shares. This composition suggests that coverslippers are not solely confined to classical pathology workflows; they also serve precision handling and surface protection needs in advanced manufacturing contexts. As a result, demand-side growth is being shaped by two parallel dynamics: diagnostic laboratories seeking higher throughput and consistency, and manufacturing operations looking for reliable automated handling solutions for sensitive substrates. Each pathway favors different equipment priorities, which explains why some vendors emphasize modular design while others focus on specialized robotic handling or staining-integrated workstations.
Supply Chain and Cost Structure Dynamics
Cost structure and supply resilience are increasingly shaping procurement timing and product selection. Laboratorians and plant operators are sensitive not only to upfront equipment price, but also to consumable availability, service responsiveness, installation footprint, and the stability of adhesive or film supply. In a market where material choices and mounting media compatibility directly affect output quality, disruptions in consumables or inconsistent adhesive performance can create operational bottlenecks and erode confidence in automation. Consequently, equipment programs that emphasize reliable consumable compatibility, serviceability, and predictable operating costs are gaining preference over solutions that deliver short-term speed but introduce long-term workflow risk. This dynamic is especially important in regions where laboratory budgets are tightly managed and where capital equipment must justify itself through sustained uptime and minimal rework.
Competitive Landscape and Leading Strategies
The coverslipper market features a mix of specialized equipment manufacturers with distinct regional footprints and product philosophies. Several companies illustrate different strategic positions within the segment. SLEE medical GmbH, based in Nieder-Olm, Germany, has built a reputation around modular and automated coverslipping systems, including both glass and film-based solutions for histology slide preparation. Its presence in the market reflects a modular approach that appeals to laboratories wanting flexibility across slide types and workflow configurations. INTELSINT SRL, headquartered in Villarbasse, Italy, contributes to the automation narrative with fully automated coverslipping connected to broader histology laboratory automation systems. Its positioning emphasizes integration, which is particularly relevant for facilities that view slide preparation as part of a larger automated line rather than a standalone process.
DAKEWE (Shenzhen) Medical Equipment Co., Ltd. represents a strategy oriented toward combined workstation functionality and broader distribution reach from Shenzhen, Guangdong. Its offerings include robotic automated glass coverslippers and integrated workstations that combine staining and coverslipping. This approach targets laboratories seeking to consolidate functions and reduce manual transitions between steps. Sakura Finetek USA, Inc., based in Torrance, California, illustrates a consumables-and-equipment linkage strategy by developing film-based and glass automated coverslippers for anatomic pathology. Its product set highlights the importance of mounting media, adhesive performance, and solvent management in the commercial value proposition. Together, these players show that leadership in the coverslipper market is increasingly defined by the ability to align hardware with consumable chemistry, regulatory considerations, and workflow design.
Flip Flops Market
Strategic Positioning and Differentiation
The clearest differentiators in this market are not simply speed or footprint, but the degree to which equipment supports consistency, regulatory comfort, and consumable compatibility. Modular glass and film systems appeal to laboratories with varied specimen types, while integrated staining-and-coverslipping platforms attract operators focused on reducing hands-on handling and standardizing output. Film-based automated coverslippers with adhesive-backed solutions serve applications where mounting simplicity and compatibility with standard slides are priorities. Equipment that reduces solvent exposure or allows customized programs can create a practical advantage in environments where safety documentation and procedural control carry significant weight. These distinctions matter because they align with how laboratories actually evaluate total workflow performance, not just instrument specifications.
Evolution of the Market Structure
The market’s evolution appears to be moving toward incremental consolidation of workflow advantages rather than dramatic concentration of share. At current concentration levels, no single vendor dominates, leaving room for regional specialists, application-focused entrants, and integrated system builders to compete on fit rather than scale alone. Over the next several years, competitive pressure is likely to encourage further bundling of functions, more deliberate consumable-equipment matching, and greater emphasis on installation, training, and support as part of the commercial offer. New entrants may find opportunities in niche workflow configurations or regional distribution, while established players are likely to strengthen their position by improving reliability, service coverage, and compatibility with broader laboratory automation ecosystems. The practical result is a market where differentiation is increasingly executable through system design and operational support rather than through price competition alone.
Future Trends and Commercial Implications
Trend 1: Platform-Based Slide Preparation Will Become a Purchasing Norm
Over the next three to five years, coverslipping is likely to be evaluated less as an isolated task and more as a node within automated slide preparation platforms. Laboratories are expected to favor systems that coordinate staining, handling, and coverslipping with fewer manual touchpoints, provided those systems can demonstrate consistent output and manageable operating costs. The commercial implication is that suppliers offering modular connectivity, standardized consumables, and dependable service support will be better positioned than those competing primarily on basic instrument features. For vendors, this trend creates opportunities to expand value through workflow services, consumables programs, and integration consulting, rather than relying solely on equipment unit sales.
PW Consulting Health Care Research Center
Trend 2: Safety, Compliance, and Materials Compatibility Will Shape Product Roadmaps
Regulatory awareness and materials science will continue to influence product design and purchasing criteria. As mounting solutions evolve, equipment that accommodates adhesive-backed films, consistent slide dimensions, and reduced solvent exposure will likely gain traction in regulated environments. This trend is commercially important because it expands the relevance of consumable-partnership strategies and encourages equipment designers to build in flexibility for different film or glass formats. At the same time, it creates risk for products that depend on a narrow set of consumables or that cannot accommodate changes in mounting chemistry and safety practices. Buyers are likely to reward solutions that make compliance and reproducibility easier to manage on a day-to-day basis.
Sandals Market
Trend 3: Regional Variation Will Remain a Strategic Factor
Despite global growth in the market, regional demand characteristics are expected to persist. Different healthcare systems, manufacturing bases, and laboratory funding models will continue to shape procurement timing, equipment preferences, and service expectations. Asia Pacific’s substantial market presence alongside North America and Europe indicates that growth opportunities are not concentrated in a single geography, and that local support capability can be as important as product features. The risk side of this trend is that companies assuming uniform purchasing behavior across regions may misjudge implementation readiness, consumable availability, or service requirements. Successful strategies will likely require region-aware product positioning and a clear plan for installation, training, and after-sales support.
Actionable Guidance for Decision-Makers
For manufacturers, the immediate priority is to treat coverslipping equipment as an operational platform rather than a standalone instrument. That means investing in modular design, consumables compatibility, and service infrastructure that reduces friction during adoption. Companies should also clarify which customer segments they serve best—high-volume diagnostic laboratories, integrated histopathology lines, or manufacturing workflows with precision handling needs—and tailor product messaging accordingly. Differentiation will increasingly come from the reliability of the entire system, including mounting consistency, consumable supply stability, and the ease with which the equipment fits into existing lab processes.
For investors, the most relevant signal is that durable growth in this market depends on workflow adoption rather than speculative demand spikes. Capital deployment should be evaluated against assumptions about automation adoption curves, regulatory comfort, and regional service readiness. Companies with credible consumables alignment, flexible product architecture, and regional distribution strength may be better positioned than those dependent on narrow product lines or price-led competition. It is also prudent to monitor how integrated workstations and film-based automated systems gain acceptance, since these developments can shift purchasing behavior toward bundled solutions and recurring consumable relationships.
For procurement and laboratory leadership, the practical task is to expand evaluation criteria beyond unit price and basic throughput. Total cost of ownership, consumable compatibility, installation burden, operator training requirements, and service responsiveness should be treated as central to the decision because they determine whether automation delivers sustained value. Where possible, procurement teams should test compatibility with existing mounting media and slide formats before finalizing equipment choices, and should ensure that vendor support arrangements match the operational stakes of histology and pathology workflows. Selecting equipment that aligns with both current volume needs and likely future workflow changes can reduce the risk of rework, downtime, and compliance friction.
More detailed segmentation data, including regional and application splits, material-type breakdowns, and company-level strategic profiles, can support more targeted planning for sites, product portfolios, and procurement scenarios. Readers seeking granular market size estimates by region, application, and type, along with deeper company evaluations and scenario planning, can review the full research report for a more detailed view of the coverslipper market and its commercial implications.
For detailed analysis of this topic, please visit the official page: Coverslipper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com