

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Pharmaceutical & Biotechnology Environmental Monitoring Market: Why 5.9% CAGR Changes Everything

Strategic Shifts in the Pharmaceutical & Biotechnology Environmental Monitoring Market: Growth, Compliance, and Commercial Opportunity
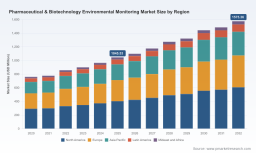
The pharmaceutical and biotechnology environmental monitoring market has entered a period of structural expansion, driven by tightening regulatory expectations, technological maturation, and a broader industry shift toward proactive contamination control. Valued at approximately 1.05 billion U.S. dollars in 2025 and projected to reach roughly 1.58 billion by 2032, the market is advancing at a compound annual growth rate of 5.9 percent over the 2020 to 2032 horizon. This trajectory reflects more than incremental demand; it signals a fundamental recalibration of how manufacturers, biotech firms, and research institutions manage environmental risk across sterile processing environments. For executives and strategic planners, the market’s growth is not merely a numbers story. It is a reflection of changing compliance postures, evolving operational philosophies, and the increasing integration of monitoring into daily quality systems rather than periodic audit preparation.
Worldwide Room Pressure Monitoring for Hospitals and Pharmaceutical Market
The market’s expansion has been steady rather than explosive, which itself is informative. Growth has been consistent through the 2020 to 2025 period, with revenue compounding as manufacturers reinvested in monitoring hardware, media, software, and microbiology services. This pattern suggests that environmental monitoring is moving from a compliance checkbox to an embedded operational capability. Yet the environment is not frictionless. Several structural challenges are shaping how companies allocate budgets, select technologies, and design long-term monitoring strategies. Recognizing these pressures is essential for anyone evaluating market entry, portfolio expansion, or procurement decisions in the sector.
Market Context and Core Challenges
The current market environment is defined by scale, regulatory pressure, and an ongoing tension between legacy practices and modern monitoring expectations. The overall revenue trajectory indicates a maturing market, but maturity does not mean uniformity. Companies are navigating a landscape where monitoring obligations are becoming more granular, more continuous, and more integrated into contamination control strategies. At the same time, the cost of implementation, validation, and ongoing compliance continues to strain resource allocation, especially for smaller manufacturers and research-driven organizations that must balance scientific throughput with regulatory readiness.
Challenge 1: Transitioning from Periodic Sampling to Continuous Monitoring
One of the central inflection points in the market is the shift away from episodic monitoring toward continuous, data-rich environmental surveillance. Regulatory expectations have increasingly emphasized ongoing viable monitoring in high-risk zones, with tighter limits and a stronger focus on trending, detection, and rapid response. For many organizations, this creates an operational challenge: continuous monitoring demands more than new equipment. It requires updated workflows, data infrastructure, scientific interpretation, and cross-functional coordination between quality, engineering, and manufacturing teams. Companies that treat environmental monitoring as a standalone activity often struggle to extract operational value, while those that embed it into contamination control strategy gain earlier warning capability and stronger process control.
Challenge 2: Compliance Complexity and Interpretation Risk
A second challenge lies in the widening gap between regulatory intent and practical implementation. Multiple standards and guidance frameworks now inform environmental monitoring programs, covering cleanroom classification, biocontamination control, aseptic processing validation, and broader facility monitoring expectations. While this layered framework strengthens quality systems, it also increases the burden of interpretation. Facilities must align monitoring frequency, method selection, alert and action levels, and trending protocols with both operational reality and regulatory language. Misalignment can lead to documentation gaps, inspection findings, or more serious consequences when monitoring failures intersect with sterile product risk. In practical terms, this raises the stakes for technology selection, training, and ongoing program governance.
Worldwide Pharmaceutical Equipment Maintenance Services Market
Challenge 3: Cost, Validation, and Total Cost of Ownership
A third pressure is economic. Environmental monitoring programs involve recurring expenditures across equipment acquisition, consumables, software upkeep, calibration, and external testing or consulting support when needed. In regulated environments, the commercial question is rarely limited to purchase price. Validation, integration with existing systems, change control, and long-term support can materially affect total cost of ownership. As a result, organizations are increasingly scrutinizing whether monitoring investments improve decision-making quickly enough to justify their operational footprint. This scrutiny favors solutions that reduce manual workload, improve data reliability, and connect monitoring outputs to actionable quality insights.
Key Drivers Shaping Market Direction
The market’s expansion is being propelled by a combination of technological evolution, regulatory momentum, demand-side change, and supply-chain dynamics. These forces do not operate in isolation; together, they are reshaping what manufacturers expect from monitoring programs and what suppliers must deliver to remain competitive.
Technology Innovation and the Rise of Integrated Monitoring
Technological advancement is a primary catalyst. Environmental monitoring is increasingly being treated as a connected system rather than a collection of discrete instruments. Continuous monitoring platforms, wireless sensing, automated trending, and software-driven data management are becoming more relevant in sterile manufacturing settings. This shift is especially visible in environments where temperature, humidity, pressure, and particulate conditions must be correlated with microbial monitoring results and process events. When monitoring data can be aggregated, trended, and reviewed efficiently, organizations gain faster detection of deviations and better support for contamination control decision-making.
Recent supplier activity reinforces this direction. One instrument provider expanded its integrated environmental monitoring and thermal validation platform with wireless sensors designed for sterile manufacturing environments, signaling a broader push toward consolidated data capture and reduced manual burden. Another company released an updated industry handbook focused on revised good manufacturing practice expectations and automated trending solutions, reflecting both the regulatory emphasis on continuous monitoring and the market’s need for practical implementation guidance. A third participant showcased continuous monitoring systems at a major industry event, underscoring the growing focus on compliance-oriented upgrades and integrated facility visibility. These moves indicate that the market is rewarding providers that simplify data integration, improve traceability, and support trending workflows.
Policy and Regulatory Environment
Regulatory developments are reshaping demand at the foundation. Revised EU GMP Annex 1 requirements have placed greater emphasis on continuous viable monitoring in high-risk zones, zero tolerance expectations where applicable, and full integration of monitoring into a contamination control strategy. The broader message is clear: environmental monitoring is no longer a standalone activity but a core control mechanism within a risk-based quality system. In parallel, sterile processing expectations from the FDA continue to reinforce the importance of validated aseptic processes, routine environmental monitoring, and evidence of effective contamination control. Together, these frameworks encourage more disciplined monitoring programs and create sustained demand for both instruments and advisory services.
The regulatory environment also encourages predictive and trend-based thinking. Updated expectations increasingly support data trending and risk-based approaches, highlighting the importance of early signal detection rather than reliance on reaction after an excursion. This creates demand for software and data tools that can support ongoing review, alerting, and documentation. In practice, regulatory momentum is helping convert environmental monitoring from a periodic obligation into a continuous quality enabler, which in turn sustains spending across monitoring equipment, media, software, and microbiology services.
Demand-Side Shifts in Pharmaceutical and Biotechnology Operations
Demand is also being shaped by changing operational priorities within the pharmaceutical and biotechnology sectors. As manufacturing complexity increases and sterile products become more central to commercial portfolios, organizations are placing greater importance on contamination control as a competitive and reputational necessity. Biotech firms, in particular, are expanding their manufacturing footprint and seeking scalable monitoring approaches that can support both development and commercial operations. Academic and research institutions contribute additional demand, especially where controlled environments must support reproducible science while maintaining regulatory-grade discipline.
Beyond compliance, there is a growing recognition that robust environmental monitoring reduces operational risk. Facilities that can detect drift earlier, interpret trends more effectively, and maintain stronger documentation are better positioned to manage investigations, minimize disruption, and support product quality. This mindset is changing procurement behavior: buyers are increasingly interested in solutions that offer reliability, support, and integration rather than lowest upfront cost alone.
Supply Chain and Cost Structure Dynamics
Supply-side dynamics are also influencing the market. Manufacturers and service providers are navigating the balance between specialized monitoring capabilities and broader operational efficiency. Consumables, media, and service components remain important recurring revenue streams, while hardware and software offerings are increasingly evaluated on how well they fit into broader facility systems. As organizations seek to streamline compliance operations, they often favor suppliers that can provide a more complete monitoring ecosystem or that can support integration across multiple monitoring domains. At the same time, validation and implementation complexity can slow adoption, making vendor support and application expertise a meaningful differentiator.
Competitive Landscape and Leading Strategies
The market features a mix of instrument specialists, life-science companies, sensor and validation providers, and service-oriented firms. This diversity reflects the breadth of environmental monitoring needs, which span particle counting, microbial air sampling, culture media, continuous environmental data management, thermal validation, and consulting or testing support. Competitive advantage in this space is increasingly determined not only by product performance but also by the ability to help customers operationalize compliance, manage data, and maintain long-term program integrity.
Strategic Positioning of Leading Players
Several companies illustrate different routes to differentiation. One U.S.-based specialist focuses on particle counters, microbial air samplers, and environmental monitoring systems designed for aseptic processing and cleanroom contamination control. Its positioning suggests strength in technical specificity and application-focused instrumentation for highly controlled environments. A French diagnostic and quality-control company offers active air samplers, culture media, and automated environmental monitoring platforms for pharmaceutical quality control and sterility assurance. This combination of consumables and platform-based monitoring creates a pathway to recurring engagement and integrated workflow support.
Another significant player operates across thermal validation, IoT-enabled continuous environmental monitoring, and sensor technologies for regulated environments. Its relevance in the market lies in bridging facility monitoring with validation and data management, an area of growing importance as organizations seek more continuous oversight. A German life-science supplier contributes microbial air monitoring systems and filtration-related solutions for cleanroom and barrier technology applications, reinforcing the market’s reliance on established contamination-control expertise. A major U.S. science and manufacturing company provides environmental monitoring plates, process analytical systems, and air samplers optimized for contamination control, benefiting from broad operational scale and cross-product integration.
Additional participants add further dimensions to the competitive landscape. One global science and technology company’s monitoring instruments and monitoring solutions support particulate and environmental oversight in pharmaceutical cleanrooms, reflecting the role of diversified industrial portfolios in this market. A Finnish provider offers continuous monitoring systems for temperature, humidity, pressure, and particle monitoring in GxP-regulated facilities, emphasizing compliance-oriented data management. A U.S.-based company delivers specialized monitoring instrumentation and related monitoring solutions for pharmaceutical cleanrooms, while another U.S. firm provides precision environmental monitoring sampling, testing, and consulting services, highlighting the continued importance of expert support alongside hardware and software.
Differences in Value Creation
These companies do not compete on identical terms. Some derive advantage from deep application expertise and specialized instrumentation. Others compete through broader platform integration, consumables ecosystems, or service-led engagement. The most differentiated offerings tend to reduce friction in daily operations: they make trending easier, improve data visibility, support validation and change control, and help teams act on monitoring information sooner. In a market where compliance burden and operational efficiency are both high, that operational simplicity often matters as much as instrument precision.
Market Structure and Evolution
The market remains moderately concentrated, with the largest players holding meaningful share, but it is not static. Consolidation pressures exist where end users prefer fewer suppliers, broader platforms, and simplified vendor management. At the same time, specialization remains valuable because environmental monitoring covers multiple technical domains. New entrants and adjacent players can gain traction by solving specific pain points, such as wireless sensing, software-driven trending, or integrated compliance workflows. The likely evolution is a hybrid landscape: established leaders strengthen platform and service capabilities, while targeted innovators capture demand around connectivity, data use, and specialized monitoring needs. For buyers, this means the market is increasingly offering more complete solutions, but also requiring clearer evaluation criteria around integration, support, and long-term program fit.
Forward-Looking Trends and Commercial Opportunities
Looking ahead over the next three to five years, several trends are likely to shape both market growth and commercial opportunity. These trends are not speculative; they follow directly from current regulatory direction, technology adoption patterns, and the operational realities of sterile manufacturing.
PW Consulting Health Care Research Center
Trend 1: Monitoring Becomes More Continuous, Connected, and Actionable
Environmental monitoring programs are expected to become more continuous and more tightly integrated with facility data systems. Wireless sensing, centralized data collection, automated trending, and easier review workflows will likely become standard expectations rather than premium features. This trend creates commercial opportunity for providers that can reduce manual effort, strengthen data reliability, and help teams interpret results in context. It also rewards organizations that can link monitoring outputs to investigation workflows, contamination control strategy updates, and operational decision-making. The broader opportunity lies not just in collecting more data, but in making that data usable for quality and manufacturing teams.
Trend 2: Risk-Based, Strategy-Integrated Monitoring Gains Ground
As regulatory expectations continue to emphasize risk-based approaches and contamination control strategy integration, monitoring programs will increasingly be judged on how effectively they support proactive risk management. This means alert and action level design, trend interpretation, and response protocols will matter as much as measurement itself. Companies that can help customers align monitoring with risk assessment, deviation management, and ongoing program review are well positioned. The commercial implication is that environmental monitoring will be sold and evaluated more often as part of a quality-system solution than as a standalone instrument purchase.
Trend 3: Services, Software, and Mixed Models Expand
The market’s services and software components are likely to grow in importance as organizations seek to manage complexity without overburdening internal teams. Microbiology services, consulting, validation support, and software-enabled monitoring management can help facilities bridge capability gaps, especially where staffing, expertise, or integration resources are constrained. Mixed operating models may become more common, with companies combining in-house monitoring with external expertise for specialized testing, program review, or surge support. For suppliers, this opens opportunities beyond hardware, particularly in recurring service relationships and software-enabled workflows that improve program consistency.
Risk Factors and Uncertainty
Despite the constructive outlook, uncertainty remains. Regulatory interpretation can vary across jurisdictions and inspection contexts, making compliance outcomes less predictable even when programs are well designed. Implementation challenges, including validation burden, data integration complexity, and staff training, can slow adoption of newer monitoring models. Cost sensitivity may also intensify if operational budgets face pressure, forcing buyers to prioritize essential monitoring needs over broader platform investments. In addition, enforcement activity around monitoring failures can heighten scrutiny and change buyer behavior quickly, particularly when sterile product risk is involved. These factors do not threaten the market’s overall direction, but they do suggest that success will depend on practical implementation, strong support, and the ability to demonstrate measurable value.
Strategic Recommendations for Decision Makers
For Manufacturers and Quality Leaders
Prioritize monitoring programs that align with contamination control strategy rather than treating environmental monitoring as a siloed compliance task. Invest in solutions that improve trending, data review, and deviation response, because the operational value of monitoring depends on how quickly and reliably results can be interpreted and acted upon. Where possible, evaluate total cost of ownership across equipment, consumables, software, validation, and support, and ensure that chosen systems can fit into existing quality and facility workflows without creating unnecessary complexity.
For Investors and Strategic Planners
Focus on the segments and capabilities most likely to benefit from regulatory-driven continuity and integration. Recurring demand for media, services, software-enabled monitoring, and integrated platforms is supported by the market’s shift toward continuous oversight and contamination control strategy requirements. Look for providers with clear application expertise, strong service models, and the ability to reduce implementation friction. Also watch for consolidation dynamics, since end users increasingly prefer fewer relationships and more coherent solution sets, while specialized innovators may still capture valuable niches around connectivity, data use, and high-risk-zone monitoring.
For Procurement and Operations Decision Makers
Define evaluation criteria around long-term usability, integration, validation support, andvendor responsiveness rather than initial price alone. Because environmental monitoring programs touch multiple teams and persist over long periods, the best choice is often the one that can be sustained with minimal disruption while maintaining data integrity and compliance readiness. Request evidence of practical implementation support, trending capability, and compatibility with existing systems, especially if continuous monitoring and data aggregation are part of the planned program. Consider whether additional consulting or microbiology services may be needed to strengthen program design and response capability over time.
Closing Perspective
The pharmaceutical and biotechnology environmental monitoring market is expanding within a broader shift toward continuous, risk-based, and strategy-integrated contamination control. Growth is supported by regulatory expectations, technological maturation, and the operational need to detect and respond to environmental risk more effectively. At the same time, the market rewards practical implementation as much as technical capability. Organizations that approach monitoring as part of their quality system, rather than as a standalone instrument purchase, are better positioned to capture both compliance value and operational resilience. For companies and investors seeking a fuller picture of segment dynamics, regional variation, competitive share patterns, and tailored scenario analysis, the complete research report provides the deeper, structured data needed to refine strategy and prioritize investment.
For detailed analysis of this topic, please visit the official page: Pharmaceutical & Biotechnology Environmental Monitoring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com