

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Helium Market: Why 2032 Projected $1.3B Scale Redefines LNG Supply Dynamics and Regional Strategy

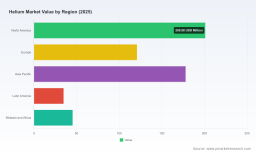
Helium Market Outlook: Strategic Trends and Commercial Opportunities (2026–2032)
The global helium market is entering a phase of structural transition, driven by expanding supply from new production hubs, evolving geopolitical and trade conditions, and intensifying demand from technology-intensive and infrastructure-heavy sectors. Output for the base year of 2025 reached approximately 580.0 million USD, with the market projected to grow at a compound annual rate of 12.75 percent through 2032, when total market value is expected to approach 1,290.0 million USD. This trajectory reflects more than incremental pricing adjustments; it signals a broader realignment in how helium is sourced, stored, contracted, and deployed across end-use industries. For executives, procurement leaders, and capital allocators, the opportunity lies in recognizing where structural advantages are forming and how to position operations before volatility reshapes supply relationships.
Market Landscape and Defining Challenges
The headline trajectory masks several underlying tensions that will determine which participants capture durable value. Supply diversification has accelerated, yet the market remains sensitive to production timing, logistics readiness, and the pace at which new volumes translate into reliable contracted supply. At the same time, demand patterns are shifting as semiconductor manufacturing, advanced diagnostics, and infrastructure programs increase their dependence on high-purity and stable helium inputs. Three challenges stand out as immediate inflection points for commercial strategy.
Supply Geographic and Source Concentration
A meaningful share of global helium continues to originate from a limited set of natural gas and LNG-linked production streams, and the geography of those sources is changing as new fields and processing facilities come online. Diversification is advancing, but the transition is uneven, and not every new source immediately improves delivery reliability for end users due to processing scale, logistics constraints, or contract structures. Buyers and investors should treat source diversification as a multi-year capability build rather than a short-term remedy.
Geopolitical and Trade Friction Affecting Availability
Trade policy remains a powerful force in helium availability. United States sanctions that imposed an import ban on helium from Russia continued into 2025, altering sourcing options for buyers who previously relied on or evaluated Russian-origin volumes. This has reinforced the value of alternative supply corridors and increased attention on North American, Middle Eastern, and European production and logistics networks. Companies planning multi-year helium requirements should incorporate sanction-aware sourcing assumptions into supply design and contract negotiations.
Grade, Purity, and Cost Volatility
Helium is not a single commodity in practice; grade specifications, purity thresholds, and delivery formats materially affect both usability and cost. In 2025, sales of Grade-A helium, defined as greater than 98 percent helium, were an estimated 81 million cubic meters valued at an estimated 970 million USD, while the estimated base price for Grade-A helium was about 12 USD per cubic meter, equivalent to roughly 330 USD per thousand cubic feet, with producers posting surcharges. This pricing environment indicates that base valuations can diverge from realized transaction prices, especially when logistical strain, capacity tightness, or quality premiums come into play. Organizations that standardize their purity requirements and lock in predictable delivery terms are better positioned to manage exposure to surcharge cycles.
Key Drivers Shaping Market Direction
The market's expansion is being shaped by a combination of technological, regulatory, demand, and supply-side forces. Each has commercial implications that extend beyond volume growth alone.
Technological and Processing Innovation
Helium production is increasingly supported by dedicated wells and on-site processing technologies that reduce reliance on co-product recovery from broader gas streams. A notable example is the Rudyard Project in Montana, where helium production began in July 2025 with dedicated wells and an on-site PSA processing plant operational. The practical significance of this model is greater control over output quality and scheduling, which can translate into more predictable supply for industrial and high-purity applications. In parallel, storage and buffer capacity are improving in certain regions. A helium storage cavern was brought online in Beaumont, TX, capable of storing excess helium production, adding a mechanism to smooth short-term supply fluctuations. Together, these developments support a market in which processing flexibility and storage redundancy are becoming differentiating capabilities rather than optional additions.
Policy, Regulation, and Sanctions Environment
Regulatory actions continue to reshape sourcing pathways. In addition to continued import restrictions involving Russian-origin helium, domestic policy can directly influence project economics and timelines. Pulsar Helium Inc. welcomed new Minnesota helium regulation as the Topaz Project advanced toward first production, illustrating how localized regulatory clarity can accelerate development and reduce uncertainty for new producers. For downstream users, policy risk is increasingly a planning variable: sourcing strategies must account for differing regulatory regimes across producing regions, as well as the possibility that trade measures or export conditions could shift available supply pools over time.
Worldwide Electronic Grade Helium Market
Demand-Side Transformation in Critical Industries
Helium demand is being reinforced by applications where purity, continuity, and thermal properties are difficult to substitute. High-purity helium is essential in aerospace, semiconductor fabrication, and electronics manufacturing, where process stability and contamination control are non-negotiable. At the same time, logistics and supply chain operations, along with smart city and infrastructure programs, are expanding their use of helium-linked systems and services as they scale sensing, monitoring, and specialized process requirements. The commercial implication is that demand is becoming less elastic in key segments: replacements are limited, and interruptions carry operational and quality risks that buyers are increasingly unwilling to absorb. This supports the case for long-term arrangements and closer integration between producers and end users.
Supply-Side Economics and Contract Structures
Cost dynamics are influenced by both physical supply and commercial structures. The presence of surcharges, the introduction of new domestic production, and the expansion of long-dated supply agreements all point toward a market where price formation is becoming more segmented. Buyers are increasingly evaluating total cost of supply rather than base price alone, factoring in delivery reliability, grade consistency, storage availability, and contract duration. For producers and distributors, this shifts competitive advantage toward the ability to offer dependable, specification-aligned supply with manageable logistics exposure.
Competitive Landscape and Strategic Positioning
The helium market is characterized by a mix of large integrated suppliers, midstream and processing specialists, and emerging exploration and production companies building dedicated helium projects. Market concentration is moderate, with the top three firms accounting for approximately 33.5 percent of the market and the top five reaching about 48.0 percent. That level of concentration leaves room for both scale-driven advantage and niche differentiation, especially as new supply comes online and contract structures evolve.
Established Suppliers and Their Advantages
Several major suppliers are positioned around global reach, processing scale, and long-term contractual relationships. Air Products and Chemicals, Inc., headquartered in Allentown, Pennsylvania, is a leading helium producer and supplier of gaseous and liquid helium from LNG, methane, and CO2 sources, supported by a global distribution network. Its breadth across source types and geographies supports flexibility in meeting varied customer requirements. Linde plc, based in Dublin, Ireland, operates as a major helium extraction, purification, and distribution provider with facilities supporting semiconductor and industrial-grade helium, giving it a strong position in high-specification industrial demand. Air Liquide S.A., headquartered in Paris, France, supplies high-purity helium for aerospace, semiconductors, and electronics, with long-term supply contracts reinforcing continuity for customers whose processes depend on specification stability.
Messer Group, located in Bad Soden, Germany, produces and distributes industrial and specialty gases including helium for metals processing and manufacturing, aligning its offering with sectors that require dependable bulk and specialty supply. Iwatani Corporation, headquartered in Osaka, Japan, supplies helium through Ras Laffan plants with a focus on industrial and high-purity applications, reflecting the importance of Middle Eastern-linked supply corridors for certain regional demand centers. QatarEnergy LNG, based in Doha, Qatar, is the world's largest helium producer, with its Helium 2 plant supplying approximately 25 percent of global output for liquid helium contracts, making it a central participant in global availability and contract formation. Gazprom PJSC, in Moscow, Russia, remains a significant producer from natural gas fields with both exports and domestic supply, though access patterns are influenced by sanctions and trade dynamics. ExxonMobil Corporation, in Spring, Texas, produces helium from natural gas with integrated extraction and sales, reinforcing the role of major integrated energy operations in supply.
Helium Gas Market
Emerging Producers and the Diversification Theme
A second layer of competitive dynamics comes from newer producers targeting dedicated helium resources and localized processing. HeliumOne Global Ltd, based in London, United Kingdom, is developing and operating helium projects including Galactica-Pegasus with purification plant operations,representing a project-focused approach to building dedicated supply. Helix Exploration Plc, also headquartered in London, began production at its Rudyard Project in Montana in July 2025, with dedicated wells and an on-site PSA processing plant operational, and in March 2026 signed a lease for a high-pressure jumbo tube trailer to support production ramp-up amid global supply disruptions. Pulsar Helium Inc., in Canada, is advancing the Topaz Project in Minnesota toward commercial production, with progress supported by evolving regional regulation as of May 2026. U.S. Energy Corp., in Texas, is targeting commercial output through helium production and development activity. These entrants matter because they broaden the supply base and can improve regional availability, especially when logistics and storage support keep pace with production growth.
Strategic Trends in the Competitive Set
Two competitive trends are becoming visible. First, long-term contracting is increasingly used to secure predictable supply and reduce exposure to spot volatility. QatarEnergy LNG signed a 15-year helium supply agreement with Uniper starting September 2025, and earlier signed a 20-year helium supply agreement with Guangzhou Guanggang Gases & Energy Co., Ltd. in February 2025. These agreements illustrate how major producers and offtake partners are aligning around duration, volume visibility, and multi-year planning horizons. Second, the market is showing signs of both consolidation pressure and fragmentation potential: large integrated suppliers retain advantages in scale and reach, while smaller dedicated producers can compete on source specificity, local logistics, and agility in serving targeted demand pockets. The net effect is a market in which differentiation will increasingly come from reliability, grade control, logistics capability, and contract design rather than from volume claims alone.
Forward Outlook: Trends Defining the Next 3–5 Years
Looking ahead, the market's direction will likely be shaped by the interaction of new supply, logistics and storage capacity, contracting behavior, and demand stickiness in critical applications. Three trends are especially relevant for strategic planning.
Broader Source Diversification with Uneven Reliability Benefits
New production from the United States and other regions is expected to continue expanding the supply base, but diversification does not automatically resolve availability risk unless it is paired with processing scale, storage, and transport readiness. Buyers should anticipate a period in which additional volumes become available in waves, with reliability improving more slowly than gross output. Commercial strategies that assume immediate normalization of supply may underestimate the value of storage buffers and multi-source contracts.
Longer Contracts and More Segmented Pricing
The trend toward long-dated supply agreements and visible surcharges suggests that pricing will become more segmented by grade, delivery format, region, and contract length. This creates both opportunity and complexity. Organizations with stable, specification-defined requirements can use longer contracts to secure continuity and reduce uncertainty, while those with flexible needs may need to manage a mix of contract types and delivery options. Price negotiation will increasingly need to account for total cost of supply, including logistics and quality consistency.
PW Consulting
Infrastructure and Storage as Strategic Enablers
Storage and logistics improvements are likely to play a larger role in market stability. The availability of storage capacity in key locations and the development of high-pressure transport assets can reduce the impact of short-term production and demand mismatches. Participants that invest early in logistics planning, storage access, or supply-chain coordination may gain an advantage in securing dependable supply during tight periods. This is particularly relevant for end users in semiconductor, healthcare, aerospace, and infrastructure-linked applications, where interruptions carry high operational costs.
Areas of Uncertainty
Several factors could alter this trajectory. Trade and sanction conditions may continue to influence which sources are accessible to which buyers. New production may ramp more slowly than anticipated if processing, permitting, or logistics face delays. Demand could shift if substitutes or process changes reduce helium intensity in some applications, although critical-use segments are likely to remain robust. Finally, price dynamics may remain volatile if supply additions and demand growth do not stay aligned, especially around high-purity grades and liquid helium supply.
Actionable Implications for Decision Makers
For Manufacturers and High-Specification End Users
Standardize purity and delivery requirements across production sites and evaluate total cost of supply rather than headline price. For processes where helium quality and continuity are critical, prioritize long-term arrangements and assess suppliers based on grade control, storage access, and logistics capability as well as source geography. In addition, map exposure to sanctioned or constrained supply corridors and build alternative sourcing options that can be activated if trade conditions shift.
For Investors and Project Stakeholders
Focus on the intersection of dedicated helium resources, processing readiness, and logistics support. Projects that combine production with on-site purification, storage connectivity, or transport capability are better positioned to convert resource potential into commercial supply. Evaluate contract structures and offtake visibility, since durable agreements can improve project economics and reduce exposure to near-term price fluctuation. Also monitor regional regulatory developments, since favorable local frameworks can accelerate timelines and lower execution risk.
For Procurement and Supply Chain Leaders
Treat helium sourcing as a resilience priority rather than a purely transactional purchase. Diversify across suppliers and regions where feasible, but avoid assuming that diversification alone resolves reliability challenges; pair it with storage planning and contract terms that protect against surcharges and short-term disruptions. Where possible, align supplier relationships with anticipated multi-year demand and clarify specifications early to reduce rework, rejection risk, and emergency purchasing premiums.
Closing Perspective
The helium market is moving from a period of tightness and reactive sourcing toward a more complex environment defined by new supply streams, evolving trade conditions, and growing demand from applications that cannot easily substitute away from helium's properties. Growth to nearly 1,290.0 million USD by 2032 is plausible within the current trajectory, but the commercial winners will be those who plan around reliability, grade consistency, logistics, and contract design rather than volume headlines alone. For organizations seeking detailed regional breakdowns, application-level demand profiles, supplier-level benchmarking, and scenario-based sourcing guidance, a comprehensive study can provide the granularity needed to convert these market-wide observations into asset-specific and contract-specific decisions.
For detailed analysis of this topic, please visit the official page: Helium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com