

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Tissue Paper Converting Machines Market: Why 4.5% CAGR Through 2032 Changes Everything

Strategic Trends and Commercial Opportunities in the Tissue Paper Converting Machines Market
The tissue paper converting machines market stands at a pivotal juncture, shaped by steady demand growth, technological evolution, and a shifting regulatory landscape. Over the past five years, the market has expanded from approximately 1,200 million USD in 2020 to roughly 1,550 million USD in 2025, reflecting a compound annual growth rate of around 4.5 percent through 2032. This trajectory signals more than a simple volume increase; it indicates a structural reconfiguration of how tissue products are manufactured, packaged, and distributed. For executives and investors, the question is no longer whether demand will persist, but how operational strategies must adapt to capture margin, resilience, and relevance in a market that is simultaneously consolidating and fragmenting.
Mapping the Market Canvas
The market's current scale reflects a mature but still expanding base. The growth from 2020 to 2025 has been underpinned by consistent household and commercial consumption, retrofit activity on aging converting lines, and incremental automation upgrades. Looking ahead to 2032, the projected expansion to more than 2.1 billion USD suggests that conversion capacity will continue to grow, though the pace and geographic distribution will vary. The revenue concentration among the top three players, at roughly 42 percent, and the top five at around 58 percent, indicates a moderately consolidated field where scale, technology access, and service networks provide meaningful advantages. Yet the remaining share is distributed across a diverse set of manufacturers, regional specialists, and cost-oriented entrants, creating a competitive environment where differentiation increasingly hinges on reliability, integration capability, and speed to market rather than price alone.
Key Challenges and Inflection Points
The sector faces a cluster of interrelated challenges that are reshaping investment and deployment decisions.
Tissue Paper Market
- Regulatory pressure on pulp traceability and sourcing. The EU Deforestation Regulation, which took full effect in late 2024, requires traceability of wood pulp used in tissue production. This regulation is not merely a compliance checkbox; it alters supplier qualification processes, documentation workflows, and procurement risk for converters who must now demonstrate chain-of-custody integrity for raw materials.
- Trade and tariff volatility affecting input costs. Geopolitical trade tensions, including U.S.-Canada-Mexico tariff dynamics, have introduced uncertainty into pulp and recovered-paper supply chains. Cost structures that were once predictable are now subject to shifts driven by policy changes, logistics disruptions, and currency movements.
- Demand for higher speeds, automation, and quality consistency. Rising consumption of hygiene products is driving investments in automation and high-speed converting lines, but this push collides with the need for flexibility. Operators must balance throughput with changeover efficiency, product differentiation, and shelf-ready packaging requirements, all while maintaining uptime and minimizing waste.
These challenges create a clear inflection point: manufacturers and converters can no longer treat converting equipment as a standalone capital purchase. Instead, decisions must account for upstream raw-material compliance, downstream packaging and logistics expectations, and the operational cost of downtime or rework.
PW Consulting Automotive & Machinery Research Center
Key Drivers Shaping the Market
Technological Innovation and Confluence of Automation
Innovation in tissue converting is moving beyond incremental speed gains toward integrated, intelligent line architectures. Leading equipment suppliers are emphasizing complete line integration that spans rewinding, folding, embossing, and packaging, reducing the need for standalone machines and simplifying changeovers. Trade show activity in 2025 and 2026 illustrates this direction: Futura S.p.A. showcased integrated converting lines at Tissue World Miami in 2026, while Gambini S.p.A. completed its North American market offer with new Comparable-TADs and TAD converting line previews at Miami events the same month. OMET presented tissue converting solutions at MIAC 2026 in Lucca, and PCMC highlighted innovations including the Meridian Elite+ at FTA FORUM INFOFLEX 2026. United Converting Tissue S.r.l. emphasized simplified, reliable converting solutions at Tissue World Düsseldorf 2025. These appearances reflect a broader pattern: manufacturers are positioning integrated, automation-ready platforms that can be configured for multiple product formats, with an emphasis on maintenance simplicity and configuration flexibility.
For decision-makers, this trend means that equipment evaluation should extend beyond machine specifications to include total line productivity, compatibility with existing infrastructure, and the vendor's ability to support service, training, and spare-parts logistics. The value proposition is shifting from "how fast can it run" to "how reliably can it run across a range of products and changeovers."
Policy and Regulatory Environment as a Strategic Variable
Regulatory developments are increasingly embedded in capital planning. The EU Deforestation Regulation's traceability requirements for wood pulp are prompting converters to reassess supplier relationships and documentation processes. In parallel, geopolitical tariff dynamics affecting pulp and recovered paper supply chains are altering cost forecasting and sourcing strategies. These forces do not merely add compliance overhead; they influence which equipment configurations make sense. For example, lines that reduce material waste, support tighter quality control, and improve yield can soften the impact of input-cost volatility. Likewise, equipment that facilitates traceability and batch integrity can help converters meet regulatory expectations without compromising throughput.
The practical implication is that regulatory and trade considerations should be integrated into vendor selection, line design, and operational planning. Equipment that supports consistent quality, minimal waste, and clear process control can become a buffer against upstream uncertainty.
Demand-Side Shifts in Household and Commercial Settings
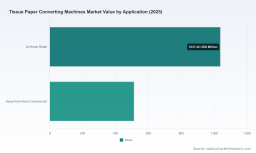
Demand for hygiene products continues to drive investments in automation and high-speed converting lines. The at-home retail segment remains the larger revenue pool, supported by staple household consumption, while the away-from-home commercial segment provides a complementary growth channel tied to hospitality, healthcare, and institutional use. These segments have different requirements: retail channels often emphasize shelf-ready packaging, consistent formatting, and brand presentation, while commercial channels may prioritize volume, reliability, and format flexibility. The result is a demand environment that rewards converters capable of serving multiple channels with adaptable equipment and efficient changeover protocols.
This demand diversity also encourages product differentiation. Folded tissue, paper napkins, toilet rolls, and kitchen rolls each carry distinct converting needs, and lines that can be configured across these formats offer downstream flexibility. In practical terms, converters are increasingly looking for equipment that can support product mix changes without sacrificing speed or quality, enabling them to respond to retail buyer requirements and commercial volume demands with greater agility.
Supply Chain and Cost Structure Realignment
The cost and sourcing environment is being reshaped by both environmental considerations and macroeconomic forces. Recovered paper has become a significant input in tissue production due to environmental concerns and cost-efficiency goals, and this shift influences not only raw-material procurement but also equipment requirements around fiber handling, consistency, and yield optimization. At the same time, tariff and trade tensions can affect pulp availability and pricing, prompting converters to think more carefully about inventory strategies, supplier diversification, and machine uptime.
From an equipment perspective, these supply-chain dynamics favor lines that support efficient material use, robust process control, and rapid troubleshooting. The cost of downtime is amplified when input costs are volatile or when compliance documentation must be maintained, making reliability and service responsiveness strategic priorities rather than operational niceties.
Competitive Landscape and Leading Strategies
Strategic Positioning and Differentiation Among Core Players
The competitive field combines established Western manufacturers with regional specialists and cost-oriented entrants. Several patterns are evident in how leaders are positioning themselves.
- Integrated line capability and automation focus. Companies such as Futura S.p.A. and Gambini S.p.A. emphasize integrated converting lines with automation enhancements, testing facilities, and product-format flexibility. Their positioning suggests a strategy built around end-to-end solutions, service ecosystems, and the ability to support both consumer and away-from-home products.
- Reliability and ease of configuration. United Converting Tissue S.r.l. promotes simplified, reliable lines for roll and folded products with a focus on ease of maintenance and configuration. This approach appeals to operators who value predictable performance, straightforward servicing, and lower complexity in daily operation.
- Specialization and format depth. OMET supplies automatic tissue converting lines, including ASV and AS models for interfolded and paper towel products, while 9. Septembar brings more than 40 years of specialization in napkins, facial tissue, and related products. C.G. Bretting Manufacturing Co., Inc. specializes in tissue and towel converting equipment including folders, interfolders, and custom lines. These players illustrate how format-specific expertise and custom configuration can create defensible niches.
- Cost-effective solutions and packaging integration. Baosuo Paper Machinery Manufacture Co., Ltd. manufactures tissue converting machines and full packaging systems with a focus on cost-effective solutions, reflecting a value-oriented positioning that can be attractive in price-sensitive deployment contexts.
- Complete lines under a broader industrial platform. Paper Converting Machine Company (PCMC), operating under Barry-Wehmiller, provides complete tissue converting lines including rewinding, folding, embossing, and packaging. Its structure highlights the advantage of being able to offer integrated equipment with broader industrial capabilities and service reach.
The strategic message is clear: differentiation is increasingly built on integration, automation, service reliability, and format flexibility. Price matters, but it is not the only axis of competition. Vendors that can reduce changeover friction, support consistent output, and deliver dependable after-sales support are positioning themselves to capture share in a market where downtime and quality variability carry real financial consequences.
Market Structure Evolution: Consolidation, Fragmentation, and New Entrants
The market's concentration, with the top three firms holding roughly 42 percent and the top five around 58 percent, suggests room for both consolidation and specialized fragmentation. Consolidation can emerge through partnerships, acquisitions, or the expansion of integrated service networks, particularly among manufacturers that can offer complete lines and cross-region support. At the same time, fragmentation persists because regional demand patterns, product-format requirements, and cost structures differ enough to sustain local and niche players.
New entrants and regional specialists continue to find opportunities, especially where they can combine cost advantages with targeted format expertise or local service responsiveness. The presence of companies from North America, Italy, Serbia, and China reflects a geographically diverse supply base, each with distinct strengths. North American and Italian manufacturers often emphasize integration, automation, and brand recognition, while other regional players may compete on price, customization, or proximity to specific customer segments. This diversity means that buyers have more options but also face a more complex evaluation environment, where the right choice depends on product mix, throughput needs, compliance posture, and total cost of ownership.
Future Trends and Commercial Opportunities
Trend 1: Integrated, Automation-Ready Converting Lines as the Default Expectation
Over the next three to five years, integrated converting lines with automation-ready architectures are likely to become more common as operators seek to reduce complexity, improve uptime, and support multiple product formats. The commercial opportunity here lies in vendors and converters who can demonstrate measurable gains in changeover efficiency, waste reduction, and service responsiveness. For equipment makers, this trend favors platforms that are modular, configurable, and supported by strong documentation and service networks. For converters, it favors strategies that prioritize total line productivity over isolated machine specifications.
The risk is that automation and integration promises can outpace real-world implementation. Lines that appear seamless on paper may require significant site preparation, training, and process reengineering. Decision-makers should assess not only the equipment but also the operational changes required to realize the expected benefits.
Trend 2: Compliance and Traceability as Competitive Differentiators
Regulatory requirements such as the EU Deforestation Regulation, combined with ongoing trade and tariff volatility, are elevating traceability and sourcing integrity from operational concerns to strategic differentiators. Over the coming years, converters that can demonstrate reliable chain-of-custody practices and consistent quality control may gain advantages in buyer qualification, market access, and risk management. Equipment and process designs that support batch integrity, documentation, and material efficiency will become more valuable.
The opportunity is twofold: converters can use compliance readiness as a selling point to retailers and commercial buyers, and equipment suppliers can highlight features that support traceability and material control. The risk is that compliance requirements may intensify, requiring ongoing updates to documentation, supplier qualification, and internal controls. Organizations that treat compliance as a one-time project rather than a continuous capability may face recurring friction.
Trend 3: Demand Diversity Driving Format Flexibility and Channel-Specific Solutions
The coexistence of strong at-home retail demand and steady away-from-home commercial demand is likely to sustain a need for format flexibility and channel-aware converting strategies. Folded tissue, paper napkins, toilet rolls, and kitchen rolls each require different handling, and retail channels often place additional emphasis on shelf-ready packaging and presentation. As a result, converters that can shift between formats efficiently and adapt packaging to channel expectations will be better positioned to capture demand across segments.
The commercial opportunity lies in equipment and service models that support rapid reconfiguration, consistent output across formats, and packaging integration that aligns with retail or commercial requirements. The risk is that trying to serve too many formats without sufficient process control can erode quality and uptime. The most successful operators will likely be those that define a clear product-mix strategy and match equipment and staffing to that strategy, rather than pursuing maximum flexibility without operational discipline.
Box Making Machines Market
Actionable Guidance for Decision-Makers
For Manufacturers and Equipment Suppliers
- Position integration and support, not just speed. Buyers increasingly evaluate total line performance, changeover efficiency, and after-sales support. Emphasize configurations that reduce complexity, improve uptime, and accommodate multiple formats, and ensure service documentation, training, and spare-parts availability match the promised capability.
- Embed compliance and traceability into the value proposition. With traceability requirements and trade volatility affecting pulp and recovered-paper inputs, equipment that supports material efficiency, batch consistency, and process control can become a strategic asset. Highlight features that help converters manage input variability and documentation burdens.
- Sharpen segmentation by format and channel. Toilet rolls, kitchen rolls, folded tissue, paper napkins, and stand-alone systems each have distinct needs. Tailor offerings and messaging to these differences, and consider channel-specific packaging and configuration options that align with retail and commercial expectations.
For Investors and Strategic Buyers
- Evaluate total cost of ownership and service reach. In a market where downtime and quality variability carry real costs, service networks, training, and parts availability can be as important as initial capital cost. Assess vendors on their ability to deliver reliable support across the deployment lifecycle, not just on headline specifications.
- Watch for consolidation and capability bundling. The concentration among leading players suggests potential for further integration through partnerships or acquisitions that expand integrated-line offerings, service coverage, or regional reach. Check whether a vendor's roadmap includes stronger integration, automation, or compliance support that aligns with long-term market direction.
- Factor regulatory and trade risk into sourcing and planning. Pulp traceability, recovered-paper demand, and tariff dynamics can influence input costs and supplier stability. Diversify sourcing where possible, and favor equipment and processes that reduce waste and improve yield to buffer against volatility.
For Converters and Procurement Teams
- Align equipment choices with product-mix and channel strategy. Define the formats, throughput ranges, and packaging requirements that matter most to your market, then match equipment capability to that strategy. Avoid over-investing in flexibility that your operations cannot manage consistently.
- Prioritize reliability and changeover efficiency. In an environment of input-cost volatility and compliance demands, uptime and consistent output are critical. Evaluate changeover procedures, maintenance access, and training requirements alongside speed and automation features.
- Use compliance readiness as a commercial lever. If traceability and sourcing integrity matter to your buyers, ensure your processes and equipment support those expectations. This can become a competitive advantage in retail and commercial qualification, especially where buyers increasingly scrutinize supply-chain responsibility.
The tissue paper converting machines market is evolving from a volume-driven equipment space into a more nuanced environment where integration, compliance, format flexibility, and service reliability shape competitive outcomes. The data points to steady growth, but the real value lies in how organizations translate that growth into operational advantage. For those seeking a more detailed view of segment dynamics, regional patterns, and company-level positioning, a deeper dive into the full research report can provide the granular data and customized context needed to turn these trends into concrete plans.
For detailed analysis of this topic, please visit the official page: Tissue Paper Converting Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com