

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Electrophysiology Devices Market: How 10.95% CAGR Redefines Competition

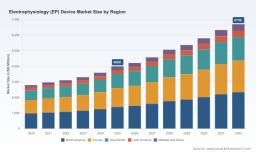
The Electrophysiology Device Market: Navigating a Decade of Transformative Growth
Market Current State and Core Challenges
The global electrophysiology (EP) device market has entered a phase of sustained expansion, driven by an aging population, the rising prevalence of cardiac arrhythmias, and rapid technological evolution. Historical data from 2020 through 2025 shows a consistent upward trajectory, with the market crossing the four billion dollar threshold in the base year. Projections extending through 2032 indicate that this growth momentum will not only persist but accelerate, supported by a compound annual growth rate that underscores the sector's resilience and strategic importance. This trajectory is not merely a function of volume; it reflects a fundamental shift in how electrophysiology procedures are conceptualized, executed, and reimbursed.
At the heart of this expansion lies a market structure that remains moderately concentrated. The top three players command nearly half of the total revenue, while the leading five collectively account for over two-thirds. This concentration suggests that scale, established clinical relationships, and comprehensive product portfolios continue to provide significant moats. However, the remaining market share, distributed among regional players and specialized innovators, indicates ample room for disruption and niche positioning. The balance between entrenched incumbents and agile newcomers defines the current competitive tension.
Worldwide Cardiac Radiofrequency Catheter Market
Despite the favorable macro outlook, the industry faces critical inflection points that demand strategic attention. First, the rapid adoption of pulsed field ablation (PFA) technologies is reshaping procedural workflows and device requirements, creating both opportunity and obsolescence risk for legacy systems. Second, reimbursement environments are evolving in complexity, with new coding structures for remote monitoring and digital health integration changing the economic calculus for hospitals and providers. Third, regulatory scrutiny is intensifying, particularly around safety labeling and real-world performance data, forcing manufacturers to balance speed-to-market with rigorous post-market surveillance. These challenges are not isolated; they interact to shape the pace of adoption and the allocation of capital across the value chain.
Key Drivers of Market Dynamics
Technological Innovation and Breakthroughs
The most conspicuous catalyst for market growth is the transition from thermal ablation modalities to non-thermal energy sources, particularly PFA. This shift promises shorter procedure times, reduced collateral tissue damage, and improved safety profiles, which in turn drive higher procedure volumes and broader patient eligibility. Mapping and navigation systems are also undergoing simultaneous refinement, with higher resolution, integration of artificial intelligence-assisted annotation, and seamless interoperability with imaging modalities. These advancements reduce operator dependency and standardize outcomes, making EP procedures more scalable across different care settings. The convergence of ablation precision and mapping fidelity is creating platforms rather than standalone devices, increasing the strategic value of integrated solutions.
Policy and Regulatory Environment
Regulatory frameworks are adapting to the pace of innovation while placing greater emphasis on procedural safety and post-market evidence. Recent updates to instructions for use for certain PFA systems, prompted by reviews of procedural adverse events, illustrate how regulators are tightening guidance without halting progression. Simultaneously, the expansion of indications for multiple PFA platforms through FDA approvals has broadened the addressable patient population, particularly for persistent forms of atrial fibrillation. This regulatory openness is contingent on robust clinical data and clear labeling, meaning that manufacturers with mature clinical programs and real-world evidence pipelines are better positioned to capitalize on indication expansions. Reimbursement policy is also evolving; newly introduced CPT codes for remote physiological monitoring and therapeutic services are aligning financial incentives with digital EP workflows, encouraging hospitals to invest in connected care infrastructure alongside hardware.
Cardiac Rhythm Management (CRM) Devices Market
Demand-Side Shifts in Provider and Patient Behavior
Healthcare providers are increasingly prioritizing efficiency, safety, and total cost of ownership over device price alone. As EP labs face capacity constraints and staffing pressures, solutions that reduce fluoroscopy time, shorten learning curves, and enable faster turnover are gaining preference. Patients, supported by greater awareness and improved screening, are seeking earlier intervention for arrhythmias, particularly atrial fibrillation, which remains the dominant application driving device utilization. The growing emphasis on minimally invasive approaches and outpatient procedural settings is also reshaping purchasing patterns, with institutions favoring platforms that support same-day discharge pathways and remote follow-up. These behavioral shifts reinforce the demand for integrated systems that deliver consistent clinical results across varied operator skill levels.
Supply Chain and Cost Structure Evolution
The supply chain for EP devices is under pressure from multiple directions. Component specialization, sterilization requirements, and regulatory-grade quality systems create inherent complexity, while geopolitical and logistics volatility have prompted manufacturers to diversify sourcing and increase inventory buffers for critical consumables. At the same time, the rise of reprocessing programs for certain diagnostic and mapping catheters introduces a parallel cost dynamic, offering institutions a way to manage expenditure on single-use items while navigating regulatory and quality assurance requirements. Cost containment efforts by providers are not necessarily negative for manufacturers; they can stimulate innovation in durable platforms, subscription-based software enhancements, and service models that convert capital expenditure into predictable operational costs. Companies that can articulate a compelling value proposition across the total cost of care are more likely to secure formulary placement and long-term contracts.
Competitive Landscape and Leading Strategies
Strategic Positioning of Leading Companies
The competitive field is anchored by a group of diversified medical technology companies that leverage broad commercial infrastructure, established physician relationships, and multi-product portfolios. Medtronic, headquartered in Minneapolis, offers a comprehensive EP portfolio that includes mapping and ablation systems for atrial fibrillation alongside defibrillation leads and cardiac ablation solutions. Its strategy emphasizes platform breadth and integration across the patient journey. Abbott, based in Abbott Park, combines EP ablation catheters with mapping tools and PFA systems, positioning around precision, workflow efficiency, and expanding clinical indications. Boston Scientific, in Marlborough, has gained attention with its PFA platform and mapping and ablation offerings, pursuing aggressive indication expansion and clinical evidence generation. Johnson & Johnson MedTech, through its electrophysiology business in Irvine, markets widely adopted mapping systems and PFA platforms, relying on brand recognition, extensive clinical networks, and continuous software advancement. Biotronik, from Berlin, focuses on ablation catheter families and PFA systems, differentiating through specialized therapy products and regional strength in European markets.
Beyond these scale players, the landscape includes technology specialists and novel entrants that target specific workflow gaps. Stereotaxis, in Saint Louis, develops robotically-navigated magnetic ablation catheters aimed at complex procedures, emphasizing precision and operator support in challenging anatomies. CoreMap is advancing a map-guided EP mapping system for atrial fibrillation ablation, with recent regulatory milestones supporting the expansion of clinical evaluation in the United States. Innovative Health operates as an FDA-cleared reprocessor of used EP devices, including mapping and diagnostic catheters, reflecting the growing institutional interest in cost management and sustainability. Each of these players contributes to a landscape that is simultaneously consolidating around platforms and fragmenting around specialized solutions.
Differentiation and Competitive Advantage
In a market where top firms hold a substantial share, differentiation is increasingly achieved through clinical evidence, workflow integration, and service ecosystems rather than hardware specifications alone. Companies that can demonstrate reduced complication rates, shorter procedure durations, and reproducible outcomes across varied operator experience levels are winning preference in high-volume centers. Software-enabled features, such as advanced annotation, procedural planning, and remote monitoring compatibility, are becoming strategic assets that enhance stickiness and create recurring value. Regulatory agility also matters; firms that efficiently navigate indication expansions and safety labeling updates can capture emerging patient populations before competitors solidify their position. Finally, commercial execution—training programs, field support, and reimbursement assistance—often determines the pace of adoption at the institutional level, making service and education as critical as product design.
Evolution of the Market Structure
The market is moving toward a hybrid structure. On one side, consolidation pressure exists as larger platforms absorb complementary technologies, expand indications, and bundle mapping with ablation to offer turnkey solutions. On the other side, differentiation and niche innovation persist, particularly in robotics, AI-assisted mapping, and cost-control services that address specific institutional needs. New entrants with focused clinical value propositions can gain traction if they solve acute workflow or safety problems, even in a concentrated market. The presence of reprocessing options further complicates the landscape by introducing cost arbitrage that incumbent manufacturers must acknowledge in their pricing and service strategies. Over time, the boundary between device, software, and service will continue to blur, rewarding organizations that can orchestrate multi-component solutions and sustain clinical credibility.
PW Consulting
Future Trends and Strategic Opportunities
Trend One: Platform Consolidation with Workflow-Centric Design
Over the next three to five years, EP procurement is likely to favor integrated platforms that unify mapping, ablation, and data management within a coherent workflow. Hospitals will increasingly evaluate total procedural efficiency rather than isolated device performance, favoring vendors that can reduce setup complexity, standardize annotation, and support remote follow-up. This trend creates opportunities for companies that invest in interoperability, training, and service integration, while posing risk for point solutions that cannot demonstrate additive value within a broader ecosystem. Strategic winners will be those that can show measurable improvements in lab throughput and operator consistency.
Trend Two: Expanded Indications and Broader Patient Access
The ongoing expansion of indications for PFA and advanced mapping systems is set to enlarge the treatable population, including patients with persistent atrial fibrillation and complex anatomies. As clinical evidence matures and labeling broadens, centers that previously deferred intervention may adopt earlier treatment strategies, increasing procedure volumes. This trajectory benefits manufacturers with robust clinical programs and clear safety narratives, but it also raises the bar for post-market data collection and Real-World Evidence. The opportunity lies in pairing indication expansion with education and reimbursement support, enabling providers to adopt new protocols confidently. The risk is that safety concerns or labeling updates could slow adoption if communication and training are inadequate.
Trend Three: Digital Integration and Value-Based Procurement
Digital health integration is becoming a competitive differentiator, with remote physiological monitoring and digital workflows gaining reimbursement support and clinical acceptance. Procurement decisions are increasingly influenced by total cost of care considerations, including readmission reduction, remote follow-up capability, and data analytics that inform population management. This environment rewards vendors that can connect device data to care pathways and demonstrate downstream economic benefits. At the same time, it introduces dependency on cybersecurity, data governance, and software lifecycle management. Organizations that treat software and services as first-class products, rather than add-ons, will be better positioned to align with value-based purchasing trends.
Actionable Recommendations for Decision Makers
For Manufacturers and Product Leaders
Prioritize platform coherence over incremental feature additions. Ensure that mapping, ablation, and software components share a unified workflow and that training, service, and reimbursement support are built into the commercial model. Invest in real-world evidence generation and proactive safety communication to navigate regulatory updates and sustain indication expansions. Where relevant, explore complementary capabilities such as remote monitoring integration or reprocessing-compatible designs to address total cost of care concerns without compromising clinical standards.
For Investors and Strategic Partners
Evaluate opportunities based on clinical differentiation, regulatory readiness, and the ability to integrate into hospital workflows rather than on technology novelty alone. Favor assets with clear paths to indication expansion, strong field support networks, and defensible data assets. Pay attention to the reprocessing segment and digital monitoring services as adjacent areas that can influence device economics and adoption patterns. Diversification across platform plays and focused workflow solutions can balance scale potential with niche growth.
For Procurement and Clinical Operations Leaders
Structure evaluation criteria around total procedural efficiency, safety consistency, and long-term service support, not solely on unit pricing. Demand evidence of workflow reduction, learning curve mitigation, and compatibility with remote monitoring where applicable. Negotiate for training, data integration, and reimbursement assistance as part of the purchasing package. Consider hybrid sourcing strategies that balance platform reliability with cost-control mechanisms, while ensuring that quality and regulatory compliance remain non-negotiable.
The electrophysiology device market is at a intersection of technological momentum, regulatory evolution, and changing economic incentives. For leaders navigating this environment, timely and granular intelligence is essential to distinguish durable trends from transient noise. Detailed segmentation data, competitive drills, and tailored scenario analysis can sharpen strategic choices and reduce execution risk. For those seeking a deeper, more customized view of the market—including segment-level dynamics, regional nuances, and actionable growth pathways—accessing a comprehensive research report can provide the granularity needed to move from insight to implementation.
For detailed analysis of this topic, please visit the official page: Electrophysiology (EP) Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com