

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Bench-Top Sterilizer Market 2026: Beyond the 4.5% CAGR Story

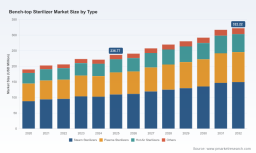
The Bench-top Sterilizer Market at a Crossroads: Strategic Trends and Commercial Opportunities
The bench-top sterilizer market has settled into a phase of steady, predictable growth that masks significant underlying shifts. Over the 2020–2025 period, the sector expanded from a modest base to a revenue run rate approaching $237 million (USD), driven by incremental adoption across healthcare, dental, and laboratory environments. Forward projections through 2032 point to a compound annual growth rate of roughly 4.5%, with the market expected to surpass $320 million by the end of the decade. These figures describe continuity, but they also reveal a market that is being quietly reshaped by regulatory clarity, technology modularization, and structural changes in how small-to-mid-sized care and research facilities manage infection control and workflow efficiency.
For executives and investors, the headline growth rate is less important than what is driving it and where friction points are emerging. The bench-top sterilizer segment is no longer a commodity-adjacent category defined by basic steam cycles and price competition. It is becoming a differentiated equipment niche where software upgradeability, water and utility integration, compliance rigor, and space-constrained design are separating capable suppliers from the rest. At the same time, reimbursement structures and procurement behaviors are placing new emphasis on total cost of ownership and demonstrable compliance, which means that competitive advantage will increasingly come from ecosystem thinking rather than instrument-level specifications alone.
Market Snapshot and the Shape of Growth
The market's trajectory from 2020 through 2025 reflects a recovery and stabilization pattern after the volatility introduced by pandemic-era procurement. Revenue climbed through 2023, experienced a modest contraction in 2024, and then resumed growth in 2025 as facilities normalized capital equipment refresh cycles. This sequence matters because it indicates that demand is not purely cyclical; it is being reinforced by longer-term factors such as the expansion of outpatient procedures, the proliferation of dental service organizations, and the ongoing modernization of laboratory infrastructure in both academic and commercial settings.
Concentration in the market remains moderate. The top three players collectively hold around 28% of revenue, and the top five account for approximately 32.5%. This level of fragmentation suggests that no single supplier has achieved dominance through scale alone. Instead, the market rewards specialization by end-use environment, regulatory readiness, and regional service capabilities. For new entrants and incumbents alike, this is a critical structural insight: broad portfolios do not automatically win, but targeted positioning against specific user profiles—dental clinics, small hospital outpatient units, research labs, and decentralized care sites—can build defensible niches.
The growth outlook through 2032 implies that the market will add meaningful volume without experiencing a step-change explosion. That kind of trajectory is attractive for operators that can manage yield, service economics, and regulatory compliance efficiently, but it also raises the bar for differentiation. When growth is moderate, margin protection and customer retention become the primary value-creation mechanisms.
Core Challenges and Inflection Points
Three interconnected challenges are defining the current inflection point for bench-top sterilizers. First, compliance expectations are becoming more granular and more auditable. Users in medical and dental environments are operating under standards that require not just functional sterilization performance but documented process reliability, cycle validation, and equipment upgrade paths that maintain classification integrity. This shifts purchasing criteria from initial purchase price toward lifecycle compliance assurance, which can disadvantage suppliers whose products are difficult to upgrade or whose documentation and service models are less rigorous.
Second, space and utility constraints are intensifying. Many dental offices, outpatient clinics, and research laboratories operate in facilities where floor space, plumbing, and power capacity are limited. Bench-top devices are inherently appealing in these settings, but they also create hidden operational dependencies. Water quality, drainage, and ambient conditions can affect sterilization reliability and service frequency. Suppliers that ignore the auxiliary infrastructure required to run bench-top sterilizers effectively risk higher callback rates and weaker customer satisfaction, even when the sterilizer itself performs well.
Third, reimbursement and procurement dynamics are reshaping the economics of adoption. In hospital outpatient settings, payment frameworks continue to recognize device pass-through mechanisms, but the absence of sterilizer-specific add-ons means that facilities weigh these purchases against broader budget pressures and operational priorities. For dental and laboratory buyers, the decision calculus is often more fragmented and discretionary, influenced by local service availability, training burden, and perceived risk. The practical effect is that the market does not respond uniformly to macro tailwinds; it responds to whether suppliers can translate clinical and operational value into lower friction for the buyer.
Key Drivers Reshaping Demand and Competition
Technology modularization is one of the most consequential drivers in the segment. Rather than forcing buyers to choose a fixed configuration at purchase, some manufacturers are enabling software-driven upgrades that move equipment between classification levels or unlock additional cycle capabilities. This approach aligns with the way many clinics and labs actually operate: they often start with a narrower use case and expand later, or they need flexibility to handle different instrument loads without acquiring separate units. Modular upgradeability also helps mitigate the risk of obsolescence in a market where purchasing cycles can be long and budgets constrained.
Regulatory alignment is another powerful driver. Products that are designed around recognized sterilization standards and that carry appropriate clearances for reusable medical devices reduce the burden on facilities to justify compliance internally. In environments where infection control audits, accreditation visits, and risk management reviews are frequent, documented conformity is not a minor convenience; it is a procurement prerequisite. Equipment that can demonstrate adherence to applicable performance and validation expectations gains trust faster and tends to encounter fewer barriers during purchasing and inspection cycles.
PW Consulting
Demand-side behavior is shifting toward integrated workflow thinking. Dental service organizations, outpatient providers, and laboratory managers increasingly evaluate sterilization equipment not as an isolated instrument but as part of a compact clinical or research process. That perspective favors solutions that are compact without being compromised, intuitive to operate, and supported by service and training models that minimize downtime. It also increases the importance of auxiliary systems that support sterilizer performance, such as purified water delivery, because reliability at the point of use often depends on more than the sterilizer cabinet itself.
Supply chain and cost structure considerations remain relevant, particularly for suppliers operating across multiple geographies. Raw material volatility, production consistency, and the cost of maintaining regional service networks all influence margin outcomes. But in this mature-yet-evolving market, the more decisive cost lever is often operational rather than manufacturing alone. Reducing installation friction, simplifying maintenance, and lowering the total cost of ownership through reliable performance and predictable service intervals can be more impactful than marginal reductions in unit price.
Competitive Landscape and Strategic Positioning
The competitive field reflects a blend of established Western manufacturers with strong clinical and dental heritage and smaller specialized players focused on laboratory and research-grade applications. Companies such as Tuttnauer, Midmark Corporation, and MELAG Medizintechnik have built reputations around steam and hot air sterilization solutions tailored to healthcare and dental settings. Their strategic positioning tends to emphasize compliance readiness, cycle reliability, and product lines that address the everyday operational realities of clinical environments. In a market where end users value familiarity, service accessibility, and auditable performance, these strengths can translate into durable customer relationships.
On the laboratory and research side, suppliers including Consolidated Sterilizer Systems, Priorclave, D.A.I. Scientific, and Benchmark Scientific focus on compact, application-specific bench-top units that serve space-constrained and specialized workflows. Their differentiation often lies in research-grade construction, practical ergonomics, and support structures that match laboratory usage patterns. Meanwhile, manufacturers like Scitek Global illustrate the growing role of ISO 13485-aligned production and Class B vacuum bench-top designs in expanding the field's quality expectations and geographic reach. This mix suggests that the market is not converging on a single template; it is supporting multiple viable value propositions as long as each is clearly tied to a defined user environment.
Recent company-level developments highlight the directions that forward-looking suppliers are taking. One notable example is the recognition of certain bench-top autoclaves through a technology breakthrough designation, accompanied by the ability to upgrade from Class S to Class B through a software update. This combination matters because it links innovation credibility with practical flexibility, allowing facilities to preserve capital while expanding capability. It also underscores a broader shift in which software is becoming a strategic layer in sterilization equipment, not merely a control interface.
Another meaningful development is the introduction of compact wall-mounted water purification systems designed to support bench-top sterilizer operations in healthcare and life science laboratories. This Signals an important evolution in how suppliers think about the sterilizer ecosystem. When purified water delivery is engineered as a complementary system, it addresses a real operational dependency and reduces the risk of performance variability. It also opens the door to more integrated commercial models, where suppliers can offer bundled solutions that improve reliability and simplify installation for end users.
Plasma Sterilizers Market
The market is likely to continue evolving through a combination of incremental consolidation and targeted expansion. Moderate concentration leaves room for bolt-on acquisitions, especially where a larger player can add geographic coverage, service density, or a complementary product line. At the same time, new entrants can still succeed by attacking specific pain points—space limitations, water infrastructure, upgradeability, or compliance documentation—if they avoid direct confrontation with entrenched incumbents in broad, undifferentiated segments.
Looking Ahead: Three Trends Shaping the Next Three to Five Years
Software-defined flexibility will become more central to commercial positioning. As more buyers seek to future-proof limited capital budgets, the ability to reconfigure performance through updates rather than hardware replacement will be increasingly valued. This trend favors suppliers that can manage software lifecycle responsibilities, validate upgrade paths, and communicate the compliance implications clearly. It also raises the stakes for post-sale support, because software-driven capability changes must be paired with training and documentation that keep users confident and audit-ready.
Integrated utility and purification support will move from niche convenience toward a more standard expectation in many deployment scenarios. Bench-top sterilizers are attractive partly because they reduce footprint, but their performance and service reliability often depend on water quality and installation conditions. Suppliers that offer or partner for supporting water purification, simplify plumbing requirements, or design for easier integration into constrained spaces will have an advantage in environments where facilities lack dedicated infrastructure teams. The commercial implication is that equipment sales may increasingly be accompanied by accessory systems, service agreements, and installation guidance that collectively lower risk for the buyer.
Regulatory and compliance maturity will continue to reward manufacturers that treat conformity as a product attribute rather than a paperwork exercise. The more clearly equipment aligns with recognized sterilization expectations and carries appropriate clearances for intended uses, the easier it becomes for facilities to adopt it and defend the decision internally. In parallel, reimbursement and payment dynamics will keep encouraging buyers to focus on value that reduces operational friction, since device-specific reimbursement remains limited. Together, these forces will push the market toward solutions that combine credible compliance, practical usability, and lower hidden costs over the equipment lifecycle.
These trends create commercial opportunities for manufacturers that can articulate a clear end-use fit, for investors that can identify suppliers with strong service economics and defensible niches, and for procurement teams that can prioritize total cost of ownership and compliance confidence over initial price. The principal risk is complacency among suppliers that assume moderate market growth will protect them from competitive pressure. In a fragmented market with rising expectations, the winners are likely to be those that invest in differentiation where it matters most to the buyer: flexibility, reliability, and support.
Actionable Implications for Decision Makers
Manufacturers should prioritize modularity and ecosystem readiness over breadth alone. The ability to upgrade configurations through software, support compliant use across intended applications, and address auxiliary needs such as water quality can be more differentiating than expanding the number of models in a catalog. Equally important is the service model: predictable maintenance, rapid local support, and clear documentation will increasingly determine whether a purchase becomes a long-term relationship or a short-lived deployment.
Investors should evaluate not only unit sales momentum but also the quality of customer retention and the economics of downstream support. In a market growing at a moderate pace, durable value often depends on repeat service revenue, low callback rates, and the ability to cross-sell complementary systems that improve reliability. Suppliers that can demonstrate a repeatable operating model across dental, medical, and laboratory segments—without diluting their focus—may offer more resilient exposure than those relying on broad but shallow product lines.
Procurement and operations leaders should evaluate bench-top sterilizers as part of a compact workflow rather than as standalone instruments. That means validating compliance documentation, confirming the practical requirements for installation and water quality, and assessing how easily the unit can adapt if the facility's mix of instruments or sterilization needs changes over time. A lower purchase price can be outweighed by hidden costs in service frequency, training burden, or operational constraints, especially in space-limited environments.
For organizations that need to pressure-test a specific market entry, portfolio extension, or procurement decision, the full set of segmentation detail, competitive profiles, and scenario analysis can be critical. PW Consulting's complete research report on the bench-top sterilizer market provides deeper breakdowns and tailored recommendations for manufacturers, investors, and buying organizations seeking to act with greater precision.
The bench-top sterilizer market is not experiencing a dramatic disruption, but it is undergoing a meaningful re-pricing of what creates value. Compliance clarity, software-enabled flexibility, utility integration, and service reliability are becoming the anchors of competitive advantage. For leaders willing to look beyond the headline growth figures, the opportunity lies in aligning product strategy and purchasing decisions with the way end users actually operate—where space is tight, workflows are compact, and confidence in sterilization performance is non-negotiable.
Sterilization Equipment Market
For detailed analysis of this topic, please visit the official page: Bench-top Sterilizer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com