

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Electric Pressure Cooker Market: Why Asia Pacific’s Scale Drives 2.9% CAGR Growth Through 2032

Electric Pressure Cooker Market: Strategic Trends and Commercial Opportunities Through 2032
The electric pressure cooker market has transitioned from a niche kitchen accessory to a mainstream appliance category, driven by shifting consumer habits, technological maturation, and evolving regulatory expectations. From a base valuation of approximately 4.5 billion USD in 2020, the market has expanded to an estimated 5.2 billion USD by 2025, reflecting a compound annual growth rate of 2.9 percent over the historical period. Looking ahead to 2032, the sector is projected to reach 6.45 billion USD, with growth pacing itself around the mid-single-digit range. These figures signal a market that has moved past its initial adoption curve and is now entering a phase where differentiation, compliance, and operational efficiency determine competitive positioning rather than mere product availability.
For executives and investors, the numbers alone do not capture the underlying dynamics. The market is consolidating around established players while simultaneously opening doors for brands that can deliver smarter functionality, tighter safety standards, and region-specific go-to-market strategies. The following analysis unpacks the structural forces shaping the category, the competitive maneuvers defining leadership, and the strategic decisions that will separate resilient operators from those caught off guard by regulatory or demand-side shifts.
Market Snapshot and Structural Challenges
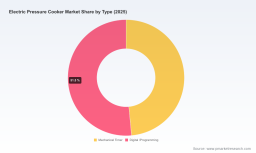
The 2026–2032 forecast window indicates a market that will continue to grow but at a measured pace. The 2.9 percent CAGR suggests steady expansion rather than explosive adoption, reflecting a category that has achieved broad baseline penetration in several mature markets while still facing headroom in others. Revenue distribution across regions, product types, and end-use segments reveals a landscape where Asia Pacific commands the largest share of activity, followed by North America and Europe, with Latin America and the Middle East and Africa representing smaller but strategically relevant pockets. The split between mechanical timer and digital/programming variants shows a near-even divide, indicating that affordability and simplicity still compete effectively against feature-rich smart appliances. Residential applications dominate commercial use by a wide margin, reinforcing the consumer-oriented nature of the category even as foodservice and institutional channels contribute a meaningful secondary demand stream.
Within this framework, three structural challenges stand out as critical inflection points for the next cycle.
Multi-Functional Cooking Food Processors Market
Safety Compliance and Recall Exposure
Product safety has emerged as a defining constraint. The category relies on pressurized cooking environments, and any failure in lid locking, pressure release, or thermal management can result in burn injuries and rapid regulatory intervention. High-profile recalls of multi-function pressure cookers and electric pressure cooker units have highlighted how quickly reputational risk can escalate when safety engineering lags behind feature proliferation. For manufacturers, this means that compliance is no longer a backend cost center but a front-line differentiator. Brands that can demonstrate rigorous validation, transparent failure-mode analysis, and responsive field action protocols will be better positioned to retain consumer trust and avoid costly inventory write-downs.
Feature Saturation and Value Perception
As digital programming, app connectivity, and multi-cooker hybrids become more common, the market risks diluting perceived value. Consumers and procurement teams increasingly evaluate whether added complexity translates into measurable convenience, energy savings, or cooking consistency. When premium features do not deliver clear usability benefits, price sensitivity rises and mid-tier mechanical alternatives regain traction. The challenge for brands is to avoid feature bloat while still offering enough differentiation to justify premium positioning. Investment in intuitive interfaces, reliable pressure control, and clear cooking presets often yields stronger returns than expanding technological specifications without user-centric design.
Regional Divergence in Adoption and Cost Structures
The market does not move uniformly across geographies. In higher-income regions, demand is shaped by convenience-driven meal preparation, brand loyalty, and a willingness to pay for smart functionality. In price-sensitive markets, volume growth depends on accessible pricing, durability, and distribution reach. Supply chain localization, component sourcing, and after-sales service expectations vary accordingly. A strategy that works in one region can underperform in another if it fails to align with local purchasing behavior, electrical standards, or competitive density. This divergence forces manufacturers and investors to think in terms of regional playbooks rather than a single global rollout.
Key Demand Drivers and Structural Shifts
The market's trajectory is being shaped by interconnected forces that touch technology, policy, consumer behavior, and supply-side economics. Understanding how these drivers reinforce one another provides a clearer view of where commercial opportunity is forming.
Technology Innovation and Smart Cooking Convergence
Technological progress in electric pressure cookers has moved beyond basic pressure maintenance toward integrated cooking logic. Digital controllers, timed presets, and adaptive heating elements are improving repeatability and reducing user error. The convergence of pressure cooking with slow cooking, sautéing, and keeping-warm functions has expanded the appliance's role in everyday meal preparation. More importantly, the push toward smarter operation is shifting competitive emphasis from hardware alone to software-defined experiences. Brands that can deliver consistent cooking outcomes, easy cleaning, and predictable energy use are gaining an edge in households where time and reliability matter more than raw specifications.
Policy, Standards, and Safety Accountability
Regulatory scrutiny is intensifying around pressure appliance safety, lid integrity, and thermal protection. Public recalls and injury reports have reinforced the expectation that manufacturers must design for fail-safe operation and maintain traceable quality controls. This environment favors companies that invest early in compliance engineering, third-party testing, and post-market monitoring. It also creates a barrier to entry for lower-cost players that cannot sustain the overhead of robust safety validation. Over time, the policy environment is likely to reward brands that treat safety as a product architecture principle rather than a reactive checklist, turning compliance into a credibility asset.
Demand-Side Behavior and Lifestyle Compression
Consumer behavior continues to favor appliances that reduce active cooking time without sacrificing meal quality. Busy household schedules, interest in healthier cooking methods, and a broader acceptance of one-pot meal preparation all support demand for electric pressure cookers. At the same time, consumers are becoming more selective about total cost of ownership, including durability, replacement part availability, and energy consumption. Commercial users, while smaller in volume, are influenced by labor efficiency, batch consistency, and equipment footprint. In both residential and commercial settings, the value proposition is increasingly tied to predictability: users want appliances that deliver the same result with minimal supervision.
Supply Chain, Manufacturing, and Cost Structure
The competitive economics of the market are influenced by component availability, manufacturing scale, and the balance between proprietary design and outsourced production. Large manufacturers with vertical integration or established OEM relationships can manage cost volatility more effectively and adjust output in response to demand fluctuations. Meanwhile, brands that rely on external suppliers must navigate pricing pressure, lead-time variability, and quality consistency. Regional manufacturing footprints also matter because they affect shipping costs, tariff exposure, and speed to market. Companies that can align production capacity with regional demand patterns while maintaining strict quality gates are better positioned to protect margins through the forecast period.
Competitive Landscape and Leadership Strategies
The market is characterized by a concentrated core of established brands alongside a long tail of regional and specialty players. Top-tier players collectively hold a significant share of revenue, with concentration levels indicating that a handful of names account for a large portion of industry activity. This structure rewards scale, brand equity, distribution reach, and the ability to manage safety and quality at volume.
Strategic Positioning Among Leading Companies
Several companies illustrate the different routes to competitive advantage in this category. Instant Brands Inc. has built strong recognition through a focused lineup of electric pressure cookers and multi-cookers, emphasizing user-friendly cooking programs and broad consumer awareness. SEB Group leverages a portfolio that includes well-known pressure cooker labels and a long heritage in kitchen appliances, using brand trust and multi-market presence to sustain relevance. Midea Group combines its own branded offerings with OEM capabilities, giving it flexibility to serve both direct consumer channels and behind-the-brand manufacturing demand. National Presto Industries, Inc. maintains a legacy-oriented approach centered on dependable electric pressure cookers, appealing to buyers who prioritize proven design and straightforward operation. Breville Group positions itself around performance-oriented appliances, targeting users who value precision cooking and higher-end build quality.
The competitive field also includes brands that have grown by emphasizing specific product experiences or channel strengths. Ninja, operating under SharkNinja, has expanded its footprint with multi-function pressure cookers that blend pressure cooking with other modes, gaining traction through aggressive product iteration and retail presence. Cosori has focused on electric pressure cookers with an emphasis on accessible design and digital features. Fissler brings a European engineering perspective through its pressure cooker lines, appealing to markets that value durability and cooking performance. Galanz Group and Joyoung Co., Ltd. reflect the importance of manufacturing scale and regional demand leadership, with product lines and OEM activity that support both consumer markets and broader appliance ecosystems.
PW Consulting Health Care Research Center
Differentiation Through Safety, Experience, and Channel Control
Across these players, the most durable differentiators are converging around three themes. First, safety engineering and transparent quality processes are becoming a license to operate in high-visibility markets. Second, user experience matters as much as hardware, with interface clarity, preset reliability, and ease of cleaning influencing repeat purchase and recommendation. Third, channel strategy remains critical because retail partnerships, e-commerce visibility, and service networks shape both reach and brand perception. Companies that align product design with safety expectations, then reinforce that alignment through controlled distribution and responsive support, are creating a more resilient competitive position.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The landscape is likely to evolve through a combination of consolidation among mid-tier players and continued fragmentation in regional niches. Larger brands may pursue acquisitions, channel expansion, or product line extensions to strengthen scale and geographic coverage. At the same time, smaller entrants can find room in specialized segments, such as compact appliances, design-forward products, or region-specific pricing tiers. However, the safety and compliance environment raises the cost of entry, meaning new players must prove reliability quickly to avoid regulatory setbacks and reputational damage. The result is a market where scale and discipline increasingly matter, but where targeted innovation can still open defensible positions if supported by strong quality controls.
Forward Outlook: Trends and Commercial Implications
Looking toward the late 2020s and into 2032, three trends are likely to shape the market's next phase and create distinct commercial implications.
Safety-First Product Architecture Becomes Table Stakes
The pattern of recalls and injury reports is pushing the category toward a safety-first design culture. Expect greater emphasis on lid-lock verification, pressure-release reliability, thermal safeguards, and clearer user feedback during operation. For manufacturers, this trend creates an opportunity to build brand credibility by making safety features visible and understandable rather than hidden inside the product. For investors, it signals that margin models dependent on cutting corners in validation or materials will face growing risk. The commercial opportunity lies in brands that can communicate dependable performance without overpromising, and that can maintain rigorous post-sale monitoring to manage issues before they scale.
Smart Functionality With Practical Value Wins Over Feature Proliferation
Digital and programming segments are expected to continue gaining ground, but the winning products will be those that connect technology to everyday usefulness. Appliances that offer reliable presets, consistent results, and easy operation will outperform those that add connectivity without solving real user pain points. This trend favors companies that invest in software usability, recipe-driven guidance, and maintenance reminders that extend product life. It also creates an opening for brands to differentiate through ecosystem integration, such as coordinated cooking workflows or compatibility with broader kitchen routines, provided those features genuinely reduce effort rather than complicate it.
Regional Playbooks Will Determine Growth Quality
As the market matures, growth quality will depend less on blanket global expansion and more on region-specific execution. In higher-income markets, premiumization and smart features may drive mix improvement. In price-sensitive markets, volume will depend on accessible pricing, durable construction, and distribution density. In commercial segments, demand will hinge on labor savings, throughput consistency, and service reliability. Companies that tailor product specifications, pricing, and after-sales support to local expectations will be better positioned to convert market growth into sustainable share gains. The risk is that brands relying on a single product strategy across all regions will face margin compression or missed adoption windows.
Risk and Uncertainty to Monitor
Several uncertainties could alter the pace or shape of growth. Regulatory actions may become more stringent if safety incidents continue to draw attention, raising compliance costs and slowing product launches. Supply chain disruptions or component shortages could pressure pricing and availability, especially for brands with limited manufacturing flexibility. Consumer sentiment may shift if economic pressures reduce discretionary spending on premium appliances, making value-oriented alternatives more attractive. Finally, the pace of smart-feature adoption could disappoint if users perceive limited benefit relative to cost, prompting a reversion toward simpler mechanical options in certain segments. Monitoring these signals will be essential for anticipating shifts in demand mix and competitive intensity.
Actionable Priorities for Decision Makers
The commercial path forward depends on how companies align product strategy, compliance culture, and regional execution. The following priorities can help translate market dynamics into practical decisions.
Stainless Steel Cookware Market
For Manufacturers and Brand Owners
- Treat safety engineering as a core design parameter, not a post-development review. Build validation, lid-lock reliability, and pressure management into product architecture early, and document failure-mode controls in a way that supports both compliance and consumer confidence.
- Balance feature sets with usability. Prioritize digital functions that improve repeatability, reduce supervision, and simplify cleanup. Avoid adding complexity that does not translate into a tangible user benefit, because value perception will increasingly determine willingness to pay.
- Align production and distribution with regional demand profiles. Consider where scale, OEM relationships, local assembly, or channel partnerships provide the strongest advantage, and avoid assuming that a single product formula will perform uniformly across markets.
For Investors and Strategic Planners
- Focus on companies with credible safety practices, disciplined cost structures, and clear brand positioning. In a market where recalls can rapidly reshape reputation, operational discipline is a meaningful indicator of resilience.
- Evaluate growth by segment and region rather than relying on aggregate market size alone. Revenue opportunities differ across residential and commercial use, across mechanical and digital types, and across geographies with very different purchasing behavior.
- Watch for consolidation signals among mid-tier players and for new entrants that can demonstrate both innovation and compliance capability. M&A, channel partnerships, and OEM relationships will likely shape competitive positioning as the market matures.
For Procurement, Retail, and Commercial Buyers
- Assess suppliers on total reliability rather than sticker price alone. Lid integrity, pressure control consistency, service support, and replacement part availability can affect downstream risk and user satisfaction more than initial purchase cost.
- Include safety documentation, recall history, and post-market response in vendor evaluation. A supplier's willingness to maintain transparent quality processes is a practical indicator of long-term partnership value.
- Match product selection to end-user expectations. Residential buyers may prioritize ease of use and preset reliability, while commercial operators may value throughput, durability, and service responsiveness. Aligning assortment with actual usage improves adoption and reduces returns.
The electric pressure cooker market is entering a phase where disciplined execution matters more than raw expansion. Growth will continue through 2032, but the companies that convert that growth into durable advantage will be those that treat safety, usability, and regional fit as strategic imperatives. Detailed segmentation data, competitive benchmarking, and scenario-based planning can help translate these broader trends into specific decisions for product roadmap, market entry, and investment allocation. For decision makers seeking a deeper dive into segment-level dynamics and tailored guidance, the full research report provides the more granular view needed to move from market understanding to action.
For detailed analysis of this topic, please visit the official page: Electric Pressure Cooker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com