

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Stem Cell Therapy Market: How 8.4% CAGR and Regional Shifts Redefine Growth Through 2032

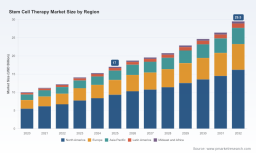
Stem Cell Therapy Market: Strategic Trends and Commercial Opportunities in a High-Growth Landscape (2025–2032)
The global stem cell therapy market has transitioned from a specialized laboratory pursuit to a commercially significant sector within the broader biopharmaceutical landscape. Valued at approximately 10.0 billion USD in 2020, the market expanded to 17.0 billion USD by 2025, demonstrating a compound annual growth rate of 8.4 percent as it approaches the 2026–2032 forecast period. This trajectory reflects more than incremental adoption; it signals a structural shift in how regenerative interventions are developed, manufactured, and positioned within healthcare delivery systems. While hematopoietic applications continue to anchor established clinical use, the commercial engine is increasingly powered by non-hematopoietic indications targeting musculoskeletal repair, wound management, cardiovascular recovery, and neurological conditions. The diffusion of these therapies depends on execution across three interconnected domains: technological reliability, regulatory predictability, and commercial viability. Organizations that understand how these domains converge will be best positioned to navigate the market’s next phase of scaling and consolidation.
Market Structure and Core Challenges
Revenue Trajectory and Concentration Dynamics
The market’s expansion from 2020 through 2025 followed a compounding pattern, reaching 17.0 billion USD before advancing toward 18.74 billion USD in 2026 and continuing upward through the remainder of the decade. This growth is not evenly distributed across the competitive field. The top three participants collectively represent only 14.6 percent of total revenue, while the top five account for 26.2 percent. Such fragmented concentration reflects an industry still in its scaling phase rather than a mature, consolidated marketplace. It also underscores the diversity of development models, manufacturing approaches, and therapeutic targets currently competing for clinical and commercial traction. The absence of dominant players creates both operational complexity and strategic openness, allowing companies with differentiated capabilities to carve out defensible positions without immediately confronting entrenched monopolies.
Manufacturing Complexity and Quality Consistency
One of the most persistent structural challenges in stem cell therapy commercialization is manufacturing reliability at clinical and commercial scale. Cell-based products are inherently live biologics, meaning batch-to-batch variability, donor sourcing consistency, and process reproducibility directly determine safety profiles and therapeutic outcomes. Meeting compendial standards such as USP or British Pharmacopoeia requirements for raw materials and reagents adds a layer of operational discipline that many early-stage programs underestimate. Inconsistent supply inputs or inadequately controlled differentiation processes can derail clinical timelines, complicate regulatory submissions, and weaken investor confidence. For commercial leaders, this means that manufacturing readiness is not a back-office function; it is a strategic asset that determines whether a promising clinical candidate can be transformed into a repeatable, scalable product.
Stem Cells Market
Reimbursement Ambiguity and Patient Affordability
A second major challenge lies in the disconnect between clinical ambition and reimbursement reality. Many non-hematopoietic stem cell applications operate outside established FDA approval pathways, leaving patients and providers to navigate out-of-pocket payment structures. In orthopedic and related regenerative settings, treatment costs frequently range between 5,000 and 50,000 USD per intervention, a range that limits broad access and complicates long-term adoption curves. This reimbursement gap creates a commercial tension: strong patient and clinician demand can coexist with fragmented payment models that slow institutional procurement and hinder predictable revenue forecasting. Companies that build clear health economic narratives, target indications with stronger payer alignment, or structure engagement models around demonstrable cost offsets will have a meaningful advantage as payers and providers demand greater evidence of value.
Regulatory Navigation Across Accelerated and Established Pathways
The third challenge is regulatory predictability. While recent policy signals have created more flexibility for early-stage development, the pathway from investigational studies to commercial approval remains multi-layered and indication-specific. Regulators are increasingly attentive to chemistry, manufacturing, and controls (CMC) rigor, even as they explore expedited review mechanisms for regenerative therapies with high unmet need. This duality requires developers to balance speed with documentation quality. Over-indexing on accelerated timelines without sufficient CMC preparation can trigger delays later, while excessive caution can cede first-mover positioning to competitors. The market’s most successful participants are those that treat regulatory strategy as a continuously evolving discipline, not a static filing exercise.
PW Consulting Health Care Research Center
Key Drivers of Market Evolution
Technical Innovation and Cell Engineering Maturation
Technological progress remains the strongest catalyst for market expansion. Advances in induced pluripotent stem cell (iPSC) platforms, genome engineering, and off-the-shelf cell design are reshaping development economics and therapeutic reach. Companies are increasingly moving beyond autologous, patient-specific models toward engineered allogeneic solutions that can be manufactured in advance, scaled more efficiently, and deployed with greater consistency. These platforms reduce dependency on individualized cell collection and processing, while enabling more standardized quality control frameworks. At the same time, improved seed line characterization, master cell bank strategies, and GMP-grade manufacturing services are strengthening the operational backbone needed to support clinical translation. Collectively, these innovations are lowering the technical barrier to repeatable production and widening the scope of indications that can be pursued with credible development plans.
Regulatory Evolution and Expedited Development Pathways
Policy and regulatory dynamics are acting as a powerful accelerant for select programs. Regulatory agencies have signaled increased flexibility for cell and gene therapy development, including more permissive quality release criteria during early investigational stages and draft guidance on expedited review pathways for regenerative medicine applications. Designations such as the regenerative medicine advanced therapy (RMAT) pathway provide eligible programs with earlier regulatory engagement, more structured feedback, and potentially faster development cycles. Recent regulatory actions, including approvals and designations in both hematologic and autoimmune settings, illustrate how targeted indications can benefit from alignment between clinical differentiation and regulatory readiness. For commercial teams, this environment rewards early regulatory planning, proactive agency communication, and indication selection that matches clinical promise with recognized expedited pathways.
Demand-Side Shifts Toward Unmet Chronic and Degenerative Conditions
Demand dynamics are being reshaped by the prevalence of chronic degenerative and inflammatory conditions that remain inadequately served by conventional treatments. Neurological disorders, cardiovascular repair needs, autoimmune diseases, and complex musculoskeletal injuries represent areas where patients and clinicians are actively seeking interventions that can modify disease progression or restore function rather than merely manage symptoms. This demand is not abstract; it translates into stronger clinical trial enrollment interest, growing institutional curiosity, and increased willingness among specialized providers to evaluate regenerative options where evidence is accumulating. At the same time, patient expectations are rising around treatment transparency, safety documentation, and real-world outcomes. Organizations that invest in robust clinical data generation, clear communication of indications and limitations, and post-market evidence collection will be better positioned to meet both clinical and market expectations.
Supply Chain Standardization and Cost Structure Evolution
The supply chain is undergoing a quiet but commercially significant transformation. As development programs mature, the sourcing of GMP-grade raw materials, reagents, media, and manufacturing support is becoming more standardized and more scrutinized. Consistency in raw inputs directly affects differentiation quality, expansion efficiency, and final product safety. This standardization is also changing cost structures. Early-stage programs often experience highly variable manufacturing economics, but the growth of specialized CDMO capabilities, GMP-grade seed lines, and reusable process infrastructure is helping companies reduce duplication and improve cost predictability over time. In parallel, regulatory emphasis on documentation and quality control is pushing firms to treat supply chain integrity as part of the product narrative, not merely a procurement concern. Companies that secure dependable GMP-grade inputs and integrate them into controlled, auditable processes are building a durable advantage in both clinical credibility and commercial scalability.
Competitive Landscape and Leading Strategies
Differentiated Strategic Profiles Across the Market
The competitive field is defined less by scale dominance and more by specialized strategic positioning. Several companies illustrate how differentiated approaches are shaping commercial trajectories. Some developers are concentrating on genome-engineered iPSC-derived platforms for allogeneic applications, building capabilities that combine cell engineering precision with scalable off-the-shelf potential. Others are advancing autologous mesenchymal stem cell therapies for neurodegenerative conditions, focusing on disease areas where unmet need remains high and clinical differentiation can be compelling. A further group is pursuing iPSC-derived immunotherapies, leveraging fast-moving regulatory designations and pilot programs to strengthen development readiness for autoimmune indications.
Beyond therapeutics developers, the ecosystem includes manufacturers and service providers that support GMP-grade product readiness. Some organizations supply clinical-grade stem cell products for regenerative applications, while others provide GMP-grade iPSC seed lines, master cell banks, and manufacturing services that reduce the operational burden for clinical programs. A parallel set of suppliers delivers GMP reagents, media, and instruments for cell expansion and differentiation, reinforcing the infrastructure layer on which therapeutics developers depend. These enabling players may not always capture headline attention, but they contribute materially to process reliability, quality control, and the overall pace at which clinical candidates can advance.
Recent Developments as Strategic Indicators
Several recent developments highlight how strategic positioning is evolving in practice. One manufacturer submitted a Type II Drug Master File to the FDA for US-generated clinical iPSC seed clones, encompassing GMP-compliant manufacturing, donor screening, and quality controls. This move underscores a broader shift toward formalized, auditable manufacturing documentation that can support downstream regulatory filings and commercial confidence. In another example, a developer received FDA RMAT designation and selection for a CMC development and readiness pilot program for an iPSC-derived CAR T-cell therapy in systemic lupus erythematosus, reinforcing how regulatory designations and early-stage CMC support can accelerate development momentum in high-interest autoimmune settings. At the same time, a strategic partnership between a genome-engineering-focused developer and a bioservices provider aimed to create a more seamless development path for iPSC-derived therapies, combining engineering capabilities with CDMO manufacturing services. These examples point to a market in which technical differentiation, regulatory readiness, and manufacturing partnerships are increasingly interdependent.
Market Evolution: Integration, Specialization, and New Entry Points
The competitive landscape is likely to evolve along several overlapping directions. One is consolidation among enabling infrastructure players, as manufacturers, reagent suppliers, and service providers seek to reduce fragmentation and offer end-to-end support for cell therapy development. Another is specialization among therapeutics developers, who may increasingly gravitate toward indication-specific platforms, manufacturing models, or engineering capabilities that are difficult to replicate quickly. A third is the continued arrival of new entrants drawn by strong growth potential and the market’s still-fragmented structure. This mix creates a dynamic environment where partnerships, platform licensing, and selective capacity expansion can be as important as proprietary pipeline advancement. Companies that treat external collaboration as a strategic lever rather than a transactional necessity will have greater flexibility to scale without overcommitting capital to every step of the value chain.
Future Trends and Commercial Implications (2026–2030)
Scaling of Off-the-Shelf and Engineered Allogeneic Platforms
Over the next three to five years, off-the-shelf and engineered allogeneic approaches are expected to gain commercial prominence as manufacturing discipline improves and early clinical signals accumulate. The appeal is straightforward: allogeneic platforms can reduce dependence on patient-specific logistics, support more predictable production planning, and enable broader distribution footprints if quality and safety benchmarks are met. The commercial opportunity lies in indication selection, process standardization, and capacity planning. Programs that align platform design with indications where repeat dosing, faster access, and scalable supply offer clear value will be better positioned to convert technical progress into revenue. The principal risk is that variability in cell behavior, immune interaction, or long-term safety could slow adoption if differentiated claims are not supported by rigorous data and transparent quality documentation.
Animal Stem Cell Therapy Market
Closer Alignment Between Regulatory Pathways and Commercial Reimbursement Strategies
A second trend is the growing intersection of regulatory progress and reimbursement planning. As more programs advance through expedited pathways and generate clinical evidence, the question of payment models will become increasingly central to commercial success. The most resilient strategies will anticipate payer expectations early, structure evidence generation to address health economic questions, and identify indications where clinical differentiation can be paired with credible cost-offset or value-based arguments. This alignment will matter especially in non-hematopoietic applications, where payment fragmentation remains a constraint. Companies that treat reimbursement as a post-approval concern rather than a parallel workstream may find themselves commercially vulnerable even after successful regulatory milestones. The risk is that clinical success does not automatically translate into market access unless payment strategy is built into development planning from the outset.
Growing Importance of GMP-Grade Infrastructure and Supply Chain Reliability
A third trend is the rising strategic value of GMP-grade infrastructure. As more programs move from early investigation toward commercialization, the ability to source consistent raw materials, maintain controlled manufacturing environments, and demonstrate batch traceability will become a key differentiator. The commercial implication is that supply chain reliability will function as a competitive moat for companies that invest in it early. Organizations that secure dependable GMP-grade inputs, formalize quality documentation, and integrate manufacturing readiness into development timelines will reduce exposure to costly delays and strengthen their credibility with regulators, partners, and investors. The uncertainty here lies in how quickly standardization can scale across a diverse supplier base and whether regulatory expectations continue to tighten around documentation and quality release criteria as programs advance.
Strategic Recommendations for Decision-Makers
For Manufacturers and Developers
Prioritize manufacturing readiness and regulatory documentation as core strategic assets rather than supporting functions. Build development plans that integrate CMC discipline, GMP-grade sourcing, and quality control from early stages so that later filings and scale-up efforts are not constrained by preventable gaps. Consider partnerships or service agreements that allow you to concentrate internal capabilities on differentiation, clinical strategy, and indication selection while leveraging external infrastructure for specialized manufacturing or supply. Where possible, align platform choices with indications that offer both clinical relevance and clearer pathways to market access.
For Investors
Evaluate not only therapeutic promise but also the operational and regulatory readiness behind each program. The most compelling opportunities are often those where technical differentiation is paired with credible manufacturing strategy, early regulatory engagement, and a plausible path to reimbursement alignment. Pay attention to enabling players as well as therapeutics developers; companies that provide GMP-grade seed lines, manufacturing services, reagents, and process infrastructure may offer exposure to market growth with different risk profiles. Assess whether a program’s indication strategy matches the regulatory and commercial environment it will actually face, rather than relying solely on scientific momentum.
For Procurement and Business Development Leaders
Strengthen supply chain diligence by treating GMP-grade consistency, documentation quality, and batch traceability as procurement criteria, not just cost factors. Seek partners whose manufacturing and quality systems can support predictable scale-up and reduce the operational risk of late-stage development transitions. Where applicable, explore flexible engagement models that allow capacity or service access without excessive long-term capital exposure, particularly in a market where program outcomes and regulatory timing can shift rapidly. Building a vetted network of manufacturing and supply partners can improve resilience and speed when programs move from clinical investigation toward commercial readiness.
Accessing Deeper Market Intelligence
The strategic picture outlined here reflects broad market structure, competitive dynamics, and directional trends, but it only captures part of the decision-making environment. Segment-level sizing, regional performance, detailed application splits, and deeper company-level data can reveal more precise opportunity pockets and risk exposure across specific indications and geographies. Organizations that need granular breakdowns, scenario analysis, or tailored guidance for a particular therapeutic area or operational function will benefit from fuller market research that maps these dimensions in greater detail. The broader stem cell therapy market is expanding with credible momentum, but its most valuable commercial positions will be earned by those who pair that awareness with precise intelligence and disciplined execution.
For detailed analysis of this topic, please visit the official page: Stem Cell Therapy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com