

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Ground Support Equipment Market Set to Reach $11.4B by 2032: Key Dynamics Explained

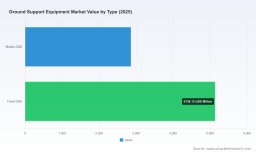
The Ground Support Equipment Market: Strategic Trends and Commercial Opportunities Through 2032
The Ground Support Equipment (GSE) market is entering a defining phase shaped by electrification, regulatory tightening, and operational modernization across the global aviation ecosystem. Valued at approximately USD 8,000 million in the base year 2025, the market has grown from roughly USD 5,020 million in 2020, reflecting a compound annual growth rate of 5.22 percent through the forecast period extending to 2032. By the end of the forecast horizon, revenue is projected to approach USD 11.4 billion, driven by fleet turnover, sustainability mandates, and expanding ground handling complexity. The market is moderately fragmented, with the top three players holding roughly 34 percent of revenue and the top five capturing about 37 percent, leaving meaningful room for specialized suppliers, regional champions, and service-oriented business models.
PW Consulting Automotive & Machinery Research Center
Market Size and Structural Trajectory
Recent years have delivered above-trend expansion, with the market climbing from USD 5,423.1 million in 2021 to USD 6,300.2 million in 2022, then USD 6,738.89 million in 2023 and USD 7,305.91 million in 2024. This acceleration reflects a combination of post-pandemic traffic recovery, replacement cycles for aging equipment, and early-stage electrification investments. The forecast points to continued momentum, with revenues expected to reach USD 8,230.72 million in 2026, USD 8,883.86 million in 2027, USD 9,538.1 million in 2028, USD 10,063.18 million in 2029, USD 10,523.26 million in 2030, USD 11,155.46 million in 2031, and USD 11,413.0 million in 2032. The trajectory suggests a market that is not merely recovering but reconfiguring around energy efficiency, digital integration, and stricter safety and maintenance regimes.
Key Challenges and Inflection Points
Despite the positive outlook, three cross-cutting challenges are shaping how companies compete and where value will accrue.
- Energy infrastructure constraints are becoming a binding constraint for large-scale electrification. As fleets transition to electric GSE, peak power demand at major hubs can approach 20 megawatts, with annual consumption nearing 51,000 MWh. Without behind-the-meter battery storage, on-site solar, or smart charging orchestration, airport operators face load management friction, demand charges, and schedule risk that can slow adoption.
- Regulatory and safety standards are tightening faster than legacy maintenance and training programs can adapt. New guidance for ground handling organizations and GSE management systems, along with evolving design and operational standards, is increasing compliance costs while also compressing the window for ad-hoc maintenance practices. Operators are being forced to modernize training, documentation, and inspection routines in parallel with equipment upgrades.
- Total cost of ownership calculations are being rewritten. The shift from fuel-intensive mobile equipment to electrified alternatives is changing the economics of acquisition, charging, maintenance, and downtime. Early deployments show double-digit fuel cost savings and material emissions reductions, but realizing those benefits depends on utilization patterns, duty cycles, charging strategy, and component durability under ramp conditions.
Key Drivers Shaping the Market
Technology Innovation and Electrification
Electrification is the most visible technology shift, and it is moving from pilot programs to fleet-level commitments. Manufacturers are launching high-voltage tractors, electrified deicing units, and electrified pre-conditioned air solutions that align with airport sustainability goals and operational reliability requirements. Recent product milestones include the delivery of the 7,000th LEKTRO towbarless aircraft tractor to Atlantic Aviation, the introduction of a class-leading electric tow tractor for global airport operators, and the showcase of an electrified GSE lineup featuring automotive-style charging compatibility and extended runtime at a major industry exhibition. These developments signal a market that is converging around practical electrification rather than waiting for a single breakthrough. The strategic implication is clear: competitiveness increasingly depends on energy integration, duty-cycle fit, and service support, not just mechanical performance.
Policy, Regulation, and Safety Standards
Policy and standards are reshaping the operating envelope. An IATA program integrating enhanced GSE into ISAGO operations is targeting meaningful reductions in ground damage costs by accelerating the transition of belt-loaders, cargo-loaders, passenger stairs, and boarding bridges. In parallel, EASA has issued decision guidance establishing acceptable means of compliance for management systems, training, maintenance programs, and safety risk management for ground handling organizations and GSE. SAE’s Aircraft Ground Support Equipment Committee continues to maintain design, manufacturing, and operational safety standards that influence procurement specifications and liability exposure. Together, these instruments raise the bar for documentation, inspection discipline, and component traceability, favoring suppliers and operators that can demonstrate consistent compliance and predictable maintenance outcomes.
Ground Handling Services Market
Demand-Side Shifts in Airport Operations
Airports and ground handlers are under simultaneous pressure to improve turnaround times, reduce emissions, and manage labor and maintenance costs. Passenger handling and aircraft handling remain central to GSE demand, while cargo handling continues to grow as e-commerce and belly cargo volumes reshape ramp activity. Electric coaches, ramp cars, and electrified service units are increasingly specified in new procurement cycles, especially where sustainability commitments intersect with operational reliability targets. A recent partnership to deploy next-generation electric GSE, including electric coaches and ramp cars in India, illustrates how regional air traffic expansion and green operational goals can align to accelerate fleet renewal. The broader message is that demand is no longer driven only by replacement cycles; it is being pulled by specifications that couple efficiency, emissions, and uptime.
Supply Chain, Cost Structure, and Energy Economics
Energy cost and supply chain dynamics are influencing procurement more than in past cycles. Behind-the-meter storage and solar systems can reduce peak loads by 20–30 percent and lower overall energy costs by 5–10 percent at large facilities, making the economics of electrification more attractive when planned holistically rather than as a unit-by-unit swap. Real-world results are already visible: a major U.S. airport achieved roughly $2.8 million in annual fuel cost savings and approximately 10,000 metric tons of GHG emissions reduction through electric GSE deployment. At the same time, demand for flexible pre-conditioned air solutions is increasing as EU airport sustainability goals push operators toward lower emissions and improved energy efficiency. These dynamics are pushing manufacturers and operators alike to think in terms of system-level energy strategy, not isolated equipment purchases.
Competitive Landscape and Leading Strategies
Core Positioning Among Leading Providers
The competitive landscape blends global specialists, regional manufacturers, and service-focused suppliers. Several companies are building advantage through electrification, while others differentiate through product breadth, parts availability, and support ecosystems.
- Textron GSE continues to expand its electrified portfolio, including high-voltage towing systems and electrified deicing equipment, with a recent exhibition emphasizing charging compatibility and extended runtime. Its scale and product breadth position it to serve operators seeking integrated ramp solutions and standardized support across multiple GSE categories.
- Trepel Airport Equipment GmbH has reinforced its position in cargo handling and aircraft tractors with a new electric tow tractor aimed at global airport operators, broadening the electrified option set in a segment where payload and durability are critical. The move reflects a wider trend of European manufacturers aligning product strength with sustainability specifications.
- ITW GSE maintains leadership in ground power units, pre-conditioned air units, and intelligent gate systems, with a focus on energy efficiency and flexible deployment. Growing demand for flexible PCA solutions tied to airport sustainability goals underscores its relevance as airports seek to reduce emissions and manage energy use across terminal and ramp interfaces.
- Oshkosh AeroTech has reached a significant adoption milestone with the delivery of the 7,000th LEKTRO towbarless tractor, indicating strong operator acceptance of electric towbarless tractors in commercial and service environments. This kind of milestone matters because it signals durability, parts availability, and a mature support base, all of which reduce perceived adoption risk.
- Tronair Inc., Aero Specialties, Mercury GSE, Avro GSE, and TUG Technologies Corporation each contribute distinct value: Tronair serves corporate, business jet, and general aviation segments with electric tugs and towbarless tractors; Aero Specialties provides new, used, and refurbished solutions that lower entry barriers and extend asset life; Mercury GSE combines sales, rentals, leasing, and technical support; Avro GSE focuses on electrified pushback tractors, loaders, and efficiency-oriented equipment; and TUG Technologies Corporation anchors baggage tractors, pushbacks, belt loaders, and deicers within a broader GSE ecosystem.
- Harlan Global Manufacturing rounds out the landscape with rugged GSE and components for military, government, and airport ramp operations, including electric tractors and specialized towing units. Its emphasis on durability and specialized use cases illustrates the continued importance of segment-specific engineering and supply reliability.
Strategic Differentiation and Business Model Evolution
Leading players are differentiating along several axes that matter to procurement and operations teams. Electrification with practical charging integration is now a baseline expectation for many RFPs, but differentiation is increasingly determined by runtime under real duty cycles, service response times, parts commonality, and the ability to integrate with airport energy systems. Value-added models such as leasing, rental, refurbishment, and full technical support are gaining importance because they reduce upfront capital barriers and align supplier incentives with uptime. This is a structural shift: competitive advantage is moving from unit price toward lifecycle economics and operational reliability. At the same time, used and refurbished channels are becoming more sophisticated, allowing operators to balance sustainability targets with budget constraints while extending asset utilization.
Market Structure Trends
Market concentration is moderate, and the structure is evolving through a mix of consolidation, specialization, and new entry. Larger players are leveraging portfolio breadth, global service networks, and electrification roadmaps to capture share in core aircraft handling and passenger handling applications. Smaller and regional suppliers are carving out niches through cargo specialization, business aviation, military and government use cases, or highly localized support. New entrants and partnerships are also emerging where energy infrastructure, charging compatibility, and sustainability specifications create opportunities for integrated solutions rather than standalone equipment. The likely outcome over the next several years is a more layered market: broad-portfolio suppliers competing on scale and support, specialists competing on application fit and durability, and service-led models competing on risk reduction and total cost of ownership.
Future Trends and Commercial Opportunities
Trend 1: Electrification as an Energy System Challenge
Over the next three to five years, electrification will become less about individual machines and more about managing energy at the ramp and terminal level. Operators will increasingly pair electric GSE with charging management, on-site generation, and battery storage to reduce peak demand and stabilize operating costs. Commercial opportunity lies in integrated offerings that combine equipment, charging strategy, service contracts, and energy optimization. Suppliers that can demonstrate reduced peak demand, predictable uptime, and lower total cost of ownership will be best positioned in procurement processes where energy availability and cost control are explicit evaluation criteria. The risk is that electrification plans outpace infrastructure readiness, creating delays, demand charges, or operational friction if charging and load management are under-specified.
Trend 2: Compliance and Safety as Procurement Filters
Regulatory and standards-driven requirements will increasingly function as procurement filters, not just compliance checkboxes. As ground handling organizations adopt structured management systems, training programs, and maintenance regimes tied to updated guidance, suppliers will be evaluated on documentation quality, inspection support, training enablement, and component traceability. Commercial opportunity will accrue to providers that can package equipment with compliant service processes, operator training, and clear maintenance pathways. The upside is stronger customer retention and pricing power for certified, well-supported solutions. The uncertainty is the pace and consistency of implementation across regions and operator types, which can create uneven demand and varying specification requirements.
Trend 3: Service-Led Models and Asset Lifecycle Optimization
Service-led business models will continue to expand as operators seek to reduce capital exposure, improve uptime, and manage mixed fleets. Leasing, rental, refurbishment, and full technical support will be especially relevant for organizations balancing sustainability commitments with budget discipline and fleet heterogeneity. Commercial opportunity exists for suppliers and intermediaries that can offer flexible acquisition paths, dependable refurbishment standards, and rapid service response. This trend also supports more efficient asset utilization across the market, extending useful life and smoothing replacement cycles. The risk is margin compression if service pricing becomes commoditized, and the operational challenge of maintaining consistent quality across new, used, and refurbished assets.
Strategic Recommendations for Decision Makers
For manufacturers and suppliers, the priority is to align product roadmaps with real operational and energy constraints. That means designing for duty-cycle durability, charging compatibility, and serviceability, while building support ecosystems that reduce downtime risk. Differentiation should emphasize total cost of ownership, uptime, and compliance enablement, not just feature lists. Where possible, package equipment with service, training, and energy integration guidance so procurement teams can evaluate solutions as part of a broader operational system.
For investors, the most durable value creation is likely to come from electrification enablers, service-led business models, and companies with strong parts and service networks. The market’s moderate concentration leaves room for disciplined operators that can capture share through reliability, localized support, and lifecycle economics. Due diligence should focus on fleet adoption milestones, service capacity, energy integration capability, and exposure to regulatory shifts that affect maintenance and training requirements.
For airport operators and ground handlers, the practical priority is to evaluate GSE decisions as energy and compliance decisions, not isolated equipment purchases. Specification should account for peak power management, charging strategy, training and maintenance readiness, and lifecycle cost, with particular attention to mixed-fleet realities during transition periods. Suppliers that can demonstrate measurable fuel and emissions savings, predictable uptime, and compliant support processes will improve the odds of successful deployment. The most effective procurement strategies treat electrification, safety compliance, and service support as interdependent choices that shape operational outcomes over the full asset life.
For organizations that need a deeper mapping of submarkets, regional specifications, application mix, and competitor-by-competitor positioning, the complete PW Consulting research report provides the segmented data and customized analysis required to translate these trends into procurement strategy, investment theses, and product planning.
Worldwide Aircraft Ground Support Equipment (GSE) and MRO Market
For detailed analysis of this topic, please visit the official page: Ground Support Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com