

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Sodium Metabisulfite Market 2026: The Real Drivers Behind 5.9% CAGR Growth

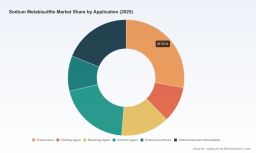
Strategic Trends and Commercial Opportunities in the Sodium Metabisulfite Market (2026-2032)
1. Market Landscape and Structural Challenges
The sodium metabisulfite market has demonstrated consistent growth over the past half-decade, evolving from a steady industrial chemical segment into a more strategically significant supply chain component. Market revenue expanded from approximately $397.5 million in 2020 to $530.34 million in 2025, reflecting an annualized growth trajectory that underscores sustained demand across multiple end-use sectors. Forecasts through the 2026-2032 period point to continued expansion, with projected revenue approaching $786 million by 2032. This growth path, driven by a compound annual growth rate of 5.9 percent, signals a market that is broadening rather than merely inflating, shaped by shifting application requirements and regional supply dynamics.
Sodium Chlorite Market
Beneath the headline figures, the market is navigating a period of structural adjustment. Three challenges stand out for operators and buyers. First, the supply chain for core raw materials is experiencing volatility that directly affects production stability and cost predictability. Sodium metabisulfite is synthesized by reacting sulfur dioxide gas with sodium carbonate or sodium hydroxide solutions, making sulfur availability and pricing a critical input variable. Second, regulatory scrutiny is intensifying across major consumption regions. Safety assessments for sulfite-based additives have undergone re-evaluation by food safety authorities, prompting manufacturers to maintain rigorous compliance documentation and adjust formulations where necessary. Third, the competitive landscape remains moderately fragmented, with a concentrated share among top-tier players alongside a broad base of regional manufacturers. This structure creates both pricing pressure and differentiation opportunities, depending on where competitors sit in the value chain.
The concentration metrics indicate that the top three participants hold roughly 22.5 percent of market revenue, while the top five account for approximately 25.8 percent. This relatively open structure means that scale advantages exist but are not insurmountable, and regional specialization can still yield meaningful competitive positioning. For decision-makers, the landscape calls for clarity on which segments offer durable margin potential versus those where commoditization is eroding returns.
2. Key Drivers Shaping Market Evolution
Technological Innovation and Process Optimization
Process innovation is reshaping how sodium metabisulfite is produced and positioned. Leading manufacturers are investing in chemical process optimization systems aimed at reducing emissions and elevating purity levels. These upgrades are not purely environmental in motivation; higher-purity outputs enable access to more demanding applications, including pharmaceutical-grade and specialty industrial uses where specification thresholds are stricter. In parallel, capacity expansions in Asia-Pacific manufacturing bases have increased output of high-purity grades, reinforcing the region's role as a supply anchor for both domestic consumption and export markets.
The practical implication is a widening gap between producers who can consistently deliver specification-grade material and those locked into commodity-level output. For buyers, this means that reliability of purity, batch consistency, and documented process controls are becoming purchase criteria rather than optional preferences. For producers, process capability is increasingly the basis for premium pricing and long-term supply agreements.
Regulatory and Compliance Dynamics
Regulatory developments are exerting a dual influence on the market. On the food and beverage side, safety reassessments of sulfite additives, including sodium metabisulfite (E223), have been conducted with updated evaluations confirming continued safe use levels under specified conditions. Such reassessments typically require manufacturers and end-users to maintain traceability, adhere to maximum permitted levels, and document compliance, which raises the administrative burden but also reinforces barriers to entry for less organized operators.
Simultaneously, the broader sulfur supply environment is being affected by energy-sector emissions patterns. Recent EPA data show that sulfur dioxide emissions from U.S. coal power plants increased by 18 percent in 2025, the second-highest increase in three decades, with exempted facilities recording nearly double that rise. While this does not directly increase sodium metabisulfite production, it reflects a destabilized sulfur economics environment that can cascade into feedstock availability and cost variability. Combined with geopolitical disruptions in the Middle East affecting sulfur supply chains and raising the risk of shortages for sulfuric acid and downstream derivatives, the regulatory and raw-material landscape is creating a more complex operating environment for producers and procurement teams alike.
Demand-Side Shifts in Applications
Demand patterns are shifting as end-use sectors adapt to changing product requirements. In food and beverage applications, sodium metabisulfite continues to serve as a preservative and antioxidant, with recent product development focused on extended shelf life for bakery and beverage categories. This aligns with broader industry goals of reducing waste, improving logistics flexibility, and maintaining product integrity across longer distribution channels. In industrial settings, demand is being reinforced by water treatment programs, where supply agreements have expanded distribution scale for municipal and industrial facilities. Chemical synthesis and intermediate applications also remain significant consumption channels, particularly where high-purity material is needed for downstream reactions and specialized processes.
These demand shifts are meaningful because they are not purely volume-driven; they are increasingly tied to performance specifications. Applications that require consistent purity, longer shelf stability, or conformance with food-grade and pharmaceutical-grade standards are creating pockets of demand that reward suppliers with targeted capabilities. For commercial leaders, the opportunity lies in aligning product portfolios with the segments where specification consistency translates into stickier customer relationships.
Supply Chain and Cost Structure Considerations
The cost structure of sodium metabisulfite production is linked closely to sulfur dioxide and alkali feedstocks, both of which are subject to energy prices, regional availability, and logistical constraints. In a market where top-tier producers account for only about a quarter of total revenue, cost discipline and supply chain resilience are differentiating factors. Manufacturers with integrated feedstock strategies or diversified sourcing arrangements are better positioned to absorb price shocks, while those heavily reliant on single-source inputs face greater exposure to volatility. The Iran-related disruption to sulfur supply chains highlights how quickly geopolitical events can translate into price pressure and availability risk for downstream chemicals.
For procurement and operations leaders, the strategic response is to treat feedstock risk as a core variable in sourcing decisions. Dual-sourcing, regional inventory buffers, and long-term supply agreements with transparent cost pass-through mechanisms can reduce exposure. For producers, the ability to communicate supply continuity and cost predictability is becoming a competitive asset in negotiations with large end-users.
3. Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of large multinational chemical companies, regional manufacturers with substantial capacity, and specialized suppliers focused on food-grade, pharmaceutical-grade, or technical-grade niches. Several firms illustrate the strategic directions that are shaping the market.
BASF SE has focused on process upgrades at its Ludwigshafen site to reduce production emissions and increase sodium metabisulfite purity levels, reinforcing its position in non-food-grade and high-purity applications for reducing and bleaching uses. This type of investment signals a strategy centered on quality differentiation and environmental performance, which increasingly matter to downstream customers with their own sustainability commitments. Aditya Birla Chemicals has expanded its manufacturing facility in Maharashtra by 30 percent to increase production capacity for high-purity sodium metabisulfite, while also strengthening its Asia-Pacific production base. The expansion supports both domestic and export markets across food, industrial, and high-purity grades, illustrating a volume-and-quality strategy that aims to capture scale while maintaining specification capability.
Ineos Calabrian Corporation has moved into new supply agreements with water treatment plants in North America, significantly expanding distribution scale in a segment where reliability and service coverage are key purchase drivers. Esseco Group S.r.l. has developed food-grade sodium metabisulfite with extended shelf life for bakery and beverage sectors, demonstrating product-level innovation that addresses end-user needs around preservation and logistics. Grillo-Werke Aktiengesellschaft remains a leading producer of high-purity material for chemical synthesis and industrial applications, underpinning a strategy anchored in specialty-grade performance.
PW Consulting
On the regional side, several Chinese and Indian manufacturers have scaled capacity to 200,000 tons annually and focused on high-purity outputs for food and industrial uses. These producers combine cost competitiveness with growing capability in specification-grade material, and many serve both local and export markets. Indian suppliers in particular have built long-standing export businesses across food preservation and industrial applications, with some emphasizing food-grade E223 material for bulk supply in food, beverage, and industrial sectors. U.S.-based suppliers and distributors continue to play an important role in providing granular, FCC, NF, and EP grades for laboratory, pharmaceutical, food, and specialty applications, often differentiating through service, documentation, and market-specific formulations.
The market is evolving along multiple axes. Consolidation is not dominant at the top tier, but there is a clear divergence between producers investing in purity, compliance, and application-specific development and those competing primarily on price. New entrants and expanding regional players are pressuring commoditized segments, while established multinationals are defending and extending positions in higher-value applications. For buyers, this means the supplier base is increasingly stratified, and the right sourcing choice depends on the performance requirements of the end application. For producers, the strategic choice is whether to compete in volume-driven segments with thin margins or to invest in capabilities that support premium positioning.
4. Future Outlook and Commercial Implications (2026-2032)
Looking ahead, three trends are likely to shape the market over the next three to five years.
First, purity and specification capability will become more decisive in customer selection. As food safety reassessments, pharmaceutical requirements, and industrial performance standards continue to tighten, demand for high-purity, well-documented sodium metabisulfite is expected to grow faster than demand for generic grades. Suppliers that can demonstrate consistent quality, robust batch records, and application-relevant certifications will capture a disproportionate share of value.
Second, regional supply chains will continue to reconfigure. Asia-Pacific capacity expansion, combined with localized production in India and China, is increasing the availability of high-purity material in and near major consumption centers. At the same time, sulfur supply volatility and geopolitical risk are prompting water treatment operators, food manufacturers, and industrial buyers to evaluate supplier diversification and regional inventory strategies more seriously. This realignment creates opportunities for suppliers that can offer reliable regional service, flexible contract terms, and transparent cost structures.
Third, application-specific innovation will open incremental growth avenues. Extended shelf-life solutions for bakery and beverage applications, expanded water treatment supply arrangements, and specialty grades for chemical synthesis and pharmaceutical use are areas where product development can translate into higher engagement and stickier demand. These opportunities are not large enough individually to transform the market, but collectively they support a growth trajectory that is more resilient than reliance on a single end-use sector.
The risks to this outlook are material. Sulfur feedstock disruptions can quickly affect production costs and availability, particularly if geopolitical tensions escalate or energy-sector emissions policies shift. Regulatory environments may become more restrictive in certain jurisdictions, raising compliance costs and limiting formulation flexibility. And in commoditized segments, price competition can compress margins for producers that lack differentiation. Decision-makers should plan for a market where growth is real but uneven, and where value capture depends increasingly on capability, reliability, and service rather than volume alone.
5. Strategic Recommendations for Decision-Makers
For manufacturers and producers, the priority is to align capacity and process investments with the segments that reward specification performance. Expanding high-purity capability, strengthening process control and emissions management, and developing application-specific grades for food, beverage, water treatment, and chemical synthesis can support premium positioning. Equally important is supply chain resilience: diversified feedstock sourcing, regional inventory strategies, and transparent cost mechanisms help protect margins during periods of input volatility.
For investors, the market offers selective opportunities rather than uniform upside. The highest-conviction cases are likely to be found where producers combine scale with purity and compliance capability, maintain regional supply advantages, and serve demand channels with durable specifications. Due diligence should focus on feedstock risk management, regulatory readiness, and the ability to sustain quality consistency across batch cycles. Capital allocation that favors differentiated capabilities over undifferentiated capacity additions is more likely to capture the market's value migration toward higher-specification segments.
For procurement and supply chain leaders, the focus should be on reducing exposure to raw-material volatility and ensuring specification reliability. Diversifying the supplier base across regions, securing long-term agreements with clear cost and quality terms, and prioritizing suppliers with documented compliance and traceability can improve resilience. Where applications are performance-sensitive, evaluating suppliers on purity consistency, shelf-life performance, and service coverage is more valuable than selecting solely on price. Inventory buffering for critical grades and scenario planning for feedstock disruptions can further reduce operational risk.
The dynamics described here reflect the current trajectory of the sodium metabisulfite market, but the detail that matters for execution lives in the segment-level data, the supplier-by-supplier capability profiles, and the region-specific demand and cost structures. For decision-makers who need to translate these trends into sourcing, investment, or capacity decisions, a deeper look at the segmentation, competitive positioning, and forward estimates can sharpen the plan. PW Consulting's full market research report provides that level of detail, including granular segmentation, competitive intelligence, and scenario analysis to support more precise strategy development.
Sodium Sulfide Market
For detailed analysis of this topic, please visit the official page: Sodium Metabisulfite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com