

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Volatile Corrosion Inhibitors VCI Packaging Market: $565M Base and 5.2% CAGR Trends

Navigating the Volatile Corrosion Inhibitors (VCI) Packaging Material Market: Strategic Trends & Commercial Opportunities
The global market for volatile corrosion inhibitors (VCI) packaging materials has matured from a niche protective solution into a critical component of modern supply chain resilience. Valued at approximately 565 million USD in the 2025 base year, the sector has demonstrated consistent expansion, growing from roughly 420 million USD in 2020 and tracking toward a projected 805 million USD by 2032. With a compound annual growth rate of 5.2 percent across the 2026-2032 forecast horizon, the market is no longer defined solely by volume replacement or basic metal preservation. Instead, it is evolving into a strategically differentiated segment where material science, regulatory compliance, and circular economy imperatives intersect.
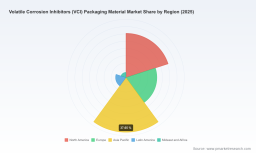
For executives and strategic planners, understanding this trajectory requires looking beyond headline figures. The steady growth trajectory masks underlying structural shifts: form factors are consolidating around films and bags, regional demand is rebalancing toward Asia Pacific while North America maintains premium positioning, and application portfolios are increasingly driven by automotive, electrical and electronics, and aerospace defense requirements. The market remains moderately fragmented, with a combined top-three share hovering around 32.5 percent and the top five reaching approximately 38.2 percent, creating a landscape where scale players coexist with specialized innovators. This configuration presents both consolidation pressures and whitespace opportunities for firms that can align chemistry capabilities with customer-specific protection requirements.
Current Market Landscape & Structural Challenges
A Market Defined by Protection Reliability and Material Evolution
VCI packaging materials have become indispensable for extending asset lifecycles, reducing warranty exposure, and enabling safer multimodal logistics. The core value proposition remains straightforward: releasing corrosion-inhibiting vapor phases that interrupt electrochemical degradation on metal surfaces during storage and transit. Yet the operational reality is more complex. Performance must hold across varying humidity levels, temperature swings, and extended dwell times, while packaging formats must integrate seamlessly with automated handling systems and existing industrial workflows.
The market's structural base reflects this balancing act. Bags and films collectively command the largest format share, driven by their versatility in wrapping, interleaving, and bulk containment applications. Papers continue to serve niche archival and lightweight wrapping needs, while other specialized formats address hybrid or high-performance scenarios. Application-wise, automotive remains a dominant anchor due to its scale and stringent quality thresholds, followed by electrical and electronics where oxidation control directly impacts component reliability. Aerospace and defense further elevate performance expectations, often requiring longer-duration protection and documented compliance trails.
Key Challenges and Inflection Points
Despite the positive growth outlook, the industry faces several structural pressure points that will shape competitive outcomes over the next cycle.
- Regulatory compression on chemical formulations: Environmental and chemical safety frameworks are tightening around traditional VCI chemistries. Amine-based inhibitors and phthalate-based plasticizers are increasingly scrutinized under evolving chemical management regimes, pushing formulators to redesign film compositions without compromising vapor-phase efficacy.
- Raw material cost volatility and trade friction: Petrochemical feedstocks and specialty chemical inputs remain central to film and bag production. Tariff escalations and export restrictions on key inputs have introduced cost uncertainty, forcing manufacturers to navigate margin compression while maintaining competitive pricing for end users.
- Performance-versus-sustainability trade-offs: Buyers increasingly expect corrosion protection to align with broader ESG commitments. This creates a dual challenge: maintaining proven inhibition performance while migrating toward recyclable, biodegradable, or lower-toxicity formulations. Early-stage alternatives can create qualification bottlenecks if durability or conformance data remain limited.
These challenges are not purely defensive. They are actively reshaping product roadmaps, supplier selection criteria, and regional sourcing strategies. Companies that treat regulatory and sustainability shifts as design constraints rather than compliance checkboxes are gaining measurable competitive distance.
Key Drivers Shaping the Market Trajectory
Technology Innovation in Chemistry and Format Engineering
Material innovation is moving the market beyond conventional inhibitor release patterns. Advances in polymer compounding, controlled-release architectures, and hybrid additive systems are enabling longer protection durations and broader substrate compatibility. The emergence of bio-resin integration and biodegradable film structures illustrates how chemistry development is expanding format possibilities while addressing end-of-life concerns. Recent product launches have demonstrated fully biodegradable film options, signaling that sustainability and protection performance can be engineered together rather than treated as competing priorities.
Equally important are improvements in application consistency and handling compatibility. Films and bags designed for uniform vapor distribution, improved tensile integrity, and compatibility with automated packaging lines reduce operational friction for high-volume industrial buyers. These engineering nuances often determine whether a VCI solution becomes a standard specification or remains a niche alternative.
Regulatory and Policy Environment as a Catalyst
Policy pressure is accelerating formulation redesign. Chemical safety thresholds under frameworks such as REACH and RoHS have already begun to restrict certain amine-based chemistries and phthalate plasticizers in VCI film compositions. At the same time, environmental certifications and regional chemical compliance programs are influencing procurement standards, especially for multinational manufacturers with strict supplier requirements.
These regulatory dynamics are creating a practical bifurcation. Suppliers with agile R&D capabilities can qualify new formulations, capture compliance-sensitive contracts, and establish themselves as preferred vendors in regulated supply chains. Conversely, slower-moving portfolios face increasing disqualification risk as procurement teams standardize on chemistry sets that preemptively meet emerging thresholds.
Demand-Side Shifts in Industrial and Logistics Behavior
Buyers are no longer treating VCI packaging as a commodity afterthought. Extended storage durations, longer transit routes, and higher value-density metal components have elevated corrosion protection from a logistics expense to a risk management investment. In automotive and electrical and electronics sectors, component sensitivity and downstream failure costs make consistent protection essential. In aerospace and defense, documentation, traceability, and protection duration often carry operational weight beyond simple corrosion prevention.
This shift changes the purchasing calculus. Procurement teams increasingly evaluate total cost of protection rather than unit price alone, considering factors such as rehandling risk, treatment redundancy, and the potential for packaging failures during storage or shipment. As a result, specification-driven adoption is becoming more common, favoring suppliers that can provide robust technical backing and repeatable performance data.
Supply Chain and Cost Structure Dynamics
Cost structures in VCI packaging are influenced by feedstock pricing, chemical input availability, and cross-border trade conditions. Tariffs on certain chemical exports and broader restrictions on specialty materials have added complexity to sourcing strategies. For film and bag producers, these pressures can translate into higher input costs and the need to diversify supplier bases or adjust geographic manufacturing footprints.
At the same time, supply chain resilience is becoming a competitive differentiator. Regional production capabilities, localized compounding operations, and closed-loop material programs are increasingly viewed as strategic buffers. These capabilities help stabilize cost exposure while supporting customer expectations around continuity and sustainability. The result is a market where operational flexibility and chemistry expertise jointly determine competitiveness.
Competitive Landscape and Leading Strategies
Differentiation Through Chemistry, Compliance, and Format Leadership
The competitive field combines established North American incumbents with European specialty players, each leveraging distinct strategic positioning. Leadership is increasingly defined not only by brand recognition but also by formulation control, regulatory readiness, and the ability to deliver protection across varied industrial contexts.
- Cortec Corporation has built its positioning around premium VpCI-branded films, bags, and papers. Its recent expansion into compounding operations for VpCI polymers and bio-resins reflects a strategy focused on vertically reinforcing chemistry capability and broadening material options.
- Northern Technologies International Corporation (ZERUST) emphasizes ICT-based corrosion prevention technologies across VCI films, bags, and papers. Its recent certification achievements for PCR-containing VCI film and the introduction of a closed-loop recycling program highlight a dual focus on regulatory alignment and circular material strategies.
- Daubert Cromwell is advancing biodegradable and recyclable VCI packaging through BioNatur® technology. The launch of a biodegradable film option and subsequent trade show presence indicate a strategy centered on sustainability differentiation and broad industry engagement.
- Armor Protective Packaging continues to maintain a strong footprint in VCI films, papers, and bags for rust prevention, with a practical, application-oriented market posture that serves a wide industrial buyer base.
- BRANOpac GmbH and MetPro Group represent European specialty supply strength, with BRANOpac focused on VCI films and papers for metal and automotive applications, while MetPro develops fabric-based systems such as BIOCOR solutions for specialized corrosion control needs.
- Transhield, Inc. takes a compounder-oriented approach, integrating VCI additives into protective materials and packaging for corrosion control, offering flexibility in customized material configurations.
These players illustrate a broader competitive dynamic: success increasingly depends on combining formulation know-how with customer-facing reliability, documentation, and sustainability readiness. The firms that lead are not necessarily the largest in every region, but those that can credibly align product performance with evolving procurement requirements.
Market Evolution and Structural Trends
The competitive landscape appears to be moving along two concurrent paths: specialization and selective consolidation.
PW Consulting
On the specialization side, companies are carving out advantage through biodegradable formats, recyclable systems, PCR-integrated films, and region-specific chemistry compliance. These moves attract buyers who need to meet internal sustainability targets or external regulatory expectations without sacrificing protection quality. On the consolidation side, mid-tier players face increasing pressure to differentiate or seek partnerships, distribution alignment, or product integration strategies that strengthen their reach and technical credibility.
New entrants and adjacent material suppliers are also monitoring the space, particularly where biodegradable film technologies, advanced polymer compounding, or closed-loop recycling models can be commercialized at scale. However, entry barriers remain meaningful because qualification cycles in industrial and defense applications can be lengthy, and performance validation is critical. This environment favors firms that can demonstrate repeatable chemistry performance, clear compliance positioning, and strong technical support during specification adoption.
Future Trends and Commercial Opportunities
Trend One: Compliance-Driven Formulation as a Market Filter
Over the next three to five years, chemical safety requirements will likely function as a market filter rather than a peripheral compliance issue. Formulations that proactively address restrictions on amine-based chemistries, phthalate-based plasticizers, and other scrutinized inputs will gain access to a broader set of industrial contracts, especially in regulated multinational supply chains. Meanwhile, products relying on older chemistry sets may face increasing specification exclusion.
VCI Anti Rust Paper Market
The commercial opportunity lies in early formulation substitution supported by validation data and customer-facing documentation. Suppliers that can offer compliant alternatives with comparable protection performance will be positioned to capture specification upgrades and preference in procurement shortlists. The risk, of course, is that performance trade-offs or insufficient qualification data can slow adoption and create openings for competing formulations.
Trend Two: Circular and Biodegradable Packaging as a Purchasing Criteria
Sustainability expectations are becoming more concrete, moving from aspirational language into purchasing criteria such as recyclability, biodegradability, recycled content, and closed-loop recovery options. Recent biodegradable film launches and closed-loop recycling initiatives signal that these concepts are transitioning from pilot narratives into commercial offerings.
This trend opens opportunities for companies that can integrate end-of-life considerations into product design without compromising protection. For buyers, the opportunity is twofold: reduce long-term waste exposure and strengthen ESG positioning while maintaining corrosion control integrity. The uncertainty centers on standardization. If definitions, certifications, and performance benchmarks remain fragmented, procurement teams may face comparison challenges that slow widespread adoption.
Trend Three: Regional Sourcing and Supply Chain Resilience
Cost volatility, tariff exposure, and raw material restrictions are encouraging regional diversification in sourcing and production. European chemical trade dynamics, for example, have already introduced cost pressures that affect packaging and chemical manufacturers. As a result, some buyers and suppliers are evaluating localized production footprints, broader supplier networks, and more flexible material sourcing strategies.
The strategic opportunity lies in resilience planning. Suppliers with multi-region capacity, adaptable compounding operations, or diversified input sourcing can better withstand cost shocks and trade disruptions. Buyers, in turn, can reduce single-point dependency by qualifying multiple suppliers and specifying corrosion protection solutions that are less vulnerable to localized input constraints. The main risk is that regional diversification may increase short-term coordination complexity and require more rigorous qualification oversight.
Strategic Recommendations for Decision Makers
For Manufacturers and Suppliers
Prioritize formulation agility and qualification readiness. The market is increasingly rewarding chemistry platforms that can adapt to regulatory shifts while maintaining protection performance. Invest in validation data, application testing, and documentation that procurement teams can use during specification reviews. Where possible, align product roadmaps with recyclable, biodegradable, or recycled-content options, but ensure these claims are backed by credible performance evidence.
Anticorrosion Tape Market
Also evaluate supply chain design with cost resilience in mind. Feedstock and chemical input exposure can affect margin stability, so diversified sourcing, regional production options, and forward inventory planning can become meaningful competitive advantages.
For Investors and Strategic Partners
Focus on differentiation quality rather than headline growth alone. The most attractive positioning often combines three elements: compliant chemistry capability, format versatility across films, bags, and papers, and credible sustainability or circular material programs. Companies that can demonstrate these attributes may be better placed to win specification-driven demand and navigate regulatory change.
At the same time, monitor fragmentation risk. Markets with moderate concentration can attract consolidation activity when leading players seek to extend regional reach, broaden format portfolios, or secure specialized chemistry technologies. Partnership and acquisition opportunities may emerge where smaller innovators hold differentiated formulations but lack scale or distribution breadth.
For Procurement and Sourcing Leaders
Move beyond unit-price comparisons toward total protection value. Evaluate candidates on performance consistency, regulatory readiness, documentation support, and end-of-life alignment with organizational sustainability goals. Where possible, qualify more than one supplier to reduce dependency on a single chemistry or geographic source, particularly in environments where raw material costs and trade conditions remain uncertain.
Use specification cycles to lock in future-proof requirements. By setting procurement standards that anticipate chemical safety thresholds and material recovery expectations, sourcing teams can reduce downstream re-qualification risk and improve long-term supply continuity.
Looking Ahead
The VCI packaging material market is entering a phase where growth is increasingly tied to technological adaptability, regulatory foresight, and buyer expectations around both protection and sustainability. The 5.2 percent forecast growth rate through 2032 reflects a market that continues to expand, but the real competitive story will be defined by how effectively companies navigate chemistry reformulations, cost volatility, and circular material demands.
For organizations seeking deeper segmentation data, region-specific sizing, application-level breakdowns, and company-level competitive assessments, a more detailed research compendium can provide the granularity needed for planning and investment decisions. PW Consulting's full market analysis offers expanded segmentation detail, scenario-based forecasts, and tailored commercial recommendations for stakeholders who need to move from strategic awareness to execution-ready intelligence.
For detailed analysis of this topic, please visit the official page: Volatile Corrosion Inhibitors (VCI) Packaging Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com