

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Ice Maker Market 2026: Beyond 3.73% CAGR—The Real Demand Shifts

The Ice Maker Market: Navigating Growth, Regulation, and Strategic Shifts Through 2032
Market Snapshots and Core Challenges
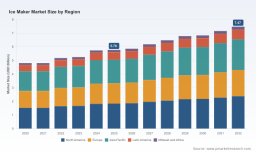
The global ice maker market has established a steady, value-driven growth trajectory over the past half-decade. Valued at approximately $4.81 billion in 2020, the sector climbed to $5.78 billion by 2025, reflecting a compound annual growth rate of 3.73 percent through 2032. This expansion is not explosive, but it is persistent, driven by structural demand in foodservice, healthcare, and retail environments that require reliable, high-volume ice production. The forecast period from 2026 to 2032 projects incremental gains, with the market expected to approach $7.47 billion by the end of the window. Such a path suggests a mature industry where incremental efficiency, regulatory compliance, and segment-specific innovation matter more than broad-based volume surges.
beneath this headline trajectory, the industry faces three interlocking challenges that will shape competitive outcomes over the next several years. The first is the tightening regulatory environment around energy consumption and refrigerants. Automatic commercial ice makers now operate under stricter performance thresholds, and the phase-down of certain refrigerants has altered equipment design, supply chain planning, and total cost of ownership calculations. The second challenge is input cost volatility. Rising prices for copper, steel, plastics, and critical components such as compressors have placed upward pressure on unit pricing, squeezing margins for manufacturers and prompting procurement teams to reassess specification decisions. The third challenge is market fragmentation combined with relatively low concentration. With the top three players holding roughly 24.6 percent of revenue and the top five around 26.2 percent, no single entity dominates the landscape. This opens the door for niche innovators and regional players, but it also means that scale advantages in manufacturing, distribution, and compliance management remain unevenly distributed.
For decision-makers, the implication is clear: the market rewards organizations that can navigate compliance without sacrificing operational reliability, manage input cost exposure through design and sourcing strategies, and position themselves in segments where performance differentiation translates into pricing power or share gains.
Key Drivers Reshaping the Market
Several structural forces are propelling change in the ice maker sector, and they interact in ways that create both pressure and opportunity.
Technology Innovation and Efficiency Gains
Advancements in compressor design, heat exchange optimization, and control systems are redefining what commercial and residential ice makers can deliver. Smart controls now allow operators to monitor production cycles, adjust output based on demand patterns, and reduce energy waste during idle periods. Modular cube designs and self-cleaning features are becoming more common in commercial units, lowering maintenance burden and improving hygiene standards. In the consumer segment, connected features and compact form factors have expanded the appeal of countertop units, particularly for households seeking convenience without sacrificing output.
These innovations are not merely incremental. They respond directly to the dual mandate of improving performance while meeting stricter energy standards. Manufacturers that integrate efficiency into the core architecture of their units, rather than retrofitting it, are better positioned to comply with evolving rules and to offer lower operating costs to buyers. The result is a competitive dimension where total cost of ownership, not just purchase price, increasingly influences procurement decisions.
Policy and Regulatory Environment
Regulatory dynamics are among the most consequential drivers in the current cycle. In the United States, automatic commercial ice makers with harvest capacities between 50 and 2,500 pounds per 24 hours must meet Department of Energy energy conservation standards. At the same time, the EPA's refrigerant restrictions under the American Innovation and Manufacturing Act have prohibited the manufacture or import of certain automatic commercial ice makers since January 1, 2025, with sales bans taking effect on January 1, 2026. These rules compel manufacturers to reformulate product lines, secure compliant refrigerants, and accelerate certification timelines.
The regulatory wave extends beyond North America. Australia's Greenhouse and Energy Minimum Standards (GEMS) Commercial Ice-makers Determination 2025 requires registration of covered models before sale, with a sales prohibition beginning on March 3, 2026. For multinational suppliers and distributors, this creates a patchwork of compliance obligations that demands coordinated product governance and regional readiness. The burden falls heaviest on organizations with fragmented product portfolios or slow certification processes, while those with streamlined compliance frameworks can turn regulatory readiness into a market entry advantage.
Worldwide Clear Ice Maker Market
Demand-Side Shifts in Foodservice, Healthcare, and Residential Segments
Demand patterns are evolving as end users reassess reliability, hygiene, and convenience. In foodservice, operators continue to prioritize consistent ice quality, rapid production, and durability under high-usage conditions. Modular designs and energy-efficient operations help reduce operating expenses in environments where margins are tight and uptime is critical. In healthcare, the need for clean, dependable ice production remains significant, with facilities emphasizing sanitation features and stable performance.
On the residential side, consumer interest in countertop ice makers has grown, particularly for nugget-style units that combine compact footprints with meaningful output. Colorway expansions and smart features reflect a broader push to position these appliances as lifestyle-enhancing products rather than purely utilitarian devices. This shift broadens the addressable market and invites competition from technology-oriented brands that bring connected functionality and low-maintenance designs to the segment.
Supply Chain and Cost Structure Dynamics
Input cost pressures are reshaping pricing strategies and product architectures. Copper, steel, and plastics have experienced cost increases, and component-level expenses for compressors and related parts have followed a similar trajectory. These dynamics affect the economics of commercial modular ice makers most directly, where material intensity and component specifications are significant. Manufacturers are responding with design optimization, localized sourcing where feasible, and selective price adjustments. Procurement teams, in turn, are weighing specification trade-offs more carefully, balancing performance requirements against budget constraints and lifecycle costs.
PW Consulting Automotive & Machinery Research Center
Supply chain resilience has also become a strategic priority. Organizations that diversify component sources, maintain buffer inventory for critical parts, and align production planning with regulatory milestones are better equipped to manage disruption. In a market where compliance deadlines and cost pressures converge, operational agility is a meaningful differentiator.
Competitive Landscape and Leading Strategies
The competitive field is characterized by a mix of established commercial manufacturers, consumer-focused appliance brands, and emerging technology-driven entrants. Rather than a single dominant playbook, leaders are pursuing differentiated strategies that align with their strengths and target segments.
Hoshizaki America has built its positioning around commercial ice machines spanning crescent, cubelet, flaked, and specialty types, with an emphasis on efficiency, durability, and North American production based in Georgia. This manufacturing footprint supports responsiveness to U.S. demand and provides a credible narrative around supply chain stability and regional service support. True Manufacturing Co., Inc. competes with commercial ice machines and bins featuring modular cube designs, highlighting class-leading energy efficiency, smart controls, and durable construction tailored for foodservice environments. Its focus on operational efficiency aligns well with procurement priorities in segments where energy and maintenance costs are closely scrutinized.
Naixer Refrigeration Equipment Co., Ltd. offers commercial ice machines including undercounter and high-capacity cube models, with self-cleaning features, air- and water-cooled options, and global certifications. This combination of features and compliance readiness supports expansion into hospitality and distributor channels, particularly in regions where certification and versatility are key purchase criteria. Recent participation in trade shows such as ABASTUR 2026 in Mexico City underscores a push into hospitality and distributor segments in Latin America, where demand for reliable commercial equipment continues to grow.
On the consumer side, GE Appliances has strengthened its presence with countertop nugget ice makers such as the Profile Opal series, which features side tank configurations and smart functionality. Product updates that expand finish availability, including new colorways, signal a strategy oriented toward aesthetic differentiation and broader consumer appeal. Frigidaire complements this landscape with compact countertop ice makers designed for high output and small footprints, targeting residential users who value space efficiency without sacrificing production. Govee Technology Co., Ltd. has entered the smart nugget ice maker space with products like the Smart Nugget Ice Maker Pro, emphasizing low-maintenance operation and full-capability features for modern homes. Its CES 2026 unveiling illustrates how technology brands are leveraging connectivity and convenience to compete in a segment traditionally dominated by appliance incumbents.
The landscape is evolving along multiple axes. Consolidation remains possible as larger players seek to broaden segment coverage or acquire niche capabilities, but fragmentation persists due to the diversity of product types, applications, and regional requirements. New entrants with smart features and differentiated designs are pressuring incumbents to accelerate innovation in consumer-facing products, while commercial manufacturers continue to compete on durability, efficiency, and compliance. The strategic implication is that success depends on segment-specific positioning: commercial leaders must demonstrate reliable performance and regulatory readiness, while consumer-oriented players must deliver convenience, aesthetics, and connected value that resonates with households.
Forward-Looking Trends and Commercial Opportunities
Looking ahead to the 2026-2032 window, several trends are likely to define the market's direction and create actionable opportunities.
Commercial Ice Machine Market
The first trend is the deepening integration of efficiency and smart functionality as baseline expectations rather than premium add-ons. As energy standards tighten and operators become more attentive to operating costs, units that optimize production cycles, reduce idle consumption, and provide actionable usage data will gain preference. Commercial manufacturers that embed these capabilities into core designs can differentiate on total cost of ownership and serviceability. Consumer brands that make connectivity intuitive and maintenance straightforward can expand adoption beyond early adopters. The opportunity lies in translating efficiency into a clear value proposition for buyers who evaluate both upfront price and long-term operating expense.
The second trend is regulatory harmonization pressure coupled with regional divergence. While the direction of travel is toward stricter energy and refrigerant requirements, the specifics vary by jurisdiction, and new rules can emerge with limited lead time. Organizations that build flexible compliance architectures, maintain transparent documentation, and prepare product portfolios for multiple regulatory scenarios will reduce the risk of market access delays. For suppliers with international ambitions, this is a strategic capability, not just a technical requirement. The opportunity is to treat compliance as a market access enabler, particularly in regions where registration and certification can act as barriers to less prepared competitors.
The third trend is segment-specific growth driven by demand quality and usage intensity. Foodservice and healthcare segments will continue to prioritize reliability, sanitation, and uptime, supporting demand for commercial units with robust construction and efficient operation. Retail and residential segments will see continued interest in compact, high-output, and aesthetically integrated solutions. The opportunity here is to align product development and channel strategy with the distinct purchasing criteria of each segment, rather than pursuing a one-size-fits-all approach. Manufacturers that can articulate clear segment value propositions are better positioned to capture share in high-priority applications.
These trends carry risks and uncertainties. Input cost volatility can compress margins and complicate pricing strategies, especially if cost increases outpace the ability to pass through adjustments. Regulatory timelines may shift, and enforcement patterns can vary, creating uncertainty for product planning. Competitive intensity in consumer-facing smart ice makers may accelerate price competition, challenging margins in segments where differentiation is harder to sustain. Additionally, regional demand trajectories can diverge based on economic conditions, hospitality activity, and healthcare investment cycles, making geographic planning more complex.
Strategic Imperatives for Decision-Makers
For manufacturers, the priority is to align product architecture with efficiency and compliance from the outset. Designs that integrate energy-saving controls, support compliant refrigerants, and reduce maintenance burden will be more resilient to regulatory change and more attractive to cost-conscious buyers. Modular platforms that can be adapted across cube, flake, and nugget formats, with options for air- and water-cooled configurations, provide flexibility to serve multiple segments without multiplying development costs. In parallel, manufacturers should strengthen supply chain planning for critical components and materials, anticipating cost volatility and regulatory milestones that affect availability and lead times.
For investors, the market offers a profile of steady growth with differentiated opportunities in efficiency-focused commercial equipment, compliance-ready portfolios, and consumer segments where smart features and design expand adoption. Due diligence should weigh regulatory readiness, segment mix, and total cost of ownership positioning as indicators of competitive durability. Companies that can demonstrate consistent performance in high-usage applications, maintain certification momentum across regions, and manage input cost exposure through design and sourcing are better placed to sustain margins and share. Investors should also monitor the pace of new entrants in smart consumer ice makers, where differentiation and brand positioning will determine whether premium positioning holds or gives way to price competition.
For procurement and operational leaders, the focus should be on specification decisions that reflect lifecycle economics rather than initial purchase price alone. Evaluating energy efficiency, maintenance requirements, sanitation features, and service support can reveal total cost advantages that are not visible in upfront comparisons. In commercial settings, aligning equipment choices with usage intensity and hygiene standards helps reduce downtime and operating expense. In residential or light-commercial contexts, balancing output, footprint, and connected functionality supports better user experience and longer-term satisfaction. Procurement teams should also track regulatory status when importing or deploying equipment across regions, ensuring that models meet local registration and refrigerant requirements before commitment.
Given the pace of regulatory change, the evolution of competitive strategies, and the variability of segment demand, timely access to detailed segmentation data, company-level benchmarks, and region-specific compliance mapping can sharpen planning significantly. A comprehensive research report can provide the granularity needed to assess subsegment size, growth differentials, competitive positioning, and scenario-based outlooks that support more precise investment, product, and procurement decisions. For organizations seeking to move from broad market awareness to targeted action, detailed intelligence offers a practical foundation for prioritizing initiatives and managing risk.
For detailed analysis of this topic, please visit the official page: Ice Maker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com