

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Circulating Tumor Cells Market: Why 13.9% CAGR Reshapes the Landscape

Circulating Tumor Cells Market: Strategic Dynamics and Commercial Opportunities Through 2032
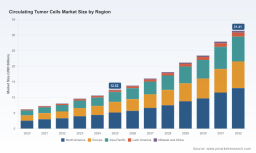
The circulating tumor cells (CTC) market has moved from exploratory science to a defined commercial segment, but its trajectory is shaped by a complex interplay of clinical adoption, regulatory clarity, pricing pressures, and technological differentiation. In 2025, the total market reached approximately 12.52 billion USD, up from 6.21 billion USD in 2020, reflecting sustained investment in liquid biopsy workflows, oncology diagnostics, and translational research infrastructure. Over the 2026–2032 forecast period, the market is projected to grow at a compound annual growth rate of 13.92 percent, expanding to an estimated 31.41 billion USD by 2032. This pace signals a maturing ecosystem in which scale, standardization, and evidence generation will increasingly determine who captures sustainable value.
Yet the headline growth curve conceals structural tensions. Several forces are converging to redefine competitive positioning, pricing models, and adoption pathways. For executives, investors, and procurement teams, the strategic question is no longer whether CTC-based approaches will matter, but how value will be created and protected as the segment matures. The following analysis examines the core challenges, demand and supply-side drivers, competitive positioning, and forward-looking trends that will shape commercial decisions over the next three to five years.
Market Landscape: Scale, Structure, and the Constraints Shaping Growth
The CTC market’s expansion from roughly 6 billion USD in 2020 to over 12.5 billion USD in 2025 reflects a segment that has crossed an adoption inflection point in selected oncology workflows. Growth has been supported by the broader liquid biopsy narrative, increasing use of minimally invasive sampling in clinical and research settings, and sustained capital into enrichment, detection, and analysis workflows. Forecast momentum through 2032 suggests the segment will continue to outpace many adjacent diagnostics categories, but the composition of that growth is becoming more nuanced.
Clinical Utility, Reimbursement Ambiguity, and Evidence Standards
One of the most consequential constraints is the gap between technical capability and demonstrated clinical utility. Despite rapid innovation, CTC-based testing remains under scrutiny for many routine cancer management indications. Coverage and policy frameworks in several major markets treat detection and enumeration as investigational for a broad set of use cases, creating uncertainty around reimbursement and adoption outside narrowly defined scenarios. This does not halt growth, but it changes its shape. Commercial activity increasingly concentrates in applications where evidence generation is strongest, where testing is embedded in clinical trial operations, or where providers can justify use through specific decision-support pathways.
For commercial leaders, this environment rewards precision over breadth. Companies that anchor their value proposition in measurable clinical outcomes, standardized workflows, and clearly defined patient populations are better positioned to navigate coverage ambiguity. The strategic implication is that product development and market entry cannot rely solely on analytical performance; they must be paired with evidence generation plans, health economics positioning, and real-world data strategies that align with payer and guideline expectations.
Regulatory Fragmentation Across Indications and Use Cases
A second challenge is regulatory fragmentation. While certain CTC-based tools have achieved regulatory clearance for specific enrichment or enumeration purposes, most CTC indications lack cleared clinical tests with broad clinical management claims. This uneven landscape creates a two-speed market: applications with clear regulatory endpoints advance more predictably, while broader diagnostic or monitoring claims must contend with a more cautious policy environment. The result is a segment in which regulatory status, rather than technology alone, often determines the speed and scale of adoption.
This fragmentation also shapes competitive strategy. Some organizations are pursuing narrowly defined regulatory pathways to secure early commercial footing, while others are building platforms designed to expand across indications as evidence matures. In both cases, regulatory strategy is becoming inseparable from product strategy. Executives evaluating entry or expansion must assess not just the science, but the likely cadence of clearance, labeling constraints, and the implications for commercialization timelines.
Platform Fragmentation and the Standardization Imperative
A third structural challenge is the diversity of technical approaches, which can complicate standardization, comparability, and large-scale adoption. Enrichment, detection, and analysis workflows are evolving along multiple technological paths, and differences in sample handling, cell capture efficiency, and downstream readout can create variability across sites and studies. In research settings, this variability may be acceptable or even useful; in routine clinical deployment, it can hinder reproducibility and slow institutional adoption.
Standardization is therefore emerging as a commercial differentiator. Platforms that offer consistent workflow integration, clearer quality controls, and compatibility with existing laboratory infrastructure are likely to gain advantage as adoption moves from specialized centers to broader diagnostic networks. The opportunity lies not simply in improving sensitivity or throughput, but in reducing operational friction, enabling multicenter comparability, and supporting the evidence pipelines that payers and guideline bodies require.
Key Drivers: What Is Propelling the Market Forward
Technology Innovation and Platform-Level Differentiation
Technology development remains the most visible growth driver, but the nature of innovation is shifting from isolated performance improvements to platform-level capability. Recent product enhancements illustrate this transition. For example, the introduction of next-generation CTC detection platforms with expanded biomarker compatibility signals a broader emphasis on flexibility, multiplexing, and integration with downstream molecular workflows. At the same time, no-cell-loss detection approaches and advanced isolation technologies are being evaluated in clinically important populations, including metastatic prostate and ovarian cancers, where tumor cell characterization may support treatment monitoring and resistance insights.
The commercial significance of this innovation cycle is that differentiation increasingly depends on combining detection performance with workflow usability and biomarker adaptability. Platforms that can accommodate varied sample types, support multiple analytical endpoints, and fit into existing laboratory routines have a stronger path to adoption than those competing solely on isolated metrics. For decision-makers, this means evaluating vendors not just by technical specifications, but by the coherence of their platform strategy, the realism of their evidence roadmap, and the degree to which their solution reduces operational complexity.
Demand-Side Shifts Toward Minimally Invasive Monitoring and Longitudinal Insights
On the demand side, there is a continuing shift toward less invasive sampling and longitudinal disease monitoring. Oncology workflows increasingly value tools that can complement tissue-based diagnostics, support treatment response assessment, and provide repeated sampling where tissue access is limited. This demand is not uniform across all cancer types or care settings, but it is strong enough to sustain commercial interest in CTC-based approaches as part of broader liquid biopsy and companion diagnostic ecosystems.
Interest is also being shaped by trial operations and translational research needs. In clinical development, CTC workflows can help characterize circulating disease biology, support biomarker discovery, and enable serial sampling across treatment cycles. In applied clinical settings, the emphasis is more selective, focused on indications and workflows where testing can inform decision-making without creating ambiguity. The practical takeaway is that demand is strongest where CTC testing solves a clear operational or clinical problem, rather than where it is positioned as a generalist solution.
Regulatory and Reimbursement Dynamics: Navigating the Adoption Gateways
Regulatory and reimbursement conditions are not only constraints; they also structure the market’s growth pathways. Clear regulatory status for specific intended uses can create dependable adoption routes, while reimbursement coding for enumeration and interpretation provides a transactional framework for certain applications. At the same time, policies that classify many CTC uses as investigational maintain pressure on manufacturers and users to build stronger evidence bases before expanding claims.
This dynamic encourages a strategic split. In applications with established regulatory and coding support, commercial activity can scale more directly through laboratory adoption and defined payment pathways. In other areas, growth depends more heavily on research use, clinical collaborations, and incremental evidence generation. Companies that understand this bifurcation can allocate resources more effectively, targeting near-term commercialization where the gateway is clearest while investing in longer-cycle evidence generation for broader indications.
Supply-Side and Operating Model Considerations
Cost structures and supply-chain realities are becoming more important as the market scales. CTC workflows involve specialized reagents, instrument access, sample handling requirements, and skilled interpretation, all of which influence total cost of ownership and adoption feasibility. As more laboratories and institutions evaluate these solutions, the economics of workflow integration, throughput, training, and service support will matter as much as the underlying technology.
This creates opportunity for providers that simplify implementation and reduce hidden operational burdens. Solutions that offer clearer consumables economics, dependable instrument service, and training support can gain advantage in competitive evaluations. For purchasers, the strategic question is less about unit price alone and more about the full cost of reliable, reproducible deployment across patient volumes and laboratory conditions.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive environment reflects a mix of specialized CTC providers, broader diagnostics and life-science companies, and emerging entrants pursuing distinct technical or clinical niches. Several organizations have established recognizable positions by aligning their product portfolios with specific workflow stages, regulatory statuses, and application foci.
Distinct Strategic Positions Among Core Players
Menarini Silicon Biosystems has built a recognized position around CTC enumeration and isolation, with an FDA-cleared test historically associated with metastatic breast, colorectal, and prostate cancers and a complementary system for cell handling and analysis. Its recent introduction of an enhanced detection platform with wider biomarker compatibility underscores a strategy oriented toward expanding the analytical versatility of an established workflow. The strength of this positioning lies in regulatory familiarity, established clinical associations, and incremental platform evolution that can support broader research and clinical exploration without abandoning a known user base.
ANGLE plc, now operating as CelLBxHealth, has emphasized a hardware-first approach with a system designed to harvest intact CTCs from blood samples, including regulatory clearance for specific enrichment use. Interim clinical study results evaluating the system for monitoring ovarian cancer treatment illustrate a move toward application-specific evidence generation. This suggests a strategy centered on demonstrating utility in defined clinical contexts where intact cell capture may offer distinct advantages, rather than competing broadly on enumeration alone.
PW Consulting
QIAGEN occupies a different position through immunomagnetic enrichment kits that fit into broader molecular and diagnostics workflows. Its offering reflects an emphasis on sample preparation and enrichment within established laboratory ecosystems, appealing to organizations that seek modularity and integration with existing processes. Bio-Techne adds further diversity with exosome diagnostics and CTC analysis solutions spanning research and clinical applications, highlighting the increasingly blurred boundary between CTC-focused tools and wider circulating biomarker strategies.
How Leading Players Differentiate
Across these examples, differentiation is emerging along several axes:
Worldwide Urine Cytology Market
- regulatory status and intended-use specificity, which shape adoption speed and commercial claims;
- platform versatility, including biomarker flexibility, compatibility with downstream analysis, and integration into laboratory routines;
- evidence-generation orientation, with some players emphasizing clinical collaborations and indication-specific studies; and
- workflow economics and operational support, which influence scalability across sites and volumes.
The market is therefore not converging on a single winning architecture. Instead, it is stratifying into segments where different strengths matter most: regulatory-driven clinical use, research and translational workflows, and application-specific monitoring or characterization. Companies that understand which segment they are targeting, and design their product, evidence, and commercial strategies accordingly, are better positioned to avoid diffused positioning.
Consolidation, Specialization, and New Entrant Risk
Market concentration remains meaningful, with a substantial share of revenue associated with a relatively small group of established players. This concentration suggests that scale, brand familiarity, and installed-base dynamics still matter, particularly where adoption depends on regulatory familiarity and laboratory trust. At the same time, the presence of multiple technical approaches and the ongoing flow of clinical collaborations indicate room for specialization and targeted entry.
The most likely evolutionary pattern is not uniform consolidation, but a mix of consolidation in established platforms and fragmentation in niche applications. Larger organizations may seek to broaden portfolios through internal development or selective acquisition, especially where complementary technologies strengthen workflow integration or biomarker breadth. Meanwhile, new entrants may find opportunity in focused clinical use cases, novel isolation or detection concepts, or applications where existing platforms are less differentiated. For investors and executives, the key is to assess whether a given entrant is addressing an underserved clinical or operational need with a credible evidence path, or simply adding another undifferentiated option to a crowded field.
Strategic Outlook: Three Trends Shaping the Next 3–5 Years
Trend 1: Evidence-Led Commercialization Will Become the Primary Growth Filter
Over the next several years, the pace and pattern of adoption will be increasingly determined by the quality and specificity of clinical evidence. As policy and payer scrutiny persists for many indications, the commercial winners are likely to be those that can demonstrate clear value in defined scenarios, whether in treatment monitoring, resistance characterization, trial enrichment, or selected diagnostic pathways. This will favor organizations that treat evidence generation as a core commercial capability rather than a supporting activity.
Opportunities will accrue to players that can align product design, clinical collaborations, and real-world data strategies around specific use cases. Risks include overgeneralization, premature claims expansion, and reliance on technical performance alone without a credible path to accepted clinical utility. For decision-makers, the practical implication is to evaluate CTC investments through the lens of indication-specific evidence, not market-level enthusiasm.
Trend 2: Integration with Broader Liquid Biopsy and Circulating Biomarker Workflows
CTC analysis is unlikely to remain isolated from the wider circulating biomarker landscape. Expectations are growing for integrated views that combine cellular and molecular information, support multimodal interpretation, and fit into comprehensive oncology workflows. This creates momentum for platforms and services that can interoperate with broader diagnostic strategies, whether through combined sample handling, complementary readouts, or informatics support.
The commercial opportunity is in interoperability and workflow coherence. Providers that enable smoother handoffs between enrichment, detection, analysis, and downstream interpretation will have an advantage as laboratories seek to manage complexity and cost. The risk is that fragmentation increases if too many point solutions compete without common data or workflow standards, making integration expensive and adoption slower.
Trend 3: Geographic and Segment Diversification With Uneven Pace
Growth will continue across regions and application segments, but not uniformly. Markets with stronger laboratory infrastructure, clearer regulatory and reimbursement frameworks, and higher oncology diagnostic spend are likely to adopt faster, while other regions will progress more selectively, often led by research institutions, specialized centers, or trial-related activity. Similarly, clinical and research applications will continue to differ in their adoption curves, with research use often paving the way for more focused clinical deployment.
This unevenness creates both opportunity and caution. Organizations with international ambitions need region-specific regulatory, reimbursement, and operational strategies rather than a single global playbook. Investors should expect variation in time-to-scale across geographies and applications, and purchasers should consider local adoption readiness when planning deployment. A key risk is assuming that growth in one segment or region will translate automatically into another.
Implications and Action Levers for Decision-Makers
For Manufacturers and Technology Developers
Prioritize indication clarity and evidence readiness alongside technical performance. A strong platform is necessary but not sufficient; the most durable commercial positions will come from aligning intended use, regulatory pathway, and evidence generation with a clearly defined adoption scenario. In practice, this means choosing where to compete, designing for workflow integration, and investing in the studies and real-world data that support reimbursement and guideline inclusion where applicable. Differentiation should be expressed not only in analytical capability, but in operational reliability, biomarker flexibility, and the ability to reduce adoption friction.
For Investors
Evaluate CTC exposure through the lens of evidence trajectory, regulatory status, and workflow economics. Companies with clear clinical use cases, credible study pipelines, and defensible differentiation in enrichment, detection, or analysis may offer stronger risk-adjusted opportunities than those competing primarily on breadth or narrative. Pay attention to whether a business is building a repeatable commercial model around specific indications or depending on broad adoption assumptions. Also consider the increasing importance of integration, service, and total cost of ownership, since these factors often determine whether a technically strong solution becomes commercially durable.
For Procurement and Laboratory Decision-Makers
Assess total workflow impact rather than instrument or kit specifications alone. The most relevant evaluation criteria include reproducibility across operators and sites, compatibility with existing sample handling and molecular workflows, training and service support, consumables and operating economics, and the availability of evidence or guidance relevant to your intended use. Where regulatory or reimbursement status is limited, align adoption with research or clearly justified clinical objectives, and treat vendor selection as a multi-year operational decision rather than a discrete purchase.
Conclusion: Turning Market Momentum into Defensible Positioning
The circulating tumor cells market is entering a phase in which growth is increasingly defined by evidence, integration, and operational fit. Strong top-line expansion and a robust forecast trajectory indicate sustained interest, but the distribution of value will depend on how effectively organizations navigate regulatory ambiguity, reimbursement uncertainty, standardization demands, and the need for indication-specific clinical utility. Platforms that combine technical credibility with workflow usability, evidence discipline, and clear targeting of high-value use cases are best positioned to convert market momentum into durable advantage.
For executives and investors seeking a sharper view of subsegment dynamics, competitive benchmarking, and tailored go-to-market implications, the full PW Consulting market research report provides deeper segmentation detail, company-level profiles, and scenario-based interpretation designed for strategic planning. In a market where adoption pathways are becoming more selective, the advantage belongs to those who can move beyond aggregate growth figures and into the operational and clinical specifics that determine real commercial outcomes.
Molecular Diagnosis Of Tumors Market
For detailed analysis of this topic, please visit the official page: Circulating Tumor Cells Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com