

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Why $5.15B Mouthwash Market’s 5.57% CAGR Reshapes Industry Competition

Navigating the Mouthwash Market: Strategic Trends and Commercial Opportunities Through 2032
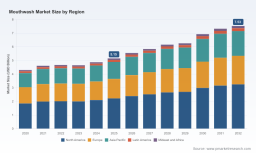
The global mouthwash market is entering a phase of disciplined expansion, moving past the volatility of the early 2020s and settling into a trajectory defined by steady volume growth, evolving consumer expectations, and a tightening regulatory landscape. Between 2020 and 2025, the market climbed from approximately USD 4.3 billion to an estimated USD 5.15 billion, reflecting a compound annual growth rate of 5.57% across the period. Looking ahead to 2032, the sector is projected to reach roughly USD 7.53 billion, with incremental annual gains accelerating modestly as therapeutic positioning, premium natural formulations, and regional penetration strategies converge. The market remains moderately concentrated, with the top three players accounting for just over half of total revenue and the top five commanding more than 70%, a structure that underscores both the enduring power of established brands and the space available for differentiated challengers.
For executives and investors, the headline numbers tell only part of the story. The real strategic value lies in understanding how the underlying dynamics are shifting: from a category historically anchored in cosmetic breath freshening toward a more clinically credible, wellness-adjacent proposition; from a relatively stable supply environment to one reshaped by input cost variability and packaging affordability concerns; and from broad-based growth to a more segmented landscape where regulatory compliance, claim substantiation, and consumer trust increasingly determine which products capture shelf space and repeat purchases.
PW Consulting Health Care Research Center
The following analysis maps the forces shaping the mouthwash market through 2032, highlights how leading companies are positioning themselves, and translates these dynamics into actionable considerations for manufacturers, investors, and procurement teams.
Market Snapshot: Scale, Trajectory, and the Turning Points Ahead
The mouthwash market has demonstrated resilience through a period of macroeconomic uncertainty, but the path forward is less about uniform expansion and more about selective outperformance within a maturing category. The broad upward trajectory reflects a combination of population growth, rising oral hygiene awareness, and the gradual migration of mouthwash from a secondary bathroom accessory to a more integral part of daily oral care routines. Yet the growth is not evenly distributed across all product types or regions, and several structural pressures are beginning to reshape competitive dynamics.
Beneath the aggregate growth figure, three interconnected challenges stand out as defining turning points for the industry:
-
Affordability and purchase frequency under pressure. Economic turbulence and heightened price sensitivity have altered how consumers buy oral care products. Rather than abandoning the category, many shoppers are adjusting pack sizes, seeking promotions, or trading down within brands. This shifts the competitive battleground from pure product innovation to pricing architecture, bundle strategies, and value communication. Companies that rely on premium price points without clear differentiation risk witnessing erosion in repeat purchase rates, while those that can maintain perceived efficacy at accessible price points are better positioned to defend share.
-
Regulatory scrutiny on claims and product safety. Enforcement activity around labeling, substantiated efficacy claims, and manufacturing standards is becoming more visible and consequential. Authorities are increasingly focused on products that make assertions about plaque removal above the gum line or gum health promotion without adequate evidence, as well as on facility compliance and documentation practices. For mouthwash manufacturers, this means that marketing agility must be balanced with robust clinical and regulatory validation. The cost of non-compliance, whether through warning letters, recalls, or import holds, is rising in both financial and reputational terms.
-
Supply chain and input cost variability. Volatility in raw material availability, packaging inputs, and compliance-related facility costs is compressing margins for many producers. At the same time, consumer price sensitivity limits the extent to which costs can be passed through without affecting volume. This environment rewards manufacturers that have built flexible sourcing strategies, efficient production footprints, and the ability to adjust pack formats and formulations without compromising quality or claim integrity.
Taken together, these forces suggest that the next phase of market growth will be less about category-level tailwinds and more about which companies can navigate affordability constraints, regulatory expectations, and supply-side disruptions while still delivering products that consumers trust and repurchase.
Core Drivers Reshaping the Mouthwash Landscape
Several structural drivers are interacting to determine where growth will concentrate and how competitive advantage will be earned. The most consequential of these revolve around product innovation, regulatory evolution, consumer behavior, and cost and supply chain dynamics.
Innovation Moving Beyond Freshness Toward Functional Credibility
Mouthwash innovation is increasingly defined by the pursuit of functional credibility rather than sensory appeal alone. While cosmetic formulations remain a meaningful part of the category, the more dynamic growth is coming from products that position around gum health, sensitivity relief, and targeted antimicrobial benefits. This shift is not merely a labeling exercise; it reflects a broader consumer inclination toward oral care products that feel connected to long-term wellness outcomes. As a result, brands are investing more heavily in formulation science, clinical validation, and tiered product architectures that allow consumers to select products based on specific concerns rather than generic freshness.
This trend also creates a clearer divide between products that can support their positioning with credible evidence and those that cannot. Manufacturers that build disciplined claim substantiation processes and communicate benefits in precise, compliant language are gaining an edge in credibility-sensitive channels, including retail pharmacy, dental professional recommendations, and digitally informed consumer segments. Conversely, products that rely on broad or ambiguous health assertions face greater exposure to regulatory scrutiny and consumer skepticism.
Regulatory and Compliance Dynamics as a Competitive Filter
The regulatory environment is becoming a more active determinant of which products can scale efficiently. Enforcement actions and guidance updates have drawn sharper boundaries around acceptable labeling, appropriate target populations, and the evidentiary basis for oral health claims. For example, regulatory attention has increasingly focused on products with unproven claims regarding plaque removal above the gum line or the promotion of healthy gums, while separate actions have addressed ingestible fluoride products for children and the importance of clear lot coding and manufacturing documentation.
These developments matter beyond compliance alone. They shape consumer trust, retailer confidence, and the operational cost structure of bringing products to market. Facility fees, documentation requirements, and the need for rigorous quality systems add to the operational baseline that manufacturers must manage. In practical terms, regulatory maturity is becoming part of competitive positioning: companies with established quality infrastructure, well-maintained labeling practices, and proactive engagement with evolving standards are better equipped to avoid disruptions and to defend their product portfolios as standards tighten.
Consumer Behavior: Wellness Adjacency, Personalization, and Value Sensitivity
Consumer behavior in the mouthwash category is being shaped by three overlapping forces. First, oral care is increasingly viewed through a wellness lens, with consumers linking daily hygiene habits to broader health consciousness. This supports demand for products that feel purposeful rather than purely cosmetic. Second, there is growing interest in natural and organic formulations, driven by preferences for botanical ingredients and simpler ingredient narratives. This has encouraged a segment of the market to expand around plant-based and naturally positioned mouthwashes, even as the majority of category revenue continues to come from conventional formulations.
Third, and critically, value sensitivity remains a dominant behavior trend. Consumers are not necessarily leaving the category, but they are becoming more deliberate about pack size, frequency of purchase, and the perceived value of premium claims. This means that product strategy cannot be separated from pricing strategy. Brands that succeed in this environment often do so by offering clear benefit differentiation at multiple price tiers, using bundle offers and smaller pack formats strategically, and ensuring that higher-priced options deliver discernible differences in formulation, experience, or substantiated outcomes.
Supply Chain and Cost Structure Pressures Refining Operational Strategy
Cost structure and supply chain resilience are increasingly central to commercial performance. Manufacturers are operating in an environment where input availability, packaging materials, and compliance-related expenses can shift unpredictably. At the same time, the ability to pass through cost increases is constrained by consumer price sensitivity and retail dynamics. The result is a market where operational efficiency is not simply a margin issue but a strategic necessity.
Leading players are responding by emphasizing process efficiency, packaging flexibility, and formulation robustness. Smaller pack sizes and bundled promotions have become important tools for maintaining accessibility and repeat purchase behavior without undermining overall brand positioning. In addition, the growing focus on facility fees and quality system requirements for drug-classified or monograph-related products underscores the importance of planning for regulatory operating costs as a structural part of the business model rather than an intermittent overhead.
Mouthguard Market
Competitive Landscape: Positioning, Differentiation, and the Shape of Future Rivalry
The mouthwash market is characterized by a blend of well-established consumer health and oral care brands, each leveraging distinct strategic strengths. The competitive structure is concentrated enough that scale, distribution, and brand recognition confer meaningful advantages, yet differentiated enough that targeted formulations, clinical positioning, and niche consumer segments can still create durable niches.
Several leading players illustrate the variety of strategic postures currently in play. One major brand owner has built a strong association between its mouthwash line and antiseptic and fresh-breath benefits, using a broad product range that spans whitening, essential care, and antiseptic variants. Its positioning emphasizes familiarity, breadth, and everyday oral hygiene routines. Another large oral care manufacturer has leaned into therapeutic and sensitivity-focused mouthwashes, using clinically oriented product names and efficacy claims to signal functional benefit beyond cosmetic freshness. A separate consumer health player has focused on gum health therapeutic positioning, reinforcing a more clinical, concern-specific identity within the category.
At the same time, smaller or more specialized companies are carving out space through natural and botanical formulations or through breath-freshening products with distinctive ingredient stories. These players often compete not on scale but on narrative clarity, ingredient positioning, and alignment with consumer preferences for simpler or more natural product profiles. Their presence contributes to a market that is diversified in product philosophy even where overall revenue remains concentrated among the largest brands.
Recent industry events have also highlighted the operational and compliance risks that can affect even well-established participants. A notable recall involving a gum health mouthwash due to lot code issues, alongside a separate warning letter related to manufacturing practice concerns and potential contamination in a children’s mouthwash product, illustrate how quality system lapses or labeling gaps can quickly become commercial and reputational issues. These incidents reinforce that operational discipline is a competitive asset: brands that maintain rigorous documentation, lot control, and manufacturing standards are better positioned to avoid interruptions and preserve retailer and consumer confidence.
On the regulatory front, broader enforcement activity has added further context to how competition will evolve. Attention to unapproved ingestible fluoride products for young children, warnings around unproven plaque and gum claims, and import alerts targeting products that fail labeling or safety standards all point to a more exacting compliance environment. Combined with updated facility fee structures for monograph-related drug facilities and contract manufacturers, these developments raise the operational baseline for scaling products that fall under more stringent regulatory expectations. The practical implication is that competitive advantage will increasingly belong to companies that treat regulatory readiness, claim integrity, and quality systems as integral to product strategy rather than as back-office functions.
Worldwide Germicidal Mouthwash Market
How the Competitive Structure Is Evolving
The market is likely to continue evolving along several overlapping paths. First, consolidation pressure may persist among smaller players who struggle to absorb rising compliance costs, input variability, and the investment required for credible therapeutic positioning. Second, differentiation is expected to deepen between cosmetic, therapeutic, and natural segments, with each segment demanding different sets of capabilities: clinical substantiation for therapeutic products, ingredient and sourcing credibility for natural products, and strong brand equity with efficient packaging for cosmetic freshness products. Third, new entrants and smaller challengers are likely to focus on narrow, well-defined consumer needs or ingredient narratives rather than attempting to compete broadly on scale, using targeted distribution and digital engagement to build presence without requiring immediate national dominance.
For incumbents, the strategic question is less about whether to defend share and more about how to allocate resources across scale efficiency, claim-supported innovation, and affordability-oriented pack and pricing strategies. The most resilient players will be those that can move fluidly across these priorities without diluting brand clarity or compliance rigor.
Future Outlook: Three Trends to Watch Through 2032
Based on current market dynamics, regulatory direction, and consumer behavior patterns, several trends are likely to shape the mouthwash market over the next three to five years.
1. Functional and wellness-adjacent positioning will keep gaining share, but only with credible substantiation
The shift from purely cosmetic mouthwash toward products that address gum health, sensitivity, and targeted antimicrobial needs is expected to continue. Consumers are increasingly receptive to mouthwash as part of a broader oral wellness routine, and this supports demand for products with clear functional intent. However, the opportunity is contingent on disciplined claim support and precise communication. Products that can demonstrate measurable benefit and present that benefit in compliant, understandable language will be better positioned to command premium consideration and repeat purchase. The risk is that aggressive or vague health messaging will face growing regulatory and consumer pushback, narrowing the highway for products that lack substantiation.
2. Natural and organic mouthwash will keep expanding as a distinct growth corridor
Demand for natural and organic mouthwash is likely to keep growing as a meaningful subset of the category, supported by ingredient transparency preferences and a broader interest in botanical formulations. This trend creates opportunities for brands that can combine clean ingredient narratives with acceptable sensory experience and shelf stability. The commercial challenge lies in balancing naturalness with performance expectations and regulatory compliance. Natural positioning alone will not be sufficient if products fail to deliver consistent freshness, usability, or trust. Brands that can integrate natural formulations with rigorous quality control and credible benefit communication are more likely to convert interest into sustained category participation.
3. Affordability-focused product architecture will become a central strategic lever
Given persistent price sensitivity and the use of smaller pack sizes and bundled promotions to maintain accessibility, product architecture will increasingly matter as much as product formulation. Companies that design portfolios with clear value tiers, flexible pack formats, and promotional strategies that protect both volume and brand perception will be better equipped to navigate consumer budget constraints. This is not simply a pricing tactic; it is a structural requirement for maintaining repeat purchase behavior in a category where consumers are willing to adjust how they buy even if they do not abandon the category entirely. Manufacturers that treat affordability as a design parameter—rather than an afterthought—are more likely to preserve share during periods of economic pressure.
Strategic Implications for Decision-Makers
The mouthwash market through 2032 will reward companies that align product strategy with regulatory readiness, consumer value expectations, and operational resilience. The following considerations are intended to help manufacturers, investors, and procurement teams translate market dynamics into practical priorities.
For Manufacturers
-
Strengthen claim substantiation and labeling discipline as core capabilities. As enforcement around unproven plaque and gum claims and safety-related documentation continues to intensify, the ability to support product positioning with robust evidence and precise language should be treated as a competitive necessity rather than a legal safeguard alone.
-
Build affordability into portfolio design. Develop tiered product architectures, flexible pack formats, and promotional strategies that preserve accessibility without undermining perceived value. This helps maintain repeat purchase behavior when consumers are managing budgets tightly.
-
Invest in quality systems and supply chain flexibility. With facility-related costs and input variability both in play, operational resilience should be planned intentionally. Lot control, manufacturing documentation, and sourcing adaptability can reduce the risk of disruptions and protect brand trust.
For Investors
-
Differentiate between scale advantages and credible differentiation. Market concentration remains significant, but the more durable growth opportunities are likely to come from brands that combine functional credibility, compliance maturity, and clear consumer value propositions rather than from broad-based category expansion alone.
-
Watch regulatory readiness as a risk and valuation factor. Companies with strong quality systems, disciplined labeling, and proactive engagement with evolving standards are better positioned to avoid costly enforcement events and to scale more predictably. Conversely, compliance exposure can translate quickly into reputational and commercial drag.
-
Monitor the natural and therapeutic segments for divergent investment theses. Natural mouthwash offers growth tied to ingredient preference and wellness adjacency, while therapeutic positioning offers potential for higher credibility-based differentiation. Each path requires different capabilities and carries different risk profiles.
For Procurement and Channel Decision-Makers
-
Prioritize supplier reliability and documentation quality. Given recent enforcement events and ongoing labeling and safety scrutiny, procurement decisions should account for the strength of a supplier’s quality systems and traceability practices, not just cost and product attributes.
-
Manage portfolio balance across price tiers and benefit claims. Shelf and channel strategies will be most effective when they reflect both the consumer’s desire for credible benefits and the reality of value sensitivity. Balancing cosmetic, therapeutic, and natural options with clear price architecture can support both traffic and margin objectives.
-
Plan for regulatory and compliance variability in sourcing timelines. Facility fees, import scrutiny, and documentation requirements can affect speed-to-market and operational continuity. Procurement plans that factor these elements in early are better positioned to avoid disruption.
Conclusion
The mouthwash market is moving into a period where growth will be earned through credibility, operational discipline, and consumer value alignment rather than through category tailwinds alone. The projected expansion from just over USD 5.15 billion in 2025 toward roughly USD 7.53 billion by 2032 reflects genuine opportunity, but that opportunity will be unevenly distributed across companies that can navigate affordability pressures, regulatory expectations, and supply-side variability while still delivering products that consumers trust and repurchase.
For organizations seeking to act on these dynamics with greater precision, deeper segmentation data, region-specific volume and revenue estimates, and tailored scenario analysis can make a meaningful difference in strategy design and execution timing. Readers interested in a more detailed assessment of market sizing by segment, competitive positioning, and forward-looking risk and opportunity mapping can explore the full PW Consulting mouthwash market research report for comprehensive data and customized insights aligned to specific business objectives.
For detailed analysis of this topic, please visit the official page: Mouthwash Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com