

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Self-Propelled Sprayer Market: The 5.5% CAGR & $312.54M Scale Reshaping Competition

Navigating the Self-Propelled Sprayer Market: Strategic Trends and Commercial Opportunities in a Transforming Agritech Landscape
The self-propelled sprayer market has entered a phase of structural expansion, driven by the intersection of precision agriculture adoption, evolving crop protection requirements, and operational efficiency demands across modern farming systems. Historical trajectory from 2020 through 2025 demonstrates steady revenue growth, with the market reaching a baseline of 215.0 million USD in 2025. Forward projections through 2032 point to a compound annual growth rate of 5.5 percent, positioning the sector to surpass 312.0 million USD by the end of the forecast horizon. This growth trajectory is not merely a function of volume expansion; it reflects a deeper market evolution where capacity optimization, technological differentiation, and regulatory adaptation are reshaping competitive dynamics. For executives, investors, and equipment buyers, the opportunity lies in recognizing how these shifts translate into actionable positioning strategies, portfolio adjustments, and procurement priorities.
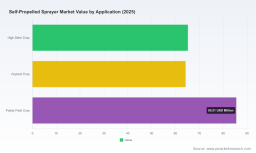
The market’s regional and segment composition underscores a diversified demand base. North America and Asia Pacific currently represent the largest revenue concentrations, followed by Europe, Latin America, and the Middle East and Africa. Across application segments, high stem crops, dryland crops, and paddy field crops each command meaningful share, reflecting the versatility required of modern spraying platforms. By capacity classification, low, medium, and high-capacity units distribute relatively evenly across the market, indicating that demand is fragmented across farm sizes, crop types, and operational intensity rather than dominated by a single machine profile. This fragmentation creates both complexity and opportunity: manufacturers and suppliers must navigate varied performance expectations while buyers benefit from an expanding menu of tailored solutions.
Market concentration remains notable, with the top three players accounting for approximately 55.0 percent of revenue and the top five reaching roughly 65.0 percent. This structure suggests a mature competitive environment where scale, brand trust, and service networks provide meaningful moats. Yet the presence of specialized regional manufacturers and the ongoing integration of precision technologies indicate that competitive advantage is increasingly defined by application intelligence, operator experience, and adaptability to local agronomic conditions rather than mechanical capability alone.
Market Present State and Core Challenges
The self-propelled sprayer sector is operating at a crossroads where demand growth meets structural friction. Several dynamics are shaping how manufacturers, distributors, and end users navigate the current environment.
Operational efficiency and chemical handling requirements are intensifying. Modern spraying platforms must balance high-capacity throughput with precise delivery, drift mitigation, and compatibility across diverse crop protection chemistries. As application windows tighten and field conditions vary, operators increasingly expect machines that reduce rework, optimize coverage, and maintain performance under variable terrain and crop height constraints. This places pressure on engineering teams to integrate advanced boom control, suspension systems, and visibility solutions without compromising payload or field mobility.
Regulatory evolution is reshaping product applicability and consumer expectations. Recent agency actions in the United States have introduced stricter application protections for over-the-top dicamba on tolerant cotton and soybean crops for the upcoming growing seasons, while also advancing new crop protection options and rootstock approvals that alter spray frequency and intensity. Such developments do not reduce demand for self-propelled sprayers outright; rather, they recalibrate how those machines are deployed, where they create value, and which features matter most in specific crop systems. Equipment strategies must account for shifting chemical regimes, residue tolerances, and the growing importance of application accuracy in regulated environments.
Capital cycles and total cost of ownership considerations are also influencing purchasing behavior. As equipment prices reflect broader inflation dynamics, labor constraints, and technology integration costs, operators are weighing upfront investment against long-term efficiency gains. This dynamic favors solutions that deliver measurable reductions in chemical waste, fuel consumption, and downtime, while also creating a premium on demonstrable return on investment. Buyers are increasingly attentive to service availability, parts logistics, and digital support ecosystems, which can determine whether a platform performs as promised over its lifecycle.
Together, these challenges point to a market where performance, compliance, and economics are tightly linked. The firms and buyers that succeed will be those who treat sprayers not as standalone hardware but as components of broader crop protection workflows that must adapt to regulation, chemistry, and field variability.
Key Drivers of Market Change
Multiple forces are converging to shape the next phase of growth. The most consequential can be grouped into technology advancement, regulatory and policy dynamics, demand-side behavior shifts, and supply-side cost and logistics pressures.
Technology Innovation and Breakthroughs
Precision application technology has moved from a differentiator to a baseline expectation. Systems that combine high-clearance architectures, adjustable boom configurations, and intelligent control mechanisms are enabling more consistent delivery across heterogeneous fields. Recent product introductions illustrate this shift. In mid-2025, a leading equipment manufacturer launched a new self-propelled sprayer series featuring a front-cab design, an advanced control lever, and a next-generation monitoring platform intended to improve operator comfort and spraying precision. By early 2026, live field demonstrations highlighted the integration of selective application capabilities with high-clearance platforms, emphasizing how operational visibility and targeted delivery can reduce overlap and improve coverage consistency. These developments signal that competitive advantage now hinges on the integration of mechanical design with digital control, operator ergonomics, and application intelligence.
Policy and Regulatory Environment
Regulatory activity is actively reshaping crop protection strategies and, by extension, equipment utilization patterns. In recent months, regulatory bodies have reinforced protections for specific over-the-top herbicide applications, approved new citrus rootstock that can help trees resist greening disease and reduce reliance on conventional sprays, and proposed registrations for new herbicide active ingredients with defined residue tolerances across multiple crops. These actions create a dual effect. First, they can alter the volume and timing of applications in certain regions and crop systems, influencing where and when sprayers deliver the most value. Second, they elevate the importance of precise, repeatable application to meet compliance expectations and minimize off-target movement. Equipment portfolios that support variable rate application, drift management, and documentation-ready operation are better positioned to align with these evolving requirements.
Demand-Side Shifts in Grower and Commercial Behavior
Farm operators and commercial applicators are increasingly prioritizing workflow efficiency and input stewardship. Labor availability, scheduling pressure, and the cost of crop protection inputs are pushing buyers toward platforms that can cover more area with fewer passes, maintain boom stability in challenging conditions, and support multiple product types where applicable. At the same time, the adoption of agronomic data tools is creating richer feedback loops between application performance and field outcomes. As a result, sprayers are being evaluated not only for mechanical robustness but also for their ability to integrate with farm management workflows, reduce variability, and support informed decision-making across seasons.
Supply Chain and Cost Structure Dynamics
Component availability, manufacturing scale, and service network reach continue to influence competitive positioning. High-capacity platforms and specialized boom systems require coordinated sourcing of chassis components, hydraulic systems, control electronics, and spraying hardware. Firms that have invested in disciplined manufacturing processes, localized service capacity, and flexible configurations are better equipped to manage cost volatility while maintaining delivery reliability. For buyers, this translates into a growing emphasis on supplier resilience, parts availability, and the predictability of maintenance intervals. In a market where uptime directly affects crop protection timing, service infrastructure has become a strategic variable rather than a secondary consideration.
Competitive Landscape and Leading Strategies
The competitive field combines global equipment leaders, regionally focused manufacturers, and specialists with strong footholds in specific crop systems or operating conditions. The top three players hold a combined revenue share near 55.0 percent, and the top five reach approximately 65.0 percent, reflecting a landscape where scale, brand recognition, and service coverage provide substantial advantages. However, differentiation is increasingly achieved through product architecture, application technology, and regional adaptation rather than mechanical capability alone.
Strategic Positioning and Differentiation
Large multinational manufacturers are leveraging integrated precision platforms and broad service networks to reinforce their position. One global leader has emphasized AI-informed application optimization, hydrostatic drive systems, and a portfolio spanning multiple series tailored to different operational scales. Another major player has focused on multi-system application flexibility, adjustable rear boom configurations, and two-height clearance options that broaden usability across crop types. A third has pursued automation and autonomy-oriented solutions within established sprayer lines, aiming to extend precise crop protection into more controlled and repeatable workflows.
Alongside these global players, specialized manufacturers are competing on targeted strengths. Some have built reputations around high-clearance mechanical drive designs optimized for efficiency and field access. Others have focused on robust chassis, advanced boom folding, and variable rate capabilities suited to diverse field conditions. Regional specialists in Brazil, Australia, Poland, and parts of Europe have developed platforms tailored to tropical, row-crop, and local agronomic requirements, including drift reduction features, high-capacity tanks, and solution systems adapted to specific environmental constraints. This diversity allows buyers to select platforms that align closely with local crop systems, topography, and operational scale.
Market Evolution: Integration, Differentiation, and New Entrants
The landscape is evolving along several axes. Integration is visible in partnerships and demo events that bring together complementary technologies, such as high-clearance platforms combined with selective application tools and next-generation monitoring systems. These collaborations highlight a trend toward interoperable solutions where the value of a sprayer is enhanced by its compatibility with precision application modules and operator support interfaces. Differentiation remains strong in areas such as boom design, clearance height, control architecture, and regional adaptability, allowing firms to defend niches even in a concentrated market. At the same time, the breadth of active manufacturers across North America, Europe, South America, and Australia suggests that new entrants and regional specialists continue to find room by addressing specific operational pain points, price points, or crop system requirements.
For executives and investors, the key insight is that market leadership will be determined less by headline capacity alone and more by the ability to deliver repeatable precision, operator-friendly controls, and dependable support in the field. Brands that can translate technology into measurable operational outcomes are best positioned to capture share as procurement criteria become more performance- and compliance-oriented.
Future Trends Over the Next Three to Five Years
Looking ahead, several trends are likely to define the market’s trajectory and create vector opportunities for different stakeholders.
Precision Application as a Standard, Not a Premium
Selective application tools, advanced boom control, and operator-centric monitoring will increasingly become part of mainstream offerings rather than niche upgrades. As these capabilities diffuse across product lines, competitive differentiation will shift toward integration quality, ease of use, and the reliability of performance under real field conditions. Equipment strategies that treat precision as a core design principle rather than an add-on will be better positioned to meet evolving buyer expectations and align with compliance-driven application practices.
Worldwide Electrical Orchard Sprayer Market
Crop-System Specificization and Regional Adaptation
Demand will continue to diverge by crop type, field condition, and local regulation. High stem crops, dryland crops, and paddy field crops each place distinct requirements on clearance, boom configuration, and delivery consistency. Manufacturers that invest in configurable platforms and region-aware product planning can capture value by matching machine characteristics to specific agronomic needs. For buyers, this trend reinforces the importance of evaluating sprayers against actual field profiles and chemical regimes rather than relying solely on generalized specifications.
Service Ecosystems and Digital Support as Competitive Factors
As equipment becomes more connected and application workflows more data-rich, the quality of service infrastructure and digital support will play a larger role in purchasing decisions and long-term satisfaction. Predictive maintenance guidance, remote diagnostics, parts availability, and operator training will increasingly influence total cost of ownership. Firms that build robust support networks and enable smoother adoption of advanced features can strengthen retention and brand preference, while buyers benefit from reduced downtime and more predictable operating costs.
Risks and Uncertainties
Several variables could alter the pace or shape of growth. Regulatory actions may change application frequencies or reduce reliance on certain chemical regimes in specific crops, affecting near-term demand patterns. Economic pressures on farm income and equipment financing can influence purchase timing and the willingness to invest in higher-capacity or technology-rich platforms. Supply chain disruptions or component shortages may affect delivery schedules and service responsiveness, particularly for manufacturers with concentrated sourcing or limited regional support. Finally, the pace of precision technology adoption may vary across regions and farm sizes, creating uneven demand intensity and requiring differentiated go-to-market approaches.
Self-propelled Forage Harvesters Market
Strategic Recommendations for Decision Makers
Different stakeholders face distinct priorities in this environment, but all can benefit from a disciplined focus on application fit, operational economics, and support reliability.
For Manufacturers and Product Leaders
Align product roadmaps with real-world application workflows rather than isolated technical milestones. Prioritize configurations that support variable rate application, drift management, and operator ergonomics, and ensure that precision features are integrated in ways that are intuitive and dependable under field conditions. Invest in regional adaptation and service capacity, as localized support increasingly influences purchase decisions and long-term brand preference. Where possible, use live demonstrations and field-based validation to show measurable improvements in coverage consistency, overlap reduction, and operator efficiency.
For Investors and Strategic Planners
Focus on companies that demonstrate a credible path to integrating precision technologies with mechanical platforms, while also maintaining disciplined manufacturing and service execution. The market’s moderate growth rate and concentrated structure suggest that value creation will come from share gains driven by differentiation and reliability rather than from broad volume surges alone. Evaluate exposure to regulatory and crop-system shifts, and consider how product portfolios are positioned across capacity classes and regions. Diversification into adaptable platforms and strong regional relevance can reduce sensitivity to single-market or single-crop volatility.
For Procurement Teams and Buying Organizations
Evaluate sprayers against actual field profiles, crop protection requirements, and support availability rather than relying on generic capacity benchmarks. Give weight to boom stability, clearance flexibility, control usability, and the strength of the manufacturer’s service network in your operating geography. Where possible, validate performance through demonstrations or reference operations that resemble your conditions. Consider total cost of ownership holistically, including downtime risk, parts availability, and the ease of integrating precision features into existing workflows.
The self-propelled sprayer market is evolving into a more performance-defined, compliance-aware, and regionally nuanced environment. Success will belong to organizations that connect equipment decisions to agronomic realities, operational economics, and support reliability, while staying alert to regulatory and technology shifts that reshape application workflows.
PW Consulting
For a more detailed view of segment sizes, regional dynamics, capacity-class comparisons, application-specific demand patterns, and company-level positioning beyond the themes outlined here, a comprehensive market research report can provide the granular data and customized analysis needed for precise planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Self-Propelled Sprayer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com