

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Endoscopic Cold Light Source Market: Beyond the 5.5% CAGR Trajectory

Strategic Horizons: Navigating Growth and Innovation in the Endoscopic Cold Light Source Market
The endoscopic cold light source market represents a critical, yet often underappreciated, layer of the modern surgical ecosystem. While the spotlight frequently falls on cameras, processors, and robotic interfaces, the illumination backbone determines the quality, safety, and longevity of every minimally invasive procedure. As healthcare systems worldwide pivot toward outpatient settings and higher-resolution imaging standards, the demand for reliable, energy-efficient, and technically compatible lighting solutions has entered a new growth paradigm. This analysis examines the structural forces reshaping the market, the competitive maneuvers defining the landscape, and the strategic opportunities emerging for stakeholders positioned to act decisively.
Rigid Endoscopes Market
Market Overview: Resilience Amid Evolving Capital and Procedural Dynamics
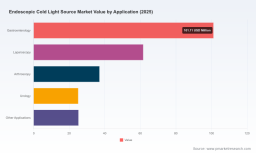
The global market for endoscopic cold light sources reached a baseline valuation of 250.0 million USD in 2025, following a steady compound annual growth trajectory of 5.5 percent across the historical review period from 2020 through 2025. The expansion from 191.28 million USD in 2020 to the 2025 baseline reflects more than incremental demand; it signals a structural shift in how healthcare providers evaluate procedural illumination. Forecasts extending through 2032 project the market advancing to 363.67 million USD, with the 2026 to 2032 forecast window sustaining the same mid-single-digit growth cadence. This trajectory is neither explosive nor stagnant, but rather characteristic of a mature medical device segment undergoing technological maturation and geographic diffusion.
Three structural dynamics warrant immediate attention. First, the transition from conventional xenon architectures to light-emitting diode platforms has fundamentally altered total cost of ownership calculations, shifting capital expenditure debates toward operating efficiency and lifecycle reliability. Second, regulatory frameworks are increasingly treating illumination as an integrated component of the endoscopic system rather than a standalone accessory, reshaping compliance pathways and procurement specifications. Third, the geographic distribution of procedural volume is rebalancing, with mature markets stabilizing demand for premium replacements while emerging regions accelerate adoption through infrastructure investment and training programs. These intersecting forces create a landscape where volume growth alone no longer guarantees competitive advantage; differentiation now hinges on compatibility, serviceability, and alignment with broader visualization roadmaps.
Core Growth Drivers: Technology, Policy, Demand, and Supply Chain Realignment
Several interconnected drivers are compounding to shape the next phase of market development. Understanding how these factors interact is essential for evaluating where value will accrue and which strategic bets will withstand regulatory and economic cycles.
Technological Innovation and the LED Architecture Shift
The migration toward LED-based cold light sources continues to redefine performance expectations. Compared with traditional xenon systems, LED architectures deliver extended operational lifespans, reduced thermal output, and more consistent photometric output across the spectral bands required for white light, near-infrared, and fluorescence imaging. Recent product launches have underscored this trajectory. In September 2025, Karl Storz SE & Co. KG introduced the POWER LED Rubina as a laser-free cold light source engineered for white light and near-infrared/indocyanine green applications, while simultaneously rolling out POWER LED 300 and POWER LED Saphira platforms designed to support white light, near-infrared/indocyanine green, and narrow-spectrum imaging modes. These releases reflect a broader industry emphasis on modular illumination that can interface cleanly with advanced visualization pipelines rather than simply maximizing raw luminous intensity.
The implication for manufacturers is clear: illumination is no longer a commodity input but a configurable element of the imaging chain. Designers who anticipate spectral compatibility requirements, integrate intelligent scope-sensing safeguards, and engineer for simplified service workflows are positioning their products as multipliers of downstream system performance. In parallel, the elimination of recurring bulb replacement costs improves the economics of ownership for high-utilization surgical suites, a factor that procurement committees increasingly weigh against upfront unit price.
Regulatory Evolution and System-Level Compliance
Regulatory expectations are tightening around illumination as a formally recognized subsystem within endoscopic assemblies. Recent clearance activity indicates that compatibility verification is becoming an explicit condition of market access for higher-resolution and fluorescence-enabled camera platforms. For example, recent regulatory summaries note that certain FDA 510(k) clearances for endoscopic camera systems incorporate compatible cold light sources within 4K ultra-high-definition and fluorescence configurations, signaling that illumination interoperability is now part of the submission narrative. On the European side, CE marking pathways for endoscopic systems have increasingly required verified cold light source compatibility under medical device directives, reinforcing the expectation that illumination components meet defined performance and safety criteria before integration.
PW Consulting
For commercial teams, this environment raises the importance of documentation rigor, interoperability testing, and lifecycle support. Products that can demonstrate validated compatibility with recognized visualization platforms gain a smoother path to adoption, while isolated illumination offerings face greater friction in system-centric procurement processes. The regulatory shift also elevates the strategic value of maintaining clear change-control protocols, because even minor photometric or connectivity modifications can trigger re-validation cycles in system-integration contexts.
Demand-Side Shifts: Outpatient Migration and Procedure Volume Rebalancing
Demand patterns are increasingly shaped by the relocation of endoscopic procedures from inpatient theaters to ambulatory and office-based settings. This migration compresses scheduling windows, increases asset utilization rates, and elevates expectations for rapid setup, reliable illumination, and minimal maintenance interruption. Simultaneously, reimbursement adjustments have expanded support for outpatient endoscopic procedures, reinforcing volume growth in environments where equipment turnover, ease of use, and uptime directly influence departmental throughput.
Procurement behavior is adapting accordingly. Decision-makers are weighing illumination platforms not only on image quality, but also on integration with existing scope inventories, compatibility with multi-specialty workflows, and the ability to reduce consumables-related downtime. In orthopedics, sports medicine, gastroenterology, and urology, the breadth of compatible applications is becoming a differentiator, particularly in facilities that consolidate multiple service lines around a shared procedural infrastructure. The practical outcome is a preference for illumination solutions that support flexible deployment rather than single-specialty optimization.
Worldwide Ultra HD Endoscope Market
Cost Structure and Supply Chain Considerations
Beyond clinical drivers, cost structure dynamics are reshaping competitive positioning. LED cold light sources reduce the recurring cost burden associated with bulb replacement while preserving fiber-optic transmission for consistent endoscopic illumination, a combination that strengthens the economic case for adoption in high-case-volume environments. At the same time, manufacturers are navigating component availability, semiconductor supply variability, and the logistics of regulated component sourcing. Firms that have invested in resilient bill-of-materials strategies, broader supplier qualification, and service inventory planning are better equipped to sustain delivery consistency, which in turn protects contractual commitments and downstream customer confidence.
The interaction between hardware cost profile and service economics is particularly important. As procurement teams increasingly evaluate total lifecycle cost rather than point-of-sale price, illumination providers that bundle predictable maintenance pathways, extended operational life, and clear compatibility documentation can convert technical strength into commercial resilience.
Competitive Landscape: Positioning, Differentiation, and the Evolution of the Field
The market remains moderately fragmented at the top. The three largest participants account for approximately 22.5 percent of total revenue, while the top five collectively represent about 28.5 percent. This concentration pattern indicates that scale advantages exist, but leadership is not yet locked into a handful of dominant incumbents. Instead, competitive advantage is being built through portfolio breadth, system compatibility, and the ability to align illumination roadmaps with broader visualization and surgical workflow strategies.
Karl Storz SE & Co. KG, headquartered in Tuttlingen, Germany, illustrates a systems-integration approach. Its recent portfolio activity highlights laser-free cold light sources engineered for white light and near-infrared/indocyanine green applications, alongside platforms designed for narrow-spectrum and advanced imaging modes. With LED lifespans extending beyond 30,000 hours, the company is reinforcing a value proposition centered on longevity, spectral flexibility, and compatibility with specialized imaging modalities. The strategic signal is that illumination can function as a precision enabler within a broader endoscopy ecosystem rather than as a discrete accessory.
Olympus Corporation, based in Tokyo, Japan, emphasizes integrated illumination within procedural and office endoscopy workflows, pairing LED light sources with video processing architectures and narrow-band imaging technology. Its positioning leans toward workflow continuity and diagnostic imaging continuity, appealing to environments where visualization consistency across cases and sites is paramount. Stryker Corporation, in Kalamazoo, Michigan, has focused on real-time visibility features, including auto-light behavior and scope-sensing safety mechanisms that reduce user burden and mitigate illumination-related procedural risks. These safety and automation features align with Stryker’s broader emphasis on intelligent surgical technology, making illumination part of a risk-managed operational narrative.
Other participants are carving out specialty- and region-specific relevance. Richard Wolf GmbH supplies cold light sources and LED illumination solutions across multiple endoscopic and surgical specialties, reinforcing breadth as a competitive lever. ConMed Corporation targets laparoscopic and endoscopic illumination for minimally invasive surgery, aligning its offerings with procedural workflows that demand dependable, compact illumination. B. Braun Melsungen AG integrates LED cold light sources with surgical visualization systems, emphasizing the linkage between illumination and the broader operative environment. Medtronic plc incorporates LED illumination within gastrointestinal and surgical endoscopy portfolios, leveraging cross-portfolio scale and clinical commercialization infrastructure. Smith & Nephew plc serves arthroscopy and sports medicine contexts, where portability, durability, and specialty-specific compatibility are critical. Fujifilm Holdings Corporation delivers LED cold light sources oriented toward high-resolution endoscopic imaging and surgical visualization, reinforcing the connection between illumination quality and diagnostic clarity.
The competitive field is evolving along several axes. Consolidation around integrated visualization platforms is increasing the value of compatible illumination, while differentiation is shifting from lamp intensity to spectral precision, interoperability, and service reliability. New entrants are less likely to succeed through generic luminance claims and more likely to gain traction by offering niche compatibility, cost-transparent ownership models, or region-specific deployment capabilities. The practical dynamic is a landscape where partnerships, ecosystem alignment, and validated integration matter as much as standalone product performance.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
Extrapolating from current developments and market structure, three trends are likely to define the strategic environment through the end of the decade.
Trend 1: Illumination as an Integrated, Compatibility-Gated Component
The trajectory of regulatory and procurement behavior suggests that illumination will be evaluated increasingly as a validated subsystem within endoscopic assemblies. As ultra-high-definition imaging and fluorescence workflows expand, compatibility verification will become a routine part of procurement specifications and clinical adoption. This trend creates opportunities for manufacturers that invest early in interoperability testing, documentation, and integration planning, while raising barriers for products that rely on loose accessory positioning. For investors and strategic planners, the implication is that value capture will increasingly accrue to providers who can demonstrate reliable fit within established visualization ecosystems.
Trend 2: LED Lifecycle Economics Reshaping Procurement Priorities
As LED architectures continue to displace legacy bulb-based approaches, total cost of ownership will become a more decisive procurement criterion. Reduced consumables replacement, extended service life, and more predictable maintenance scheduling strengthen the business case for LED illumination in high-utilization surgical environments. This shift favors manufacturers who can articulate lifecycle value clearly and support it with service logistics, extended warranties, and predictable performance data. It also raises the stakes for incumbents with legacy replacement models, particularly in markets where departmental budgets are scrutinized for recurring operational costs.
Trend 3: Procedural Migration and Multi-Specialty Deployment Pressure
The ongoing relocation of endoscopic procedures to outpatient and office-based settings, combined with reimbursement support for ambulatory volume, will increase demand for illumination solutions that can be deployed rapidly, maintained efficiently, and adapted across specialties. Facilities that consolidate gastroenterology, urology, laparoscopy, arthroscopy, and other service lines around shared infrastructure will favor flexible platforms over highly specialized single-use configurations. The commercial opportunity lies in designing for cross-specialty compatibility, streamlined setup, and service continuity, while the risk lies in over-specialization that limits deployment scalability.
Actionable Guidance for Decision Makers
The strategic implications vary by role, but the underlying requirement is shared: illumination decisions are becoming part of broader system, workflow, and cost planning rather than isolated equipment purchases.
For Manufacturers and Product Strategists
Align illumination roadmaps with system compatibility and spectral requirements rather than treating illumination as a standalone feature race. Prioritize interoperability validation, serviceability, and lifecycle economics in product messaging, because these attributes increasingly determine adoption speed in system-centric procurement environments. Invest in documentation and change-control discipline to protect compatibility certifications as imaging platforms evolve, and evaluate whether product lines are structured to support multi-specialty deployment or whether portfolio fragmentation is limiting scalability.
For Investors and Corporate Development Teams
Look beyond headline growth rates and assess exposure to integration-driven value creation. Companies with validated compatibility narratives, LED lifecycle economics, and service infrastructure that supports uptime are better positioned to capture share in system-integration-heavy procurement cycles. Monitor how regulatory and reimbursement shifts alter volume patterns across outpatient and ambulatory settings, since those shifts influence both demand timing and the relative attractiveness of different illumination architectures. In due diligence, treat compatibility documentation, service network coverage, and bill-of-materials resilience as material indicators of commercial durability.
For Procurement and Clinical Operations Leaders
Structure evaluation criteria around total lifecycle impact rather than initial unit price. Compatibility with existing scope inventories, support for multi-specialty workflows, and the ability to reduce consumables-related downtime are increasingly relevant to departmental throughput and total cost outcomes. Where possible, test illumination integration within representative procedural workflows before committing, because lighting performance in isolation does not fully predict operational fit within endoscopy and surgical ecosystems. Align procurement planning with anticipated outpatient volume growth, since infrastructure readiness can influence how smoothly expanded procedural activity is absorbed.
Conclusion
The endoscopic cold light source market is entering a phase where technological maturity, regulatory integration, and procedural migration intersect to reshape value creation. Growth is steady rather than disruptive, but the drivers behind that growth are changing how illumination is specified, purchased, and integrated. LED lifecycle economics, compatibility gating within endoscopic systems, and the expansion of outpatient procedural volume are jointly raising the bar for product differentiation and commercial execution. Organizations that treat illumination as a strategic element of the visualization chain—rather than a peripheral accessory—will be better positioned to capture the next phase of demand while managing the operational risks inherent in evolving regulatory and reimbursement environments. For decision makers seeking deeper segmentation detail, regional trajectory breakdowns, and tailored scenario planning, complete market research reports provide the granularity required to translate these directional insights into concrete commercial action.
For detailed analysis of this topic, please visit the official page: Endoscopic Cold Light Source Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com