

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PSIM Market: Why 16.3% CAGR and Cloud Shift Redefine Security Strategies

Physical Security Information Management (PSIM) Market: Strategic Trends and Commercial Opportunities
The global Physical Security Information Management (PSIM) market has entered a phase of accelerated expansion, driven by the convergence of physical security infrastructure, digital transformation, and escalating threat landscapes. Valued at approximately $1,257.0 million in 2025, the market is projected to reach $3,619.43 million by 2032, reflecting a compound annual growth rate of 16.3% over the forecast period. This trajectory underscores a structural shift from fragmented, device-centric security operations toward unified, data-driven security management platforms. For enterprise decision-makers, investors, and technology providers, the PSIM landscape presents a compelling mix of scaling demand, evolving competitive dynamics, and emerging commercial vectors that warrant strategic attention.
Market Landscape and Core Challenges
PSIM platforms serve as centralized orchestration layers that aggregate video surveillance, access control, intrusion detection, alarm management, and incident response workflows into cohesive operational dashboards. The market's expansion from roughly $775.19 million in 2020 to its current scale reflects sustained adoption across critical infrastructure, enterprise campuses, logistics hubs, and public sector facilities. Growth has been broad-based, with mature deployments in North America and Europe establishing foundational architectures, while Asia Pacific and emerging regions accelerate adoption as digital security standards mature and urban infrastructure investments increase. Software components continue to represent the dominant revenue share, reflecting the platform-centric nature of modern deployments, while services remain essential for integration, customization, and ongoing operational support.
Despite robust growth, the PSIM market confronts several structural challenges that will shape competitive outcomes over the next several years.
Hardware Security Modules (HSM) Market
Integration Complexity and Legacy Infrastructure
Many enterprise and public sector facilities operate heterogeneous security ecosystems accumulated over decades. Bridging legacy analog or proprietary digital systems with modern IP-based PSIM platforms requires extensive integration work, customized middleware, and phased migration strategies. The complexity of unifying disparate protocols, data formats, and vendor interfaces often extends deployment timelines and increases total cost of ownership, creating friction for organizations seeking rapid modernization.
Data Governance, Sovereignty, and Compliance Burden
PSIM platforms aggregate sensitive operational data, including video feeds, access logs, incident records, and location telemetry. Regulatory frameworks increasingly mandate strict data handling, storage localization, and cybersecurity certification standards. In European markets, compliance requirements around data sovereignty and operational technology security directly influence architecture choices, vendor selection, and cross-border deployment models. Organizations must balance centralized management efficiency with localized data processing obligations, adding architectural complexity to platform design and procurement decisions.
On-Premises Inertia Versus Cloud Transition Economics
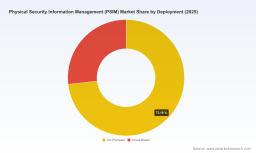
On-premises deployments continue to command a substantial share of the market, reinforced by higher initial hardware and integration investments, perceived control over sensitive security data, and institutional familiarity with localized architectures. While cloud-based PSIM offerings offer scalability, remote management, and reduced infrastructure overhead, the transition requires organizations to reassess capital expenditure patterns, network reliability assumptions, and internal security operations capabilities. The economic and operational tradeoffs between deployment models remain a central decision variable for procurement teams.
Key Drivers Shaping Market Evolution
The PSIM market's growth trajectory is not merely a function of incremental security spending. It is being reshaped by converging technological, regulatory, and operational forces that alter how organizations design, procure, and operate security management environments.
AI-Enabled Analytics and Event Orchestration
Artificial intelligence has moved from experimental feature sets to core operational capabilities within PSIM platforms. Intelligent video analytics, behavioral anomaly detection, automated license plate recognition, and correlation engines now enable security teams to filter noise, prioritize alerts, and coordinate responses with greater precision. The shift toward AI-augmented event orchestration reduces reliance on manual monitoring and allows centralized security operations to manage larger asset footprints with fewer incremental staffing requirements. Recent product movements reflect this emphasis: major vendors have released cloud-based PSIM solutions that extend remote management capabilities while reducing on-premises infrastructure dependencies, and industry reports highlight accelerating AI adoption alongside hybrid-cloud deployment models. These developments signal a market where analytics depth and automation maturity are becoming key differentiators rather than peripheral enhancements.
Regulatory Mandates and Critical Infrastructure Protection
Policy environments are increasingly shaping PSIM adoption patterns. Regulatory initiatives targeting critical infrastructure cybersecurity certification, operational technology security compliance, and unified incident orchestration requirements are compelling organizations in industrial, government, and public service sectors to adopt centralized management platforms that satisfy auditability, logging, and response coordination standards. Directives such as NIS2 compliance requirements for operational technology environments directly influence deployment architectures and centralized incident orchestration in industrial and government sectors. Simultaneously, data protection regulations continue to drive sovereignty considerations for storage and processing in European deployments. For vendors, regulatory alignment is becoming a procurement prerequisite; for buyers, compliance-driven standardization creates both deployment mandates and opportunities to consolidate fragmented security stacks under unified platforms.
Operational Efficiency Demands and Security Operations Centralization
Organizations are increasingly treating physical security as an operational efficiency challenge rather than a standalone compliance function. Distributed facilities, expanding logistics networks, and hybrid work environments have stretched traditional security monitoring models. Centralized PSIM platforms enable security operations centers to monitor multiple sites, correlate events across systems, and standardize response protocols without proportionally scaling headcount. The integration of external data sources, such as real-time gunshot detection alerts into unified incident response workflows, illustrates how PSIM platforms are evolving into broader situational awareness and response orchestration tools. This expansion broadens the addressable use case beyond traditional access control and video monitoring into integrated public safety and enterprise resilience applications.
Deployment Model Economics and Infrastructure Cost Realignment
Cost structures across the PSIM value chain are shifting as cloud architectures mature and integration practices standardize. While on-premises installations remain dominant due to established procurement patterns and higher initial hardware and integration costs relative to cloud alternatives, cloud-based models are gaining traction where organizations prioritize remote management, elastic scaling, and reduced facility infrastructure requirements. At the hardware layer, specialized components such as fiber-optic sensors and thermal camera calibration modules require frequent firmware updates and specialized maintenance, reinforcing the importance of vendor support ecosystems and lifecycle management capabilities. These cost dynamics encourage buyers to evaluate total lifecycle economics rather than upfront acquisition expenses, gradually reweighting procurement decisions toward platforms that offer predictable operating costs and scalable service engagement models.
Competitive Landscape and Strategic Positioning
The PSIM market remains moderately concentrated, with leading vendors commanding a combined share that leaves substantial room for specialized providers, regional players, and integration-focused partners. Competitive differentiation is increasingly defined by platform openness, analytics depth, deployment flexibility, ecosystem partnerships, and the ability to satisfy regulatory and operational requirements across diverse customer segments.
Vendor Strategic Profiles
Several established players illustrate the range of competitive approaches shaping the market.
- Genetec Inc. has positioned its unified security software platform around IP-based video surveillance, access control, and automatic license plate recognition, emphasizing an integrated architecture that spans multiple security domains. Its recent product and research activities highlight a focus on AI adoption trends and hybrid-cloud deployment models, alongside the introduction of cloud-based PSIM capabilities designed to support remote security management and reduce on-premises infrastructure dependencies.
- Honeywell International Inc. offers an integrated platform combining access control, video surveillance, intrusion detection, and related systems under a maximum security PSIM framework. Its recent collaboration with Rhombus to deliver integrated cloud access control and video management through channel partners reflects a strategy that blends established enterprise relationships with cloud-native access control ecosystems.
- NICE Systems Ltd. emphasizes unified security management and event orchestration within its PSIM platform, targeting environments where centralized incident coordination and workflow automation are priorities.
- Milestone Systems A/S has built its market presence on an open video management system platform that supports centralized management and analytics, appealing to organizations that prioritize interoperability and flexible integration across third-party devices and applications.
- AxxonSoft Inc. focuses on a distributed PSIM software platform with intelligent video analytics, IP connectivity, and event-driven automation, catering to deployments that require scalable event processing across geographically dispersed assets.
- Advancis Software & Services GmbH has advanced its vendor-neutral PSIM software with enhanced identity management capabilities, reinforcing a strategy centered on security and building management integration without vendor lock-in.
- videoNEXT Federal, Inc. serves federal and enterprise physical security integration requirements, reflecting a specialized focus on public sector and large-scale enterprise deployment contexts.
- SureView Systems positions its open response PSIM platform around unified security operations and law enforcement integration, and its integration with gunshot detection technology demonstrates a push toward real-time incident alerting and coordinated response workflows.
- Prysm Software emphasizes video analytics and security event management within its PSIM offering, targeting environments where analytic-driven alerting and event correlation are central to operational value.
Market Structure Trends: Consolidation, Specialization, and Ecosystem Plays
The competitive landscape is evolving along multiple axes. Large diversified security and technology firms continue to leverage cross-selling opportunities, channel networks, and existing customer relationships to expand PSIM adoption within broader security portfolios. At the same time, specialized PSIM vendors compete on platform openness, analytic sophistication, response orchestration capabilities, and domain-specific integrations that address niche operational requirements. Partnerships and integrations are increasingly central to market positioning, as vendors extend ecosystems through cloud access control alliances, third-party sensor integrations, and public safety data linkages. This dynamic suggests a market that will continue to support both platform-centric incumbents and focused specialists, with differentiation shifting toward ecosystem reach, deployment flexibility, and the ability to translate heterogeneous data into actionable operational workflows.
Future Trends and Commercial Implications
Looking ahead across the next three to five years, several interrelated trends are likely to define PSIM market evolution and shape where commercial value is created.
Hybrid and Cloud-First Architecture Adoption Will Accelerate
As cloud-based PSIM capabilities mature and organizations gain confidence in remote management, centralized monitoring, and elastic scaling, hybrid and cloud-first deployment models are expected to capture increasing share. The transition will not eliminate on-premises architectures, particularly in environments with stringent data sovereignty requirements or specialized hardware dependencies, but it will shift a growing portion of new deployments and refresh cycles toward models that reduce facility infrastructure burdens and enable centralized administration across distributed sites. Commercial opportunities will emerge for vendors that can offer flexible migration pathways, predictable operating economics, and strong integration support during transition periods.
Security Control Room Market
AI-Driven Automation and Situational Awareness Will Redefine Operational Value
AI-enabled analytics, automated event correlation, and response orchestration will continue to move from optional enhancements to core expectations. As platforms incorporate more sophisticated detection, filtering, and workflow automation, the value proposition of PSIM will increasingly rest on reducing response latency, improving operator efficiency, and enabling smaller security teams to manage larger, more complex environments. Opportunities will extend beyond traditional security operations into broader resilience use cases, including coordinated incident response, public safety integration, and cross-system situational awareness. Vendors and service providers that can demonstrably reduce operational overhead while improving incident handling will be best positioned to capture premium positioning.
Regulatory Alignment and Compliance-Driven Procurement Will Shape Market Access
As cybersecurity certification requirements, operational technology compliance mandates, and data sovereignty expectations become more entrenched, regulatory alignment will increasingly influence procurement decisions and deployment architectures. Public sector, critical infrastructure, and industrial buyers are likely to prioritize platforms that can demonstrate compliance readiness, auditable logging, and configurable data handling. This trend creates both a barrier and an opportunity: vendors that proactively align with evolving standards and offer transparent compliance capabilities will gain preferential access to regulated segments, while buyers that standardize on compliant platforms can reduce audit exposure and streamline multi-site governance.
Potential Risks and Uncertainties
Several factors warrant caution. Rapid AI adoption introduces questions around false-positive rates, analytic reliability, and the operational consequences of over-automation in high-stakes environments. Cloud transition paths may encounter network dependency assumptions, latency sensitivities, and internal capability gaps that slow adoption in certain segments. Regulatory landscapes will continue to evolve, and divergent requirements across jurisdictions can complicate global platform standardization. Additionally, specialized hardware components and maintenance dependencies can create lifecycle cost uncertainties if firmware update cadence, calibration requirements, or vendor support models are not carefully managed. Decision-makers should treat these variables as design constraints rather than fixed assumptions.
Strategic Guidance for Decision-Makers
The PSIM market's growth and structural evolution create distinct imperatives depending on an organization's role in the value chain.
For Security Technology Manufacturers and Platform Providers
Differentiate through ecosystem openness, analytics depth, and deployment flexibility rather than feature count alone. Investments in interoperable architectures, AI-driven event orchestration, and cloud-native management capabilities will likely determine competitive relevance as buyers evaluate total lifecycle economics and operational outcomes. Strengthening compliance alignment and transparent data handling capabilities will expand addressable segments in regulated markets. Partnerships that extend platform reach into access control, public safety data, and specialized sensor ecosystems can accelerate adoption and create sticky integration relationships.
For Investors and Strategic Capital Allocators
Focus on companies that combine scalable platform economics with clear operational value propositions in centralized security management and incident orchestration. The market's growth trajectory favors providers that can support hybrid deployment models, reduce integration friction, and demonstrate measurable operational efficiency gains. Evaluate exposure to regulated sectors carefully, as compliance-aligned offerings may command stronger positioning but also face higher verification and documentation burdens. Monitor consolidation patterns, partnership ecosystems, and cloud migration adoption as indicators of where market share and margin potential are likely to concentrate.
PW Consulting
For Enterprise and Public Sector Procurement Leaders
Evaluate PSIM investments through a total lifecycle and operational outcome lens rather than upfront hardware cost alone. Prioritize platforms that can unify heterogeneous security systems, support phased migration from legacy architectures, and provide configurable compliance capabilities aligned with jurisdictional requirements. Consider deployment model tradeoffs in the context of network reliability, internal operations capabilities, and long-term scaling needs. Request demonstrable evidence of analytic reliability, integration breadth, and response orchestration workflows during evaluation, and structure vendor engagements to include clear support, firmware lifecycle, and maintenance commitments.
For organizations seeking deeper segmentation data, deployment-model economics, regional demand dynamics, and customized strategic recommendations, the full PW Consulting research report provides expanded analysis and detailed market breakdowns tailored to specific decision contexts.
For detailed analysis of this topic, please visit the official page: Physical Security Information Management (PSIM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com