

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
SAP Market 2026–2032: Why a 6.8% CAGR and Personal Hygiene Demand Redefine Growth Trajectories

Navigating the Super Absorbent Polymer Market: Strategic Trends and Commercial Opportunities
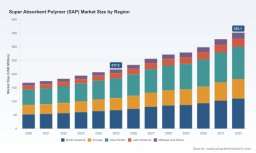
The super absorbent polymer (SAP) market has entered a decisive growth phase, transforming from a mature hygiene enabler into a strategically contested arena shaped by sustainability mandates, supply chain localization, and application diversification. Over the historical period from 2020 to 2025, global revenue progressed from approximately 168.5 million to 217.2 million, reflecting steady industrial adoption and shifting consumer expectations. The trajectory extends into the forecast window through 2032, with market value projected to reach 352.1 million. This expansion corresponds to a compound annual growth rate of 6.8 percent, signaling that the sector will not merely grow but will continuously reconfigure around new performance benchmarks, regulatory pressures, and competitive positioning. For executives and investors, the implication is clear: SAP is no longer a commodity input defined solely by absorption capacity. It is becoming a value-differentiated material where carbon intensity, circularity, regional supply security, and application-specific formulation expertise determine long-term profitability.
The market’s evolution is shaped by structural forces that demand strategic recalibration. First, the industry is witnessing a pronounced shift from volume-driven competition to sustainability-led differentiation. Traditional price and capacity battles remain relevant, yet procurement specifications increasingly incorporate product carbon footprint, renewable energy usage, and end-of-life considerations. Second, regional capacity expansion is rebalancing global supply chains. Producers are locating manufacturing closer to end-user clusters to reduce logistics exposure, respond faster to localized demand surges, and mitigate freight volatility. Third, application diversification is stretching SAP beyond its historical core. While personal hygiene remains the dominant demand center, agriculture, medical devices, and industrial moisture management are creating new performance requirements and pricing dynamics. These forces converge into a single strategic reality: success will belong to players who can align product architecture, production footprint, and compliance readiness with where demand is heading, not where it has been.
Key Challenges and Inflection Points
The market faces several interconnected challenges that will define competitive outcomes over the next several years. Raw material dependency and cost volatility remain fundamental pressures. SAP production is closely tied to acrylic acid availability and energy input, meaning that margin stability depends on integrated feedstock access, process efficiency, and the ability to manage intermittent cost spikes. Companies that can secure upstream integration or negotiate resilient supply arrangements will maintain a structural advantage in an environment where cost discipline directly influences pricing power.
PW Consulting
Regulatory and sustainability expectations represent another critical inflection point. Buyers and brand owners are increasingly requiring verifiable environmental credentials rather than aspirational claims. Carbon footprint verification, bio-based material pathways, and recycling compatibility are moving from optional narratives to procurement prerequisites. This shift introduces both cost and capability demands: manufacturers must invest in certified production pathways, lifecycle documentation, and formulation adjustments without sacrificing absorption performance or throughput. The challenge is not simply meeting regulation, but doing so in ways that preserve commercial competitiveness.
A third challenge lies in application fragmentation. SAP used in hygiene products differs materially from SAP formulated for agricultural water retention, medical absorption, or industrial blocking applications. Each segment imposes distinct criteria on swelling ratio, gel strength, particle size distribution, salinity tolerance, and processing behavior. The result is a widening technical bar for producers who must manage multiple product grades while avoiding excessive complexity in manufacturing and inventory. Companies that overcommit to undifferentiated capacity may find themselves exposed to margin compression, while those that align grade architecture with high-value applications can command better positioning.
Technology Innovation and Performance Frontiers
Technological progress is redefining what SAP can deliver and how it competes. Recent product introductions illustrate a clear industry direction toward zero-carbon and low-impact variants. BASF’s HySorb® B 6610 ZeroPCF, launched in early 2025, marked the first polyacrylate-based super absorbent polymer with a product carbon footprint of zero for hygiene applications. This achievement was enabled through renewable energy use and a biomass balance approach, and the product is ISCC PLUS-certified. The strategic significance extends beyond a single product launch: it signals that carbon-neutral SAP is commercially viable and ready for integration into hygiene value chains that demand verifiable environmental credentials.
Innovation is also advancing through material design and process efficiency. LG Chem continues to advance bio-balanced and standard SAP grades using a self-polymerization process, reinforcing a model where formulation control and process ownership support both performance consistency and supply flexibility. Sumitomo Seika Chemicals has focused on circularity by unveiling a horizontal chemical-recycling process for diaper-grade SAP, with a pilot expected in fiscal 2026 and commercial rollout targeted around 2030. This direction suggests that future SAP competitiveness may depend not only on absorption metrics but also on recyclability, recovery pathways, and the ability to participate in closed-loop material strategies.
These developments matter because they reshape procurement logic. When sustainability credentials and recycling compatibility become part of specification, the basis of competition expands from cost-per-ton to value-per-performance-profile. Manufacturers that integrate carbon, circularity, and application-grade precision into their product portfolios will be better positioned to secure long-term contracts and premium positioning.
Policy, Regulation, and Sustainability Requirements
Policy and regulatory dynamics are accelerating the market’s sustainability pivot. Although requirements differ by jurisdiction, the broader direction is consistent: increasing scrutiny of carbon intensity, material sourcing, and end-of-life impact. Certification frameworks and brand-owner expectations are translating into practical procurement filters. SAP suppliers cannot rely solely on functional specifications; they must also demonstrate alignment with buyer sustainability commitments and compliance documentation standards.
This shift has operational consequences. Production sites that rely on renewable energy, utilize biomass-balanced feedstocks, or achieve recognized certification gain a meaningful commercial advantage in tenders where environmental attributes influence selection. At the same time, regulators and customers are not asking for sustainability at the expense of performance. The strategic challenge is to combine credibility with reliability: maintaining absorption capacity, gel integrity, and processing consistency while introducing lower-impact materials and processes. Companies that treat sustainability as an engineering and supply chain discipline rather than a marketing exercise will be best equipped to navigate this environment.
Demand-Side Shifts and Application Diversification
Demand patterns are evolving as end-use sectors broaden and consumer behavior changes. Personal hygiene remains the central application anchor, supported by ongoing demand for diapers and adult care products. However, the market is increasingly shaped by adjacent opportunities where SAP solves specific moisture-management problems. Agriculture represents one such frontier, where water retention and soil condition improvement create demand for SAP with different performance priorities than hygiene grades. Medical applications, though smaller in volume, are important for specialized absorption needs where purity, compatibility, and reliability are paramount. Industrial uses add further complexity, spanning water blocking, cable protection, and other moisture-control functions.
This diversification changes the competitive calculus. A manufacturer with strong hygiene grades may still need to adapt formulations, process parameters, and quality systems to capture value in agriculture or industrial applications. The most resilient strategies combine core-volume strength with selective expansion into segments where technical expertise and specification fit create defensible positions. For buyers, the diversification also means more choice and more negotiation leverage, but only if suppliers can reliably deliver differentiated grades at scale.
Supply Chain Reconfiguration and Cost Structure Evolution
Supply chain architecture is becoming a strategic differentiator. Regional capacity investments are reducing reliance on distant production hubs and shortening response times to local demand changes. Nippon Shokubai’s August 2025 groundbreaking for a new 50 kt/yr SAP plant in Indonesia illustrates how producers are expanding within growth regions to serve Southeast Asian hygiene and agricultural demand directly. Integrated acrylic acid production across multiple countries strengthens feedstock stability and allows producers to manage cost exposure more effectively.
Polyacrylamides (PAM) Market
Cost structure dynamics are also influenced by manufacturing scale, R&D intensity, and process maturity. Chinese manufacturers such as Nuoer and Banglida continue to build capacity and product breadth, with Nuoer operating significant annual capacity and maintaining multiple R&D bases, product lines, and active patents. Banglida has scaled production with advanced equipment and a focused workforce. These developments underscore a competitive environment where regional scale, equipment modernization, and product specialization coexist. The broader lesson is that cost leadership is not automatically synonymous with capacity leadership; it must be supported by stable feedstock access, process efficiency, and grade-level profitability.
Strategic Positioning of Leading Manufacturers
The competitive landscape is shaped by the way leading companies combine product brands, process control, regional footprint, and sustainability readiness. BASF maintains a strong global position through well-known SAP brands and a sustainability-forward product strategy. Its zero-PCF launch and certification pathway demonstrate an effort to align performance with environmental accountability, which is increasingly relevant for hygiene customers under sustainability pressure.
Nippon Shokubai’s strategy emphasizes scale, integration, and regional expansion. With a leading share in disposable diaper applications and integrated acrylic acid production across multiple countries, the company is built to serve global demand while reinforcing supply resilience. Its Indonesian expansion reflects a deliberate push to capture growth in Southeast Asia, where hygiene and agricultural demand continue to rise. Sumitomo Seika Chemicals differentiates through application versatility and circularity development. Its SAP portfolio spans hygiene, industrial water-blocking, and agricultural uses, and its chemical-recycling initiative positions the company to participate in longer-term circular economy expectations.
LG Chem offers another strategic model: bio-balanced and standard SAP production supported by a self-polymerization process, serving hygiene, sanitary, wire sheath, and cooling applications. This approach highlights the value of process ownership in maintaining product consistency and expanding application coverage. Nuoer and Banglida represent the growing influence of high-capacity regional manufacturers with strong focus on absorbency performance and product range. Nuoer’s emphasis on high-CRC and ultra-high absorbency grades, alongside a broad R&D footprint, illustrates how capability depth can support competitive presence. Banglida’s focus on high absorption capacity and scalable production reinforces the importance of equipment quality and operational discipline in sustaining growth.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The market is likely to evolve through a combination of consolidation and selective fragmentation. Consolidation will remain relevant where integrated feedstock access, global distribution, and sustainability certification create advantages that are difficult for smaller players to replicate quickly. Larger producers may also pursue capacity additions that strengthen regional presence and improve service levels for major customers. At the same time, fragmentation will persist because application-specific requirements and regional demand dynamics create room for specialized manufacturers. High-absorbency grades, bio-based or lower-carbon variants, and recycled-material pathways can each support distinct competitive niches.
New entrants and capacity expansions will continue to influence pricing and availability, especially in regions with strong demand growth. The risk for established players is complacency in the face of localized competition; the opportunity is to use brand strength, technical service, and sustainability credentials to deepen customer relationships. For emerging manufacturers, the challenge is to move beyond capacity growth and build differentiation through grade specificity, quality consistency, and credible environmental performance.
Future Trend 1: Sustainability as a Procurement Gate
Over the next three to five years, sustainability is likely to become a gate criterion rather than a bonus feature. Procurement processes will increasingly require evidence of carbon footprint management, certified sourcing, and circular compatibility. This trend will reward producers that can deliver verified low-impact SAP without compromising absorption performance. It will also raise the importance of documentation, lifecycle transparency, and certification readiness. Companies that can integrate these attributes into standard offerings will be better positioned to secure long-term supply agreements and avoid losing share to competitors with stronger environmental alignment.
Future Trend 2: Regional Capacity Localization and Supply Resilience
Capacity expansion is expected to continue in regions that combine demand growth with logistics and cost considerations. Localized production will help reduce exposure to freight volatility and improve responsiveness to end-market changes. This trend will be particularly important for hygiene and agricultural applications, where demand fluctuations and customer service expectations reward regional proximity. The commercial opportunity lies in building supply architectures that balance scale with closeness, ensuring that capacity is not only available but also reliably accessible where it is needed.
Future Trend 3: Application Diversification with Grade Specialization
SAP demand will continue to spread across multiple applications, each with distinct performance requirements. This will encourage more specialized grade development and a broader portfolio logic. Manufacturers that can tailor formulations for agricultural water retention, medical absorption, industrial blocking, and hygiene performance will capture more value than those that rely on a single generalized product. The opportunity here is to use technical service and application engineering as differentiators, helping customers optimize SAP usage and creating switching costs through specification fit.
Commercial Opportunities
These trends point to several commercial opportunities. First, sustainability-aligned SAP grades can open access to customers with explicit decarbonization and compliance goals. Second, regional capacity and supply resilience can strengthen customer retention in markets where service reliability is increasingly valued. Third, application-specific SAP solutions can support premium positioning and longer-term relationships by solving customer problems more precisely. Each opportunity depends on execution: credible certification, consistent quality, and the ability to scale differentiated grades withoutlosing cost discipline.
Risks and Uncertainties
Several uncertainties warrant caution. Raw material cost volatility and energy price fluctuations can compress margins if not managed through integration or hedging strategies. Overinvestment in undifferentiated capacity may lead to pricing pressure and weakened profitability. Regulatory expectations may evolve faster than product development cycles, creating compliance gaps for companies that underestimate documentation and certification demands. In addition, application diversification can increase complexity if product portfolios become too fragmented to manage efficiently. The balance between specialization and operational discipline will determine whether diversification becomes a growth lever or a cost drain.
Bio-Based Superabsorbent Polymers (SAP) for Hygiene Products Market
Strategic Guidance for Manufacturers
Manufacturers should prioritize three actions. First, align product development with verifiable sustainability requirements and ensure certification and documentation capabilities are in place. Second, optimize capacity deployment by matching regional expansion to demand growth and customer service needs, rather than pursuing scale for its own sake. Third, strengthen grade-level differentiation by focusing on applications where technical service and formulation fit create defensible value. Companies that execute on these fronts will be better positioned to convert market growth into durable margin advantage.
Strategic Guidance for Investors
Investors should evaluate SAP exposure through the lens of differentiation and resilience. Capacity alone is an incomplete signal; the more relevant questions concern feedstock integration, sustainability credentials, regional positioning, and application breadth. Companies with credible low-carbon pathways, certified production, and strong customer relationships in growth regions are likely to capture more durable value. At the same time, due diligence should account for complexity risk: portfolios that are overly fragmented or dependent on volatile input structures may face margin instability even in a growing market.
Strategic Guidance for Procurement and Supply Chain Leaders
Procurement leaders should treat SAP sourcing as a multi-criteria decision that includes performance, availability, and environmental alignment. Diversifying the supplier base by capability rather than by price alone can reduce exposure to supply disruptions and future compliance shifts. Specification language should be updated to reflect sustainability requirements where relevant, and supplier qualification should include documentation, certification, and service reliability. Early engagement with suppliers that demonstrate both performance consistency and credible sustainability readiness can reduce transition risk and improve long-term sourcing stability.
Conclusion
The super absorbent polymer market is moving into a phase where growth is expected but competitive advantage is increasingly selective. The combination of sustainability mandates, regional supply reconfiguration, and application diversification is reshaping procurement logic and product strategy. Companies that can integrate low-impact production, localized supply resilience, and application-specific performance will be best prepared to capture value as the market expands toward 2032. For decision-makers seeking deeper segmentation data, company-level benchmarking, and customized scenario planning, a full research report can provide the detailed teardown and forward modeling needed to translate these trends into concrete commercial actions.
For detailed analysis of this topic, please visit the official page: Super Absorbent Polymer (SAP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com