

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Honing Machines Market Outlook: Inside the 5.5% CAGR Growth Trajectory to 2032

The Honing Machines Market: Strategic Trends and Commercial Opportunities Through 2032
The precision machining landscape is undergoing a quiet but decisive transformation. Honing machines, once viewed as a mature specialty tool for finishing cylindrical bores, are now experiencing renewed strategic importance driven by tighter tolerances, material complexity, and the need for repeatable surface integrity across high-value components. The addressable revenue for this equipment category expanded from approximately 600 million USD in 2020 to an estimated 773.0 million USD in 2025, and forward projections point to a 1,126.0 million USD market by 2032. That trajectory reflects a compound annual growth rate near 5.5 percent, a pace that is modest in absolute terms but meaningful when layered against rising expectations for quality, throughput, and labor efficiency. For executives and investors, the story is not simply about a growing equipment market; it is about where capability gaps are opening, which regions and applications are consolidating value, and how leading manufacturers are positioning to capture it.
Market Snapshot and Core Challenges
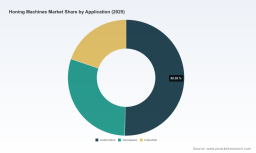
Over the historical window from 2020 through 2025, the honing equipment segment demonstrated resilience through periods of supply chain friction and uneven demand cycles. By the base year of 2025, the market sits at 773.0 million USD, and the forecast path from 2026 through 2032 implies a gradual acceleration rather than an explosive breakout. Growth is broadly distributed, but not evenly weighted. Regional activity concentrates around the Asia Pacific corridor, followed by North America and Europe, with smaller but still strategic contributions from Latin America and the Middle East and Africa. On the equipment side, horizontal configurations command the larger share of revenue, while vertical platforms hold a substantial and technically distinct portion of the demand base. By end use, automotive applications anchor the largest segment, aerospace follows as a high-value demand center, and industrial applications provide a diversified and recurring floor of activity.
Market structure remains moderately fragmented but is steadily consolidating around a handful of capable players. Concentration metrics indicate that roughly 42.5 percent of revenue is held by the top three firms, and the top five account for about 58.3 percent. This pattern suggests a market where scale, application specialization, and after-sales capability increasingly matter, even as regional and niche participants continue to compete on price, service proximity, or product flexibility. The implication is straightforward: competitive advantage will be less about announcing a single new machine and more about building repeatable precision, uptime, and application engineering strength across a portfolio.
Where the Pressure Points Are
Despite the constructive growth outlook, several structural challenges are reshaping how buyers evaluate honing equipment and how suppliers must design their offerings.
- Escalating precision expectations are compressing the margin for error. As components move toward thinner walls, tighter bore geometries, and surface finish requirements that directly influence performance and life, operators are demanding better repeatability and traceability. Machines that cannot reliably hold tolerances across shift-to-shift variation or that require heavy manual intervention are losing ground to more controlled, CNC-centric solutions.
- Labor availability is becoming a hidden constraint on adoption. Skilled operators and setup technicians remain difficult to secure in many regions. This shortage affects not only throughput but also the business case for equipment itself. Honing machines that demand highly specialized handling face slower uptake because customers must solve an operational workforce problem before they can solve a quality problem.
- Component and input cost dynamics are pressuring both pricing and development cycles. The core material foundation of honing equipment depends heavily on diamond abrasives and carbide tooling, which serve as both consumables and integral performance enablers. Fluctuations in these inputs influence cost structures, service economics, and the pace at which manufacturers can introduce new machine generations without compromising margins.
Key Growth Drivers
The 5.5 percent CAGR through 2032 is not a statistical abstraction; it reflects a set of durable forces that are altering demand, product design, and competitive behavior. At least four drivers stand out.
1. Technology Innovation and Precision Automation
The most consequential shift is the movement from labor-intensive finishing toward integrated CNC and multi-spindle platforms that combine tighter process control with reduced cycle time. Recent equipment introductions make this trend visible. In mid-2025, KADIA Produktion GmbH introduced its third-generation U line universal honing machine, a two-spindle platform designed to raise precision and productivity while improving maintenance accessibility. Around the same time, Abhi Fine Products launched the ABE20550 Twin Spindle Expansion Honing Machine at IMTEX 2025, signaling continued activity in vertical and horizontal configurations aimed at precision internal machining. These developments are not isolated product launches; they are evidence of a broader push toward machines that can do more in a single setup, reduce manual variability, and support repeatable bore finishing across automotive, aerospace, and general engineering work.
For business leaders, the practical takeaway is that machine selection is increasingly a process decision rather than a simple capital equipment purchase. Buyers are comparing uptime characteristics, tooling flexibility, integration with existing machining cells, and the ability to reduce operator dependency. Suppliers that can deliver documented improvements in consistency, setup time, and consumable efficiency will find a stronger value proposition than those competing solely on initial price.
2. Regulatory and Standards Pressure on Operator Competence
Regulatory and standards-based expectations are becoming a meaningful influence on equipment demand, particularly where machining outcomes must be auditable and operator qualifications are formalized. In the UK, machining operations on honing or lapping machines must comply with the British Standard SEMMME214 for operator competence, reinforcing the link between equipment capability and workforce readiness. While this is a national standard, it reflects a broader global tendency for quality-critical sectors to require clearer competence assurance, especially in applications where surface integrity affects downstream performance.
PW Consulting
This environment favors equipment that simplifies setup, supports standardized work, and reduces reliance on tacit knowledge that is difficult to scale. It also elevates the importance of documentation, training support, and service ecosystems. Companies that treat operator enablement as part of the product, rather than as an afterthought, are better positioned to meet compliance-oriented buyers and industrial customers seeking consistent results across sites.
3. Demand-Side Evolution Across Automotive and Aerospace
End-user demand is the main engine of growth, and the composition of that demand is shifting toward applications where bore quality directly affects functional performance. Automotive remains the largest demand center, driven by engine and transmission components, hydraulic systems, and the broader need for reliable internal geometries in high-volume production. Aerospace adds a different profile of demand: lower volumes but higher value, stricter tolerances, and a premium on surface quality and traceability. Industrial applications contribute a broad and diversified base, supporting demand for honing across general engineering and component manufacturing.
The commercial implication is that the market is not a monolith. High-volume automotive work tends to reward speed, tool life, and repeatable process control, while aerospace and precision industrial work often prioritize surface integrity, flexibility, and application engineering. Winning suppliers need to manage these differing expectations within the same product family or portfolio, often by offering variants that address throughput in one segment and precision or customization in another.
4. Cost Structures, Purchase Economics, and Mid-Range CNC Adoption
Capital economics are shaping adoption patterns as much as technical requirements are. Mid-range CNC honing machines typically carry an average purchase price between USD 120,000 and USD 180,000, a band that places them in a strategic middle ground: accessible enough for serious capacity upgrades, yet substantial enough to require a clear return case. This price structure pushes buyers to think in terms of total cost of ownership, including consumable usage, changeover time, service responsiveness, and the cost of operator skill. It also makes competitive differentiation more nuanced, because two machines with similar nominal specifications can have very different operating economics.
At the same time, raw material realities deserve attention. Diamond abrasives and carbide tools constitute the primary raw material and core component foundation for honing machines, so supply stability and consumable performance directly affect customer economics. Equipment vendors that provide better tooling management, predictable consumable behavior, or integrated finishing solutions can create value even in a market where machine prices face upward pressure.
Competitive Landscape and Leading Strategies
The competitive field includes a mix of established precision brands and regionally focused manufacturers, each pursuing a different route to relevance. Sunnen Products Company, headquartered in Saint Louis, Missouri, offers horizontal, vertical, single-stroke, and tube honing machines alongside precision abrasives for automotive, aerospace, and general engineering bore finishing. Its breadth across machine types and abrasives gives it a systems-oriented positioning that appeals to buyers looking for a broader finishing capability rather than a standalone machine. In early 2026, Sunnen participated in the STOM Show in Poland, showcasing precision honing machines for hydraulic, automotive, and engineering components, a reminder that trade presence and application visibility remain important tools for maintaining market awareness.
German manufacturers continue to play a central role in the precision segment. KADIA Produktion GmbH has focused on universal two-spindle CNC honing machines, most recently advancing its third-generation U line with enhanced precision, productivity, and maintenance features. NAGEL Maschinen- und Werkzeugfabrik GmbH specializes in CNC honing machines and precision tools for automotive and industrial applications, while Gehring Technologies GmbH produces precision honing machines and systems for aerospace and automotive precision bore finishing. Lapmaster Wolters complements this group by providing lapping and honing machines for precision surface finishing, broadening the scope of surface-quality solutions. The common thread among these players is a focus on process control, application credibility, and after-sales reliability, which matter particularly in high-value or compliance-sensitive work.
North American and Asian participants add important variation. Nagel Precision Inc. positions itself as a North American provider of precision honing machines and tooling systems, offering a regional service and distribution angle. Nissin Precision Machines Co., Ltd. in Japan produces advanced CNC honing machines for aerospace, automotive, and general precision applications, while Toyo Advanced Technologies Co., Ltd. supplies single-axis and vertical honing machines for precision manufacturing. PEMAMO SA in Switzerland develops high-precision honing machines and tools for industrial and automotive use, and Engis Corporation specializes in precision finishing and honing systems for complex components. Rottler Manufacturing rounds out the U.S. presence with vertical CNC honing machines for engine block and cylinder rebuilding, an application-specific niche that highlights how specialized use cases can anchor a business line.
In India, Abhi Fine Products manufactures vertical and horizontal honing machines, including newer Twin Spindle Expansion models for precision internal machining, and has shown a willingness to introduce new configurations at major trade events. In China, Duo Bang Machinery Co., Ltd. manufactures vertical and horizontal honing machines for automotive and industrial components, while Ningxia Zhongwei Dahe Machine Tool Co., Ltd. produces heavy-duty honing machines for industrial applications. These players illustrate a market where regional proximity, price competitiveness, and segmentation by application can create viable positions even against more globally recognized brands.
Hardening Machines Market
How Leading Players Are Differentiating
The market is not being won by a single type of company. Instead, successful players tend to differentiate along a few recognizable lines.
- Application depth over generic breadth. Firms that can speak credibly to specific end uses, such as engine block and cylinder rebuilding, aerospace bore finishing, or hydraulic components, often build stronger customer trust than those relying on broad product catalogs alone.
- Process control and multi-spindle flexibility. Multi-spindle and CNC-centric platforms are increasingly attractive because they reduce variability and can improve throughput without sacrificing precision. This is a clear area of competitive motion, especially as buyers seek to reduce dependency on scarce skilled labor.
- Service and consumable ecosystems. Because diamond abrasives and carbide tools are central to machine performance, the ability to provide reliable tooling, predictable consumable behavior, and responsive maintenance can be as important as the machine specification itself.
- Regional presence with global relevance. Some competitors win by being close to the customer, offering local support and faster problem resolution, while still maintaining enough technical credibility to serve demanding applications.
How the Landscape Is Evolving
The configuration of the market suggests continued but selective consolidation. With the top three firms holding about 42.5 percent and the top five around 58.3 percent, there is already meaningful concentration at the top, yet enough fragmentation below the leaders for regional specialists and niche application providers to survive. Over the next few years, expect further divergence: larger players may expand through portfolio breadth, application engineering, and service reach, while smaller firms may thrive by focusing on specific machine types, consumables, or regional demand pockets. New entrants are likely to face the steepest hurdle in premium precision segments unless they bring a clear technical or cost-structure advantage. Conversely, segments tied to rebuilding, heavy industrial use, or localized service needs may remain more open to new competition, especially where buyers prioritize responsiveness and practical uptime over brand pedigree.
Future Trends and Commercial Opportunities
Looking from 2026 through the early 2030s, several trends are likely to shape where value accrues and how companies should position themselves.
1. Precision-as-a-Process Will Become the Default Buying Logic
Buyers will increasingly evaluate honing equipment as part of a broader finishing process rather than as an isolated asset. That means machine specifications will be judged alongside tooling behavior, setup simplicity, consumable consistency, documentation, and operator enablement. The commercial opportunity here is for suppliers that can package technology and support into a defensible process solution. Companies that can demonstrate reduced variability, faster changeovers, or better consumable economics will have stronger pricing power than those competing only on machine features. The risk is that vendors who fail to invest in application engineering and service integration may see their specifications commoditized, especially in mid-range segments where buyers are comparing total cost of ownership more aggressively.
Worldwide Grinding Machine With Moving Table Market
2. Labor Constraints Will Accelerate Automation and Standardization
The persistent shortage of skilled operators is not a temporary inconvenience; it is becoming a structural reason to choose equipment that is easier to set up, easier to run, and easier to standardize across shifts and sites. Expect stronger demand for CNC-centric platforms, better process documentation, and machines that reduce the need for highly specialized manual judgment. For suppliers, the opportunity lies in designing for repeatability and providing tools that help less experienced operators achieve reliable results. For buyers, the strategic move is to select equipment that lowers operational dependence on scarce talent while preserving quality. The uncertainty is that automation adoption may be uneven across regions and customer segments, and some markets may manage the labor constraint through extended shifts or outsourcing rather than new equipment, softening near-term demand in certain pockets.
3. Regional Demand Will Stay Centered on Asia Pacific, but Value Capture Will Depend on Application Strength
Asia Pacific continues to represent the largest regional concentration of demand, and that orientation should persist as manufacturing activity, component complexity, and precision expectations grow. However, regional size alone does not guarantee profitable growth. The more important question is which players can convert regional volume into sustainable margin through application specialization, service quality, and consumable economics. North America and Europe will remain important, particularly in higher-value applications and where standards and compliance expectations influence equipment selection. Latin America and the Middle East and Africa will likely continue to contribute smaller but strategically relevant demand, especially where industrial and automotive components are machined or rebuilt locally. The risk for global suppliers is underestimating local competition and service expectations; the opportunity is building regional relevance without diluting technical credibility.
Strategic Implications for Decision Makers
The honing machines market is expanding at a measured but steady pace, and the real strategic question is how to position within that growth so that a company captures more than a share of revenue. Different audiences will need different actions.
For Equipment Manufacturers and Integrators
- Invest in multi-spindle and CNC-centric capability that reduces operator dependence. The market is rewarding machines that improve repeatability and simplify setup, especially as skilled-operator shortages persist.
- Build application credibility in the segments that matter most to your portfolio. Automotive volume, aerospace precision, engine rebuilding, and industrial heavy-duty use each reward different strengths. Clear positioning makes it easier to compete on value rather than price alone.
- Treat tooling, consumables, and service as part of the product promise. Since diamond abrasives and carbide tools are core to performance, predictable consumable behavior and responsive support can differentiate a machine in practice, not just on paper.
For Investors and Strategic Partners
- Focus on companies with durable application depth and service ecosystems. The moderate concentration at the top of the market suggests scale and credibility matter, but the most attractive opportunities may be in firms that combine technical competence with strong regional or segment-specific execution.
- Watch for evidence of process-level differentiation rather than spec-sheet competition. Machines that improve uptime, reduce setup complexity, or stabilize consumable performance are more likely to sustain pricing power over a multi-year horizon.
- Track consolidation signals carefully. With meaningful share held by leading players, future moves in M&A, distribution partnerships, or regional service expansion could reshape competitive access more than incremental product launches.
For Procurement and Operations Leaders
- Evaluate total cost of ownership, not just acquisition price. With mid-range CNC machines typically priced between USD 120,000 and USD 180,000, the decision should include consumables, changeover time, training burden, and service responsiveness.
- Prioritize machine choices that reduce dependence on scarce skilled labor. Equipment that supports standardized work, clearer setup procedures, and repeatable outcomes can mitigate operational risk while improving quality consistency.
- Align machine selection with compliance and competence expectations. Where operator standards such as SEMMME214 apply, equipment that supports documented competence and consistent outcomes will be easier to justify internally and to auditors or customers.
Why the Next Phase of the Market Deserves Deeper Intelligence
The broad contours of the honing machines market are now clear: steady growth toward 2032, a meaningful concentration of demand around Asia Pacific, automotive, and aerospace, and a competitive field where application strength and service reliability increasingly matter as much as machine specification. What is less visible from the surface is where the highest-margin opportunities will appear, which subsegments are becoming more commoditized, how consumable economics will affect customer adoption, and where regional service capacity will determine commercial success. Those questions are best answered with segment-level data, company-level movement tracking, and scenario-based planning rather than headline market size alone.
For organizations making capital, partnership, or go-to-market decisions, the value lies in connecting the 5.5 percent CAGR and the 1,126.0 million USD end-point to operational reality: which machine types, applications, and regional pathways offer the strongest commercial logic today, and how that logic may shift as automation, labor availability, and precision expectations continue to evolve. Detailed segmentation data, competitive monitoring, and tailored strategic recommendations can help leaders move from general market confidence to specific, defensible action.
For detailed analysis of this topic, please visit the official page: Honing Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com