

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Dental Chair Market: Why 5.4% CAGR and 848 Million in 2032 Signal a Shift

Strategic Shifts and Commercial Opportunities in the Dental Chair Market
The dental chair market is undergoing a period of structural transformation, driven by a convergence of technological innovation, regulatory tightening, and shifting demand patterns across care settings. Valued at approximately $480 million in 2020, the market has expanded steadily to reach $587.7 million in 2025, with projections indicating growth to $848 million by 2032. This trajectory reflects a compound annual growth rate of 5.4% over the 2026–2032 forecast period, a pace that signals durable demand rather than speculative expansion. The underlying growth is not uniform across all segments, but the overall trajectory points to a market where value creation increasingly depends on integration, compliance, and patient experience.
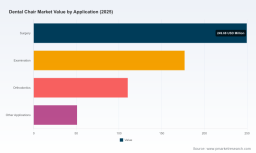
Beyond the headline figures, the market dynamics reveal important structural nuances. The revenue split between powered and non-powered dental chairs remains closely balanced, indicating that demand is bifurcated by clinical need and budget constraints. Surgical applications continue to capture the largest share of value, reflecting the procedural intensity and equipment-specific requirements of operative settings. Examination and orthodontic use follow, each with distinct ergonomics, workflow, and positioning requirements. Regionally, North America and Europe represent the largest revenue pools, while Asia Pacific and Latin America reflect faster adoption curves in emerging clinic networks and public health expansion initiatives. The market remains relatively fragmented at the top, with the top three players accounting for roughly 22.8% of revenue and the top five reaching about 28.5%, leaving meaningful room for specialized entrants, regional champions, and platform leaders to differentiate.
Key Inflection Points Shaping the Market
A market growing at a mid-single-digit pace can still present pronounced strategic tension. Three challenges stand out for decision-makers evaluating near-term positioning.
Dental Market
The first is the widening gap between clinical expectations and equipment capability. Dentists and patients increasingly expect chairs that support ergonomic workflows, patient comfort, and seamless integration with digital tools. This raises the bar for manufacturers to deliver not just a seat, but a configurable clinical platform. The second challenge is regulatory and standards pressure around infection control, water management, suction, and wastewater systems. As stationary dental units become more complex, the compliance burden increases, particularly for newer entrants seeking market access in regulated territories. The third challenge is the economic sensitivity of certain end users. While surgical and multi-specialty practices can justify premium investments, smaller clinics and high-volume care settings may prioritize affordability, serviceability, and total cost of ownership, creating pressure on pricing and differentiation.
Together, these forces are reshaping the market’s center of gravity. Growth will increasingly accrue to players that can combine usability, compliance, and workflow efficiency in ways that are hard to replicate quickly, while also maintaining credible access to cost-sensitive segments.
Key Demand Drivers Redefining the Market
Technology Innovation and Workflow Integration
The most consequential driver is the shift from isolated dental chairs to integrated operatory solutions. Practitioners are looking for equipment that reduces repositioning time, supports ambidextrous working styles, and connects with digital workflows such as imaging, intraoral scanning, and treatment-planning tools. This is not merely a convenience trend; it has direct implications for chair time, staff ergonomics, and procedure throughput. Manufacturers that embed intuitive user interfaces, modular consoles, and instrument configurations aligned to clinical routines are better positioned to capture value in workflows that demand speed and repeatability.
Recent market activity illustrates this direction. At IDS 2025, a major dental equipment specialist introduced a new generation of dental units and patient chairs emphasizing ambidextrous hanging tube delivery, a larger user interface, and a modular console architecture. The product update underscores a broader industry move toward flexibility in instrument access and easier adaptation to different practice layouts. In parallel, broader platform players continue to push AI-guided positioning and comprehensive operatory ecosystems across multiple countries, reinforcing the expectation that clinical equipment is becoming more software-defined and more connected.
The business implication is clear: value will migrate toward systems that reduce setup friction, improve clinician ergonomics, and integrate without disrupting existing digital workflows. This favors modular architectures and configuration options that can be tailored to procedure mix, space constraints, and staff preferences.
Dental Material Market
Policy, Standards, and Regulatory Access
Regulatory and standards developments are reshaping both the pace of product introduction and the structure of market entry. Dental chairs and operative units are subject to clearance requirements in major markets, and product classification can influence timelines, documentation, and testing burden. In the United States, dental chairs and operative units in certain product categories require premarket clearance, and compliance expectations increasingly extend beyond the device itself to supporting systems such as waterlines, suction, and wastewater handling.
The standards environment is also evolving. A proposed update to a key stationary dental unit standard has put renewed attention on air, water, suction, and wastewater system requirements, including test methods and performance expectations. For manufacturers, this signals that product design can no longer treat utilities and infection control as afterthoughts. It also raises the importance of documentation discipline, validation, and post-market support. Newer entrants seeking access to regulated markets must plan for these requirements early, since clearance and standards alignment can become a meaningful barrier or a differentiator depending on execution.
A practical example of this dynamic is visible in recent clearance activity for a cost-oriented integral dental unit with a patient chair designed for clinic use. The receipt of 510(k) clearance signaled that such products can reach the U.S. market when they demonstrate equivalence to predicate devices, while also highlighting the diligence required to navigate product code requirements and classification rules. The broader lesson is that regulatory strategy is now a market entry lever, not a back-office function.
Demand-Side Shifts in Patient Experience and Clinic Economics
Demand is being reshaped by two reinforcing forces: patient expectations and clinic economics. Patients increasingly associate equipment quality with comfort, privacy, and professionalism. Chairs that support whole-body support, better positioning, and calm clinic environments can influence appointment experience and retention, especially in competitive urban settings. At the same time, clinics are under pressure to manage labor, turnover, and infection control costs. Equipment that reduces setup time, improves accessibility, and simplifies cleaning or maintenance can contribute to operational efficiency even when purchase price is not the lowest.
This dual pressure is encouraging a broader set of buying criteria. Some practices are prioritizing barrier-free or accessibility-oriented designs that support inclusive care and simplify movement for staff and patients. Others are attentive to maintenance and waterline management, where even modest training and procedural discipline can affect reliability and compliance. The result is a market in which the best value proposition is increasingly multi-dimensional: comfort, ergonomics, infection control, and usability all matter, but their relative importance varies by practice type and patient mix.
Supply Chain and Cost Structure Dynamics
A fourth driver is the evolving cost structure of dental equipment manufacturing and distribution. Regional manufacturing footprints, component sourcing, and service networks all influence both price competitiveness and responsiveness. In cost-sensitive segments, there is growing interest in operatory solutions that balance functionality with affordability, particularly for clinics expanding in developing markets or building high-throughput models. In premium segments, the value equation is more about differentiation, clinical performance, and service reliability than unit cost alone.
This divergence is creating opportunities for targeted positioning. Manufacturers serving broader global markets need to manage the tension between scale efficiency and local adaptation, especially when utility configurations, clinical norms, and service expectations differ by region. At the same time, regional specialists can compete effectively by focusing on particular workflow needs, practice types, or geographic service commitments. The cost structure discussion therefore leads directly to a strategy question: should a company pursue platform breadth, or concentrate on a clearly defined clinical and economic niche?
Competitive Landscape and Strategic Positioning
A Fragmented but Increasingly Layered Market
The competitive set spans ergonomic specialists, global platform providers, and cost-focused manufacturers, each pursuing a distinct value proposition. Some companies anchor their positioning in patient comfort and whole-body support, building product families around reliability and ergonomic alignment with practitioner posture. Others emphasize ambidextrous delivery, multi-instrument configurations, and digital maintenance monitoring, targeting practices that value flexibility and service predictability. There are also players that focus on accessibility, infection control, and barrier-free oral procedure designs, aligning with inclusive care and higher-throughput settings. On the cost side, a number of manufacturers offer integral dental units and clinic-oriented solutions that make operatory capability more accessible to budget-conscious buyers.
Differentiation Anchors Among Leading Players
Several differentiation themes are evident across the leading companies.
- Ergonomics and whole-body support remain a strong anchor for brands that position the chair as a comfort and reliability platform rather than a commodity fixture.
- Ambidextrous and modular delivery systems are becoming important for practices that need instrument access flexibility, shorter setup times, and adaptability to varied operatory layouts.
- Digital and health-care IT connectivity is expanding from a differentiator into more of a baseline expectation, especially when it supports maintenance monitoring, configuration management, or integration with digital workflows.
- Infection control and accessibility are increasingly embedded in product identity, not just compliance documentation, particularly for chairs designed for barrier-free use or higher clinical throughput.
- Regulatory access and clearance discipline are emerging as competitive advantages for companies that can demonstrate repeatable market entry in regulated territories.
How the Landscape Is Evolving
The market is neither fully consolidated nor purely fragmented; it is becoming layered. Large global providers continue to expand platform breadth and cross-market presence, using ecosystems and integrated workflows to justify premium positioning. Specialized manufacturers compete by deepening their fit with particular clinical workflows, ergonomic priorities, or regional service needs. Meanwhile, newer entrants are finding openings in cost-sensitive segments and in markets where clinic expansion and dental access initiatives increase demand for basic, reliable operatory capacity.
From a strategic standpoint, the most interesting trend is the growing importance of “fit” as a competitive moat. A chair that is technically adequate but poorly matched to a practice’s workflow, space constraints, or compliance requirements will lose against a more tailored alternative, even if it costs less. This suggests that competitive advantage will increasingly come from configuration depth, service readiness, and the ability to align equipment with real clinical operations rather than from broad feature claims alone.
Forward Outlook: Trends Likely to Shape the Next Three to Five Years
Trend One: From Equipment Purchases to Operatory Platforms
Over the next several years, purchasing decisions will likely place even greater weight on how a dental chair fits into a broader operatory platform. Practitioners will continue to favor systems that reduce repositioning effort, support multiple instrument configurations, and connect cleanly with imaging, scanning, and practice workflows. The strategic opportunity is to design chairs and units that are modular enough to adapt across procedure types while remaining simple to configure and maintain. Companies that can reduce operational friction will be better positioned to defend pricing and loyalty in a market where buyers compare total workflow impact, not just unit specifications.
PW Consulting
Trend Two: Compliance and Infection Control as Design Drivers
Standards evolution and clearance expectations will continue to influence product design and market access. Air, water, suction, and wastewater performance requirements are receiving more attention, and that attention is translating into design priorities around maintainability, utility management, and validation. The commercial upside for manufacturers is the chance to turn compliance into a value narrative: chairs and units that are easier to clean, easier to validate, and easier to operate safely can reduce staff burden and support more consistent clinic performance. The risk is that standards and clearance expectations can lengthen development cycles and raise the entry bar for newer players, especially if documentation and testing demands increase faster than internal readiness.
Trend Three: Segment Bifurcation Between Premium Workflow Solutions and Accessible Clinic Equipment
The market is likely to keep splitting along a practical line: premium, workflow-intensive solutions for multi-specialty and higher-complexity settings, and accessible, reliable equipment for expanding clinic networks and cost-sensitive buyers. This bifurcation is not a weakness; it is an opportunity for targeted strategies. Premium players can continue to compete on ergonomics, digital integration, and operatory ecosystems, while more affordable platforms can compete on functional sufficiency, serviceability, and rapid deployment. The key is that each segment requires a different value story, different service commitments, and different cost structures. Companies that try to serve both without clear segmentation may dilute their positioning.
Risks and Uncertainties Worth Watching
Several uncertainties could alter the pace or shape of growth. A shift in reimbursement or clinic investment cycles could affect purchase timing, particularly in smaller practices. Regulatory timelines and standards finalization may change product roadmaps if requirements become more prescriptive than anticipated. Supply and service continuity could become more important if practices increasingly rely on connected or more complex units, since downtime affects clinical throughput more directly in digitalized environments. Finally, if regional competition intensifies in budget segments, margin pressure may force manufacturers to improve efficiency or retreat to narrower niches.
Implications for Decision-Makers
The dental chair market is not simply expanding; it is reorganizing around workflow, compliance, and patient experience. For leaders operating in or adjacent to this space, the priority is to align product strategy and commercial strategy with where value is actually being created.
For Manufacturers and Product Leaders
- Design for configuration breadth without sacrificing setup simplicity. Modular consoles, ambidextrous delivery options, and flexible instrument arrangements are increasingly relevant because they let a single platform serve multiple clinics and procedure mixes.
- Treat infection control and utility management as product identity, not just compliance. Chairs that are easier to service, validate, and maintain can reduce staff burden and create a stronger post-sale value proposition.
- Clarify segment positioning early. Premium workflow ecosystems and affordable clinic-oriented units require different roadmaps, service models, and pricing logic. Blurring the two can weaken both.
For Investors and Strategic Allocators
- Favor companies with defensible ergonomics, workflow fit, and service readiness over undifferentiated feature lists. In a market where the top five players hold less than 30% of revenue, differentiation and repeat purchase economics can matter more than scale alone.
- Watch regulatory and standards developments as signals of future barriers and product requirements. Clearance discipline and standards alignment are becoming part of the competitive toolkit, especially for entrants targeting regulated markets.
- Look for evidence that software, connectivity, and maintenance monitoring are translating into real operational benefits rather than appearing as add-on features. Practical workflow impact is a better indicator of durability than technology language alone.
For Procurement Teams and Practice Operators
- Evaluate total workflow impact, not just purchase price. Chairs that support accessibility, simplify repositioning, and reduce setup time can improve staff efficiency and patient flow in ways that offset higher upfront cost in the right setting.
- Prioritize serviceability and compliance support. Equipment that is easier to clean, validate, and maintain can lower operational risk and reduce training burden, especially in clinics where staff time is constrained.
- Match equipment to procedure mix and clinic model. A chair that fits a surgical-heavy operatory may be a poor fit for a high-throughput examination or orthodontic setting, so configuration should follow clinical reality.
Where to Go Next
The strategic picture is becoming clearer: durable growth in the dental chair market will increasingly depend on how well equipment supports real clinical workflows, regulatory expectations, and patient-facing experience. The companies most likely to capture value are those that can integrate ergonomic design, modular flexibility, compliance discipline, and service readiness into a coherent offering, while also knowing which segment they are really serving. For decision-makers planning investments, product roadmaps, or procurement choices, the next step is to stress-test assumptions against granular segment data, regional dynamics, and company-specific positioning rather than relying on aggregate headlines.
Readers seeking a deeper, segment-level view of the market—including detailed regional and application splits, revenue trajectories across the forecast period, and customized strategic recommendations—can access the full PW Consulting market research report for the dental chair market. The complete analysis provides the finer segmentation and context needed to evaluate investment timing, competitive moves, and product strategy with greater precision.
For detailed analysis of this topic, please visit the official page: Dental Chair Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com