

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Sliding Door Hardware Market 2026: What the 5.2% CAGR and $185.6M Base Really Signal

The Sliding Door Hardware Market: Strategic Trends and Commercial Opportunities Through 2032
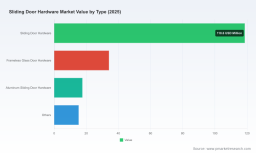
The sliding door hardware market has transitioned from a niche hardware segment into a strategic component of broader building systems procurement. Valued at USD 185.6 million in 2025 and projected to reach USD 261.7 million by 2032, the market expands at a compound annual growth rate of 5.2 percent across the forecast period. Growth is not uniform, nor is it guaranteed. Instead, it reflects a convergence of space optimization demands, evolving building codes, material cost pressures, and competitive repositioning among established manufacturers and regional entrants. For executives and investors navigating building products and architectural hardware portfolios, the market presents a clear signal: value creation will depend on how quickly organizations adapt to specification shifts, supply chain volatility, and changing end-user expectations.
Market Snapshot and Structural Challenges
The market’s trajectory from 2020 through 2025 demonstrates steady expansion, but the pace of growth has quietly shifted. Volume increases in recent years are increasingly tied to specification upgrades rather than pure unit growth. Hardware that once served basic functional requirements now must meet elevated performance thresholds for soft-close behavior, vibration durability, corrosion resistance, and installation efficiency. This shift is reshaping demand patterns across residential and commercial construction, renovation activity, and specialty architectural applications. The market’s moderate concentration, with the top three players accounting for roughly 26.5 percent of revenue and the top five reaching approximately 31.2 percent, indicates a fragmented landscape where regional specialists, performance-focused manufacturers, and cost-competitive suppliers coexist. That fragmentation creates both opportunity and risk. Customers benefit from choice, but specification consistency, quality assurance, and lead-time reliability become harder to manage at scale.
Several structural challenges are shaping the market’s near-term path. First, compliance and testing expectations are rising at the same time cost pressures intensify. Updated industry standards now require enhanced soft-close testing for sliding door hardware in multi-family and commercial buildings, while broader certification frameworks impose stricter vibration durability requirements for bi-fold and pocket systems. These requirements are not optional add-ons; they are becoming gatekeepers to specification approval in higher-value projects. Second, material and cost volatility is compressing margins and forcing suppliers to reconsider sourcing, pricing, and product mix. Stainless steel consumption for hardware components increased year-over-year, driven by stronger demand for corrosion-resistant tracks and rollers in commercial installations. At the same time, aluminum extrusion prices for sliding door tracks rose in early 2025 due to supply chain adjustments in North American manufacturing. The combination of higher input costs and more demanding performance specifications is changing the economics of entry-level versus premium hardware tiers. Third, demand is being reshaped by urban density and space constraints. In high-density residential markets, adoption of space-saving sliding door hardware has accelerated, reflecting a structural shift in how buildings are designed and retrofitted. This trend favors products that balance compact installation footprints with reliable operation, but it also raises the bar for engineering precision and finish consistency.
Cabinet Hardware Market
Core Demand Drivers
Technology Innovation and Performance Expectations
Hardware innovation is increasingly defined by operation quality rather than mechanical novelty alone. Soft-close mechanisms, low-force systems, concealed mounting options, and smoother track integration are moving from premium differentiators into baseline expectations for many residential and commercial applications. The emphasis is shifting toward user experience: consistent sliding motion, reduced noise, easier installation, and finishes that hold up under repeated use. Suppliers that can integrate these performance attributes without inflating assembly complexity are gaining traction in specification-driven projects. Innovation is also visible in system design. Top-hung and bottom-rolling tracks, heavy-duty suspension solutions, and lightweight architectural systems are being refined for distinct use cases, from large commercial doors to high-end residential interiors. The practical implication is that product architecture matters as much as component quality. Systems that simplify installation and reduce on-site adjustment can win preference even when unit pricing is not the lowest.
Policy and Regulatory Environment
Regulatory and standards-driven changes are playing a larger role in shaping hardware selection. Updated standards effective in 2025 mandate enhanced soft-close testing for sliding door hardware in multi-family and commercial buildings, reinforcing the importance of validated performance in shared-use environments. In parallel, recertification expectations for manufacturers include stricter vibration durability testing for bi-fold and pocket systems, raising the compliance burden for suppliers that lack robust testing infrastructure. These developments influence more than product design. They affect specification cycles, project timelines, and the risk profile of sourcing from manufacturers with less proven compliance histories. For decision-makers, the regulatory environment is becoming a filter: hardware that cannot demonstrate consistent performance under newer testing expectations is increasingly difficult to justify in higher-specification projects, especially where liability, maintenance, and user safety are priorities.
Demand-Side Shifts in Construction and Renovation
Demand is being shaped by two overlapping forces: new construction priorities and retrofit behavior. In residential construction, the push toward space-saving layouts is accelerating hardware adoption in high-density markets, where interior footprint efficiency carries greater value. This trend supports demand for sliding solutions that integrate cleanly into compact floor plans and multi-use spaces. In commercial construction and healthcare environments, there is growing interest in hardware that supports durability, ease of maintenance, and specialized functional needs such as lightweight operation or water-managed thresholds. Renovation and retrofit activity further broadens the opportunity set, particularly where older interiors are being updated with modern hardware aesthetics and improved operation. Across these channels, specification decisions are increasingly influenced by total cost of ownership rather than upfront price alone. Installers, architects, and facility operators are paying closer attention to long-term reliability, serviceability, and compatibility with broader building systems.
Supply Chain and Cost Structure Dynamics
Cost structure is becoming a strategic variable rather than a static backdrop. Raw material trends are reshaping pricing logic across the hardware segment. Stainless steel demand for corrosion-resistant components has increased, reflecting stronger commercial requirements and a preference for hardware that withstands harsher environments. Aluminum extrusion pricing pressure, meanwhile, has affected track manufacturing economics in certain regions, especially where supply chain adjustments have tightened availability or raised input costs. These dynamics matter because sliding door hardware is not a purely commoditized category. Performance differentiation, finish quality, load capacity, and testing compliance all influence willingness to pay. Suppliers that can manage material exposure through product design, sourcing strategy, or value-tier segmentation are better positioned to protect margins while still meeting specification requirements. The broader lesson is that cost management and product strategy must move together; otherwise, price competition can quickly erode differentiation.
Competitive Landscape and Leading Strategies
The competitive field is broad, with manufacturers positioned around different value propositions rather than competing solely on price. Several patterns stand out when examining how leading companies are competing.
One clear axis of differentiation is application specialization. Some manufacturers focus on comprehensive residential and commercial sliding systems with emphasis on smooth operation and durability, offering both top-hung and bottom-rolling track options. Others concentrate on heavy-duty commercial and industrial systems designed to support larger doors with robust suspension and track solutions. A third group targets precision hardware for furniture and architectural applications, including low-force soft-close systems and concealed options for high-end residential projects. This specialization matters because it shapes specification eligibility. A supplier known for heavy-duty commercial systems may be the natural fit for large-scale installations, while a precision-focused manufacturer may win preference in interior design-driven residential work.
Regional manufacturing and supply positioning is another competitive lever. North American-made pocket door and exposed barn door hardware systems, including frame kits and weather-resistant options, appeal to customers prioritizing domestic sourcing and faster fulfillment. In contrast, cost-effective sliding hardware solutions for residential and commercial applications have gained attention in markets where price sensitivity remains high and specification requirements are less performance-intensive. The presence of both domestic and international suppliers creates a layered market where customers can balance cost, lead time, compliance, and finish quality according to project needs.
Recent company actions illustrate how the landscape is evolving in practice. In August 2025, one major supplier released an updated catalog with streamlined sliding door hardware offerings, enhanced quality, and reduced lead times across bypass, bi-fold, barn door, and pocket door applications. That move signals a focus on specification clarity and fulfillment reliability, both of which matter in project-driven purchasing. In March 2025, another manufacturer introduced new healthcare sliding systems, lightweight sliding platforms, and water return thresholds for architectural applications, reflecting a strategy built around environment-specific solutions and specialized building needs. Earlier in the year, a major industry participant demonstrated expanded operating convenience and safety features for aluminum sliding windows and doors at a leading trade show, underscoring the broader industry push toward usability and safety-enhanced hardware.
Together, these developments point to a market that is not simply consolidating around a few dominant players. Instead, it is differentiating around performance tiers, application fit, and service reliability. Market concentration remains moderate, leaving room for regional specialists and targeted entrants, but the bar for competitive relevance is rising. Manufacturers that can combine tested performance, predictable lead times, and clear application alignment are gaining an advantage. Those competing primarily on price without differentiated quality or compliance support face growing pressure, especially as specifications become more demanding and installation expectations increase.
For customers and investors, the evolving landscape carries a practical message: supplier selection is increasingly a risk-management decision. A hardware partner’s ability to meet updated testing expectations, maintain consistent material quality, and deliver on schedule can be as important as the product’s nominal feature set. In fragmented markets, reputation for reliability often becomes the tie-breaker in specification choices.
Forward Outlook: Three Trends Shaping 2026–2032
1. Specification-Led Growth in Performance-Tiered Hardware
Over the next several years, growth is likely to be increasingly driven by performance-tiered specification rather than undifferentiated volume expansion. As soft-close expectations, vibration durability requirements, and corrosion resistance demands become more entrenched in commercial and multi-family projects, hardware suppliers will need to demonstrate validated performance in order to remain eligible for higher-value specifications. This creates opportunity for manufacturers that can clearly segment product lines by performance level, application, and testing compliance. It also raises the stakes for suppliers whose portfolios blur the line between economy and premium tiers without clear differentiation. The commercial opportunity lies in aligning product architecture with specification categories, making it easier for architects, procurement teams, and installers to match hardware to project requirements without added risk.
PW Consulting Automotive & Machinery Research Center
2. Space Optimization as a Sustained Demand Engine
Urban density and interior efficiency are likely to remain powerful demand drivers, especially in residential construction and retrofit activity. As layouts become more compact and multi-functional, sliding hardware that supports space-saving designs without sacrificing operation quality will continue to find favor. Adoption momentum in high-density markets suggests that this is not a temporary cycle but a structural shift in building design priorities. For manufacturers, the opportunity is to develop systems that balance compact footprints with reliable load handling, clean finishes, and straightforward installation. For investors and strategic planners, the implication is that demand tied to space optimization is likely to be more resilient than demand dependent solely on cyclical construction volume.
3. Supply Chain Discipline and Material Strategy as Competitive Advantages
Input cost volatility and material availability will continue to shape competitive outcomes. Stainless steel demand for corrosion-resistant components and aluminum extrusion pricing pressures are reminders that hardware economics are sensitive to both material selection and sourcing geography. Over the forecast period, suppliers that manage material exposure through design efficiency, segmented sourcing, or strategic inventory planning are likely to protect margins more effectively than those reacting mainly through price adjustments. This trend also reinforces the importance of transparent product positioning. As costs fluctuate, customers will increasingly value suppliers that can explain trade-offs clearly, maintain consistent quality, and reduce installation rework. In that environment, supply chain discipline becomes a visible competitive advantage rather than an internal operational detail.
These trends do not develop in isolation. Specification requirements, demand-side space optimization, and supply chain pressures are interacting to reshape where value is created in the market. The most resilient players will be those that treat performance, compliance, and operational reliability as an integrated strategy rather than separate workstreams. At the same time, uncertainty remains. Construction cycles can shift, regional supply conditions can change, and standards evolution may accelerate faster than product development in some segments. The market’s direction is positive, but the path will reward preparation more than passive participation.
Actionable Implications for Decision-Makers
For manufacturers and product strategists, the priority is to sharpen application alignment and performance transparency. Product portfolios should make it easier for customers to identify which systems are suited to residential, commercial, healthcare, or retrofit use without forcing them to infer fit from generic catalogs. Where compliance expectations are rising, testing documentation and performance validation should be treated as selling points, not afterthoughts. Suppliers should also review material exposure and cost structure with a focus on long-term margin resilience, particularly where stainless steel and aluminum usage is tied to commercial specifications. Finally, lead-time reliability and catalog clarity can be leveraged as differentiation, especially in project-driven purchasing where delays and specification ambiguity carry real costs.
For investors and corporate development teams, the market offers a case for targeted engagement rather than broad exposure. Moderate concentration and clear application segmentation suggest that value may be found in suppliers with strong positioning in specific performance tiers or end-use environments, particularly where they combine compliance readiness with stable fulfillment. Due diligence should pay close attention to testing capability, material sourcing resilience, and the ability to serve higher-specification commercial and multi-family projects. Companies competing only at the lowest price point may face margin compression as standards and material costs rise, while suppliers with credible performance differentiation and application focus are better positioned to defend value.
Drawer Slides Market
For procurement teams, architects, and specification decision-makers, the practical takeaway is to evaluate hardware choices with a broader lens than unit price alone. Updated testing expectations, vibration durability requirements, corrosion resistance needs, and installation efficiency should be weighted alongside cost, especially in commercial and multi-family projects where long-term performance and compliance risk matter more. Supplier reliability, documentation quality, and reputational consistency can reduce specification risk and installation friction. Where projects involve specialized environments such as healthcare or high-traffic commercial settings, environment-specific hardware solutions may deliver better total outcomes than generic alternatives.
Across these roles, the common theme is that the market is becoming more specification-sensitive, more compliance-dependent, and more operationally demanding. That environment increases the value of detailed, current intelligence. Segmentation nuances, regional dynamics, material trends, standards changes, and competitor moves all influence how opportunities should be evaluated and where risk is concentrated. For organizations that need to translate these shifts into procurement strategy, product roadmap decisions, or investment positioning, broader research coverage can provide the granularity needed to move from directional insight to precise action. A full research report can support that next step by offering deeper segmentation detail, regional comparisons, and customized considerations aligned to specific business objectives.
For detailed analysis of this topic, please visit the official page: Sliding Door Hardware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com