

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Cables Market Outlook 2026-2032: Why a 6.3% CAGR Signals Strategic Shifts

Navigating the Cables Market: Strategic Trends, Challenges, and Commercial Opportunities Through 2032
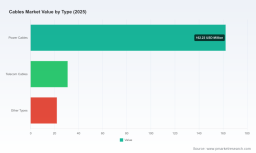
The global cables market stands at a critical inflection point. Valued at $215.0 million in 2025 and projected to reach $357.35 million by 2032, the sector is tracking a compound annual growth rate of 6.3 percent across the forecast horizon. This trajectory reflects more than steady industrial expansion; it signals a structural realignment driven by energy transition investments, digital infrastructure build-outs, and shifting supply chain dynamics. For executives and investors, the opportunity lies not in treating cables as a commoditized utility input, but in recognizing how technology differentiation, regulatory fragmentation, and raw material volatility are redrawing competitive boundaries.
Historical data from 2020 through 2025 shows consistent upward momentum, with revenues climbing from $163.15 million to the current baseline. The acceleration into 2026 and beyond is unlikely to be linear. Capacity expansions, product innovations, and policy interventions are compressing timelines for adoption while simultaneously raising the bar for operational resilience. Understanding where value is being created—and where margin compression looms—requires looking past aggregate figures and examining the forces shaping segment performance, competitive positioning, and procurement strategies.
Market Snapshot and Core Challenges
The cables sector has matured into a multi-layered ecosystem where power distribution, telecommunications, and specialized industrial applications coexist but operate under distinct economics. Power transmission and energy distribution continue to anchor overall demand, while telecom infrastructure and data center connectivity drive higher-growth, specification-driven segments. The market remains relatively fragmented at the top, with the top three players holding a combined share of 24.6 percent and the top five reaching 26.2 percent. This concentration level leaves substantial room for regional specialists, niche innovators, and vertically integrated suppliers to compete on technology, service, and localization rather than scale alone.
Several structural challenges are testing the industry’s ability to translate demand growth into sustainable profitability.
- Raw material price volatility is reshaping cost structures. Copper has surged to approximately $12,046 per metric ton on global exchanges, with aluminum, PVC, and XLPE compounds following similar upward trajectories. The pressure stems from geopolitical tensions, trade tariff adjustments, and surging demand from data centers, electric vehicle infrastructure, and renewable energy projects. Manufacturers face difficult choices between absorbing input costs, passing them through to customers, or redesigning products to reduce material intensity.
- Regulatory fragmentation is creating uneven operating environments. In the United States, Proclamation 10895 adjusted aluminum imports with duties on aluminum wire rod reaching 25 percent ad valorem, implemented through March 2025. The Department of Commerce subsequently imposed 25 percent duties on products from China under HTS subheading 8544.49.90, covering aluminum wire and cable without connectors. A presidential proclamation from July 30, 2025, recommended an immediate universal 30 percent import duty on semi-finished copper products, with phased tariffs on refined copper beginning at 15 percent in 2027 and escalating to 30 percent in 2028. These measures alter landed costs, sourcing strategies, and competitive dynamics across regions.
- Infrastructure delivery bottlenecks and specification complexity are lengthening project cycles. As utilities, hyperscalers, and industrial operators demand higher performance, tighter sustainability criteria, and integrated connectivity, suppliers must navigate longer qualification processes, customized engineering requirements, and tighter logistics windows. The result is a market where speed to deploy and technical reliability increasingly separate leaders from followers.
For decision-makers, these challenges are not merely headwinds; they are filters. Companies that treat cost volatility as a purely tactical procurement issue will find themselves exposed to margin erosion and supply disruptions. Those that embed material strategy, regulatory foresight, and specification leadership into their operating models can convert pressure into differentiation.
Key Drivers Reshaping the Market
The growth trajectory is being pulled by a combination of technological advancement, policy direction, demand-side behavior, and supply chain recalibration. Each factor reinforces the others, creating pockets of accelerated opportunity alongside zones of uncertainty.
Technology Innovation and Performance Breakthroughs
Product innovation is moving beyond incremental improvements to structural changes in how cables are designed, manufactured, and deployed. Recent developments illustrate the pace of change. In October 2025, Prysmian Group introduced BendBrightXS 160µm single-mode optical fibre, recognized as the world’s first of its kind, enabling tighter bend radii and higher density in space-constrained environments. In May 2025, Nexans launched industrial cable solutions engineered to improve sustainability and energy efficiency, targeting reduced losses and longer service life. Belden Inc. followed with its 10GXM13 Category 6A Cable, a TIA-compliant small-diameter solution designed for high-performance data environments where space and airflow matter. Earlier, in June 2025, The Siemon Company introduced Smart Building COMPLETE, a unified connectivity and cabling solution that integrates multiple subsystems into a single architectural approach.
These launches reflect a broader shift: cables are no longer passive conduits but active enablers of system-level efficiency. In data centers, smaller diameters and higher bend tolerance translate into better rack utilization and lower cooling overhead. In industrial and smart building contexts, integrated connectivity reduces installation complexity and lifecycle maintenance. For suppliers, the ability to pair material science with application engineering is becoming a core competitive lever, not a secondary service offering.
Policy and Regulatory Environment
Government policy is acting as both an accelerator and a barrier, depending on region and product class. Energy transition mandates, grid modernization programs, and broadband expansion initiatives are creating sustained demand for high and medium voltage power cables, submarine and offshore wind solutions, and fibre-based telecom infrastructure. At the same time, trade policy is reshaping input costs and cross-border sourcing. The layered tariff actions on aluminum wire rod, aluminum wire and cable from China, and semi-finished and refined copper products are altering the economics of imported inputs and finished goods.
The regulatory environment rewards companies that can localize production, diversify supplier bases, and anticipate duty impacts before they affect quotation validity or project margins. For multinational players, regional manufacturing footprints and flexible procurement strategies are increasingly tied to bidding credibility. For smaller suppliers, understanding duty structures and qualification pathways can determine whether they can serve specific public or utility tenders at all.
Fiber Optic Cables Market
Demand-Side Shifts in Enterprise and Consumer Behavior
End-user behavior is changing in ways that ripple through cable specifications and volume patterns. Data center expansion continues to drive demand for high-bandwidth, low-latency connectivity, pushing higher specifications for both power and telecom cabling within constrained physical footprints. Electric vehicle charging networks and renewable energy connections are expanding the footprint of medium and high voltage distribution, often in locations where grid reinforcement is urgently needed. Industrial automation and smart building adoption are increasing the premium on integrated, reliable connectivity that can support analytics, monitoring, and modular reconfiguration.
These demand shifts favor suppliers that can offer application-tailored solutions, rapid technical support, and lifecycle services rather than commodity product sales alone. Procurement teams are increasingly weighing total cost of ownership, energy efficiency, and installation speed alongside unit price, especially in capital-intensive projects where downtime or rework carries significant cost.
Supply Chain and Cost Structure Dynamics
Material costs, logistics, and manufacturing capacity are interacting to reshape the supply side. Copper and aluminum price movements, combined with PVC and XLPE compound trends, are pressuring gross margins and forcing경영진의 재고 전략, 가격 계약 구조, 및 제품 설계 재평가를 요구하고 있습니다. 동시에, Prysmian Group의 2025 년 5 월 산업용 케이블 생산 능력 확장과 같은 활동은 고성능 세그먼트에서 용량 제약이 시장 접근의 장벽이 될 수 있음을 시사합니다.
Supply chain resilience is now a strategic variable. Companies are diversifying sourcing, increasing safety stock for critical inputs where feasible, and investing in manufacturing flexibility to switch between specifications without losing efficiency. The companies that can maintain consistent quality while adapting to input volatility are likely to secure preferential positions in utility, industrial, and hyperscaler supply chains, where reliability often outweighs marginal price differences.
Competitive Landscape and Leading Strategies
The market’s competitive structure is evolving through a mix of scale-based expansion, technology specialization, and application-focused positioning. The leading players are not competing on a single axis; they are building distinct value propositions that align with where they can win on engineering, localization, and service.
Prysmian Group, headquartered in Milan, Italy, continues to emphasize high and medium voltage cables, optical fibre cables, and energy transition solutions spanning renewable and smart grid infrastructure. Its May 2025 capacity expansion for high and medium voltage industrial cables, paired with the October 2025 BendBrightXS optical fibre introduction, illustrates a dual strategy: scaling core power distribution capabilities while pushing fibre innovation for dense, high-performance environments.
Nexans, based in Paris, France, focuses on high voltage, medium voltage, and low voltage cables for energy distribution, offshore wind, and industrial applications. Its January 2025 launch of industrial cable solutions centered on sustainability and energy efficiency signals a positioning around lifecycle performance and regulatory-aligned design, appealing to utilities and industrial buyers facing efficiency mandates and carbon considerations.
NKT A/S, headquartered in Copenhagen, Denmark, concentrates on high voltage, medium voltage, and low voltage power cables, submarine cables, and offshore wind solutions. Its portfolio aligns with the growing need for long-distance, high-reliability connections in marine and wind environments, where qualification rigor and installation expertise create meaningful barriers to entry.
Worldwide Rolling Stock Cables Market
Fujikura Ltd., from Tokyo, Japan, offers power transmission cables, optical transmission systems, and electronic materials. Its combination of power and optical capabilities positions it to serve projects where energy and data infrastructure intersect, particularly in regions where integrated solutions reduce coordination risk.
LS Cable & System, based in Anyang, South Korea, covers energy, telecommunication, and industrial cables, providing a broad domestic and export platform that can adapt to varied regional specifications. Leoni AG, from Nuremberg, Germany, specializes in automotive wiring systems and harnesses, competing in a demand environment shaped by vehicle electrification and complex onboard connectivity requirements.
PW Consulting
In the interconnect and specialized connectivity space, Amphenol Corporation, headquartered in Wallingford, Connecticut, USA, provides interconnect and sensor solutions for data communications, industrial, and automotive applications. TE Connectivity, based in Galway, Ireland, delivers connectivity and sensor solutions across industrial, automotive, and aerospace sectors. Belden Inc., from St. Louis, Missouri, USA, focuses on networking, industrial automation, and smart building cabling systems, with its 10GXM13 Category 6A launch reinforcing a focus on compact, high-performance data cabling.
The landscape is shifting along several dimensions. First, consolidation pressure is rising in segments where scale, compliance, and global service networks matter, but fragmentation persists where localization, niche specifications, and rapid innovation can win. Second, differentiation is moving from pure volume to performance, sustainability, and integration. Third, new entrants and specialized players are carving out roles in high-growth subsegments such as data center connectivity, EV infrastructure, and offshore wind, where application knowledge and qualification speed can outweigh incumbency.
For buyers and investors, the practical implication is that supplier evaluation must be segment-specific. A company that leads in high voltage offshore solutions may not be the best fit for compact data center cabling, and vice versa. Competitive advantage is increasingly tied to the ability to match technical capability with application context, regulatory awareness, and delivery reliability.
Future Trends and Commercial Implications for 2026-2030
Looking ahead three to five years, several trends are likely to shape where growth concentrates and how value is captured.
Trend 1: Energy-Connected Infrastructure Will Anchor Demand, While Digital Connectivity Drives Specification Upgrades
Power transmission and distribution will continue to form the demand backbone, reinforced by renewable integration, grid modernization, and EV charging networks. At the same time, telecom infrastructure and data center build-outs will push higher specifications for bandwidth, density, and energy efficiency. The commercial opportunity lies in solutions that address both dimensions: cables and connectivity that support power delivery and data performance within the same constrained environments. Suppliers that can offer integrated engineering support and lifecycle optimization will be better positioned to win complex projects and reduce competitive substitution risk.
Trend 2: Material Strategy and Trade Policy Will Become Core Competitive Variables
With copper near $12,046 per metric ton and aluminum, PVC, and XLPE following upward pressure, raw material management will move from procurement desk work to strategic planning. Tariff actions on aluminum wire rod, aluminum wire and cable from China, and phased duties on refined copper will continue to influence sourcing decisions, quotation structures, and regional manufacturing logic. Companies that build flexible input strategies, consider material substitution where technically viable, and price with regulatory foresight will protect margins more effectively. For investors, exposure to firms with diversified sourcing, localized production, and engineering-led product design is likely to offer greater resilience than pure volume players.
Trend 3: Sustainability, Efficiency, and Integration Will Redefine Procurement Criteria
Sustainability and energy efficiency are transitioning from nice-to-have attributes to evaluation criteria in utility, industrial, and building projects. Solutions such as lower-loss industrial cables, compact high-performance data cabling, and unified smart building connectivity are gaining traction because they reduce installation complexity, improve operational efficiency, and align with broader decarbonization goals. The risk is that specifications become more fragmented and qualification cycles lengthen, especially where multiple standards and sustainability benchmarks must be satisfied. Suppliers that invest early in credible efficiency claims, documentation, and testing will shorten sales cycles and build trust with specification-driven buyers.
Potential uncertainties remain. Trade policy could shift further, altering input costs and competitive positioning across regions. Demand tempo may vary by sector, with data center and EV infrastructure potentially outpacing other applications in certain periods. Capacity additions in high-performance segments could create temporary constraints or, conversely, lead to pricing pressure if supply outpaces project Pipelines. Monitoring these dynamics will be essential for timing capacity decisions, pricing strategies, and partnership choices.
Strategic Actions for Decision-Makers
The market’s direction is clear enough to act on, but the specifics matter. Different stakeholders face different leverage points.
- For manufacturers and suppliers, prioritize application-aligned innovation over broad commodity expansion. Invest in product designs that reduce material intensity, improve installation efficiency, or enable higher performance in constrained spaces. Align manufacturing flexibility with the segments where qualification speed and technical support create the strongest barriers to substitution. Build input and tariff monitoring into quotation and pricing processes so that margin assumptions reflect the current regulatory and commodity environment rather than historical averages.
- For investors, evaluate exposure by segment and capability rather than by aggregate market growth alone. Companies with differentiated positions in high voltage, offshore wind, optical fibre innovation, or integrated connectivity are likely to face different competitive dynamics than undifferentiated volume suppliers. Assess whether a company’s sourcing strategy, manufacturing footprint, and technical service model can withstand material volatility and shifting trade policy. In high-growth subsegments, look for evidence of specification leadership, repeat project wins, and the ability to convert innovation into documented efficiency or performance benefits.
- For procurement and buying organizations, broaden evaluation criteria beyond unit price. Include total cost of ownership, energy efficiency, installation complexity, qualification timelines, and supply continuity. Where projects involve both power and data connectivity, consider suppliers that can coordinate across domains or provide integrated solutions that reduce interface risk. Build tariff and material price scenarios into long-term contracting strategies, and consider dual-sourcing or regional supply options where qualification allows, to reduce exposure to single-point disruptions.
The cables market will continue to expand, but the distribution of value will be uneven. Segments tied to energy transition, digital infrastructure, and integrated connectivity are likely to reward suppliers and buyers who act on specification, resilience, and total cost logic. Those who depend on commoditized positioning without differentiating on performance, sourcing agility, or application support will face tougher margins and more intense competition. Timely, detailed intelligence on segment dynamics, regulatory developments, and supplier capabilities can sharpen these decisions and reduce the risk of mis-timed investments or procurement choices. For leaders seeking deeper segment breakdowns, regional detail, and tailored recommendations, the full research report provides the granular data and structured analysis needed to translate these trends into concrete strategy.
For detailed analysis of this topic, please visit the official page: Cables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com