

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Portable Power Bank Market 2026: Why 9.6% CAGR and Asia Pacific Dominance Reshape Strategy

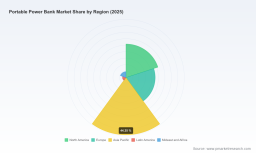
Portable Power Bank Market: Strategic Shifts and Commercial Pathways Through 2032
The global market for portable power banks has matured beyond its early-stage expansion into a sophisticated segment defined by rapid capacity escalation, charging protocol standardization, and intensifying regulatory scrutiny. Spanning 2020 through 2025, the sector grew from approximately 12.15 billion USD to 18.6 billion USD, reflecting sustained demand across consumer electronics and expanding commercial applications. Forward projections through 2032 place the market at 35.6 billion USD, guided by a compound annual growth rate of 9.6 percent. This trajectory signals more than incremental volume growth; it indicates a structural transition where power banks are becoming higher-performance, safety-regulated, and increasingly integrated with broader mobility and energy ecosystems. The convergence of battery engineering advances, shifting travel norms, raw material dynamics, and evolving compliance frameworks is reshaping competitive positioning and creating distinct commercial pathways for manufacturers, investors, and procurement teams.
At this scale, the market no longer rewards generic capacity claims. Differentiation now hinges on output architecture, charging efficiency, thermal management, material compliance, and ecosystem alignment with flagship device standards. The competitive field remains moderately concentrated, with the top three players accounting for roughly 37.6 percent of revenue and the top five reaching about 50 percent. Such concentration suggests room for both consolidation and targeted disruption, particularly as new entrants leverage specialty form factors, ruggedization, or certified wireless protocols to capture underserved segments.
PW Consulting
Market Context and Structural Challenges
The current phase of the market is characterized by decoupling levels of power delivery from physical portability, alongside mounting pressure to satisfy tighter safety and transport requirements. This creates several operational and strategic challenges that decision-makers must navigate.
Capacity and Output Escalation Under Physical Constraints
Consumers and professional users increasingly expect power banks that can charge high-draw laptops, tablets, and multi-device setups at speeds approaching native wall adapters. The result is a race toward higher wattage and larger cell configurations without proportionally increasing bulk or weight. Thermal management, cell balancing, and conversion efficiency become critical engineering constraints as output targets climb. Products that fail to balance performance with safe operating temperatures or that compromise on sustained output under load risk losing credibility in both consumer and commercial channels.
Regulatory Tightening Across Safety and Transport
Compliance is shifting from a peripheral concern to a core product design parameter. New mandatory national standards for portable power banks now require stricter battery safety validation under abusive conditions and establish a recommended service life, with a transition window that forces product redesigns and supply chain adjustments. Simultaneously, air transport rules have become more restrictive. Passenger limits now cap power banks at two units per traveler, prohibit onboard recharging, and mandate individually protected carry-on storage. For logistics and distribution, shipment requirements now specify a lower state of charge for air transport under designated dangerous goods provisions. These rules affect packaging, inventory planning, freight costs, and end-user behavior, particularly for travel-heavy and corporate deployment models.
Material Volatility and Export Policy Uncertainty
Battery pack economics remain exposed to fluctuations in lithium, cobalt, and nickel markets, with average pack costs spanning a broad range in 2026. Beyond commodity pricing, export controls on lithium battery cells, graphite anode materials, and related equipment have introduced new friction in cross-border procurement and manufacturing footprints. Companies that rely on concentrated sourcing or single-region supply chains face elevated risk of disruption, customs complexity, and cost volatility. This environment rewards diversified sourcing strategies, inventory buffering where justified, and proactive engagement with component suppliers that can demonstrate compliance and continuity.
Core Drivers Shaping Demand and Supply
Technology Innovation and Charging Protocol Maturation
A defining driver is the rapid standardization and certification of wireless charging protocols aligned with major device ecosystems. Industry activity now includes Qi 2.2-certified wireless power banks, magnetic alignment improvements, and higher-wattage wired outputs designed for laptop-class devices. These developments are not merely feature upgrades; they alter the value equation by enabling cleaner, cable-free workflows and supporting flagship devices that prioritize magnetic attachment and intelligent power negotiation. Higher-output models reaching 240W and multi-cell architectures for laptop charging broaden the addressable use case from phone topping to full work-session power delivery. The strategic implication is that protocol compatibility and intelligent charging management are becoming table stakes for premium positioning, while engineering teams must also ensure that higher power levels do not compromise reliability or user safety.
Regulatory and Compliance-Led Redesign Cycles
Policy and standards activity is shaping product roadmaps directly. Mandatory safety testing for abusive conditions and the introduction of a recommended service life create a compliance catalyst that favors manufacturers with robust validation capabilities and mature quality systems. The transport restrictions also change demand patterns: travelers and enterprises deploying field equipment must plan storage and carriage more carefully, which can increase demand for rugged, clearly labeled, and safely packaged units. Companies that internalize these requirements early can turn compliance into a differentiator by documenting service life expectations, providing clear handling guidance, and aligning packaging with transport rules. In effect, regulation is acting as both a barrier and a filter, elevating the importance of engineering discipline and documentation.
Demand-Side Behavior and Use-Case Expansion
Consumer behavior continues to tilt toward always-on connectivity, with users carrying multiple devices and expecting consistent battery availability through long travel days, remote work, and outdoor activities. At the same time, commercial and industrial applications, while smaller in relative terms, are growing in importance for field operations, mobile workstations, and backup power in settings where grid reliability is variable. This diversification expands the product matrix beyond single-use consumer chargers. It also encourages hybrid designs that combine high capacity with ruggedization, solar compatibility for extended off-grid use, and clear labeling for safe transport. For marketers and product planners, the opportunity lies in matching form factor and feature sets to specific lifestyles and workflows rather than competing solely on sticker capacity.
Power Banks Market
Supply Chain Reconfiguration and Cost Structure Pressure
The cost environment reflects a combination of raw material fluctuations and policy-driven sourcing shifts. Battery pack economics vary widely depending on cell chemistry, packaging, and certification requirements, and volatility in lithium, cobalt, and nickel markets can quickly alter margin assumptions. Export controls on critical battery materials and processing equipment add another layer of complexity to procurement planning and manufacturing location decisions. Firms that can secure stable cell supply, diversify anode and cathode sourcing, and maintain buffer inventory for high-demand SKUs gain an advantage in both cost predictability and launch readiness. There is also a growing incentive to design for repairability, replaceable cells where feasible, and modular components that can extend service life and align with emerging sustainability expectations.
Competitive Landscape and Strategic Positioning
Established Leaders and Feature-Led Differentiation
Several companies are carving distinct positions by aligning product architectures with clear user needs. One prominent consumer-focused player emphasizes high-output models such as a 20,000mAh 220W option alongside ultra-slim 10,000mAh designs with fast charging and magnetic wireless variants. This portfolio strategy addresses a broad range of portability and performance requirements, allowing the brand to serve users who prioritize pocketable convenience as well as those who need laptop-grade output. Another fast-moving competitor has pushed into certified wireless territory with a 25W Qi 2.2-aligned model, signaling a commitment to protocol leadership and compatibility with next-generation device ecosystems. A separate line of high-capacity laptop-oriented models up to 25,000mAh with strong magnetic and Qi2/MagSafe support reinforces the trend toward powering full device portfolios rather than single phones.
In the specialty and rugged segment, a US-based outdoor brand combines compact USB power banks with rugged Flip-series designs that integrate solar compatibility, targeting travelers, campers, and field users who value durability and off-grid options. Another rugged-focused offering emphasizes military-grade waterproof designs across 5,000mAh to 15,000mAh capacities for camping and adventure use. These niche positions illustrate how differentiated durability, environmental sealing, and solar integration can command premium value in specific use cases, even as mainstream segments compete on speed, capacity, and wireless compatibility.
Recent Industry Moves and the Importance of Timing
Recent product and event activity underscores how fast the field is moving. A major international brand introduced next-generation power banks at a prominent consumer technology event, including a 27,000mAh model with 240W output, demonstrating continued escalation in both capacity and power delivery. Around the same period, another competitor launched a 25W wireless model certified to the latest Qi 2.2 specification, marking an early move in protocol-aligned wireless charging. On the industry coordination side, a major power bank conference in Shenzhen gathered speakers from cell suppliers and material companies, highlighting the interconnected nature of cell technology, materials, and product design. For competitive strategy, these developments matter because they compress decision cycles. First-mover advantage in certified wireless, high-wattage laptop charging, or rugged solar-integrated designs can shape channel preferences and retailer shelf positioning before the broader market catches up.
USB Portable Battery Market
Market Structure Evolution
The market is exhibiting both consolidation pressure and segmentation opportunity. Moderate concentration among leading players indicates the presence of scale benefits in brand reach, channel relationships, and engineering investment. At the same time, the proliferation of specialized use cases—ultra-slim travel models, high-output laptop chargers, rugged outdoor units, and certified wireless options—creates space for targeted entrants and for incumbents to expand through subcategory depth. The likely trajectory over the next few years is a layered competitive structure: broad-line brands compete across capacity and output tiers, while specialists capture margins in durability, protocol leadership, or outdoor and field-use niches. M&A and channel partnerships may accelerate as larger players seek to fill feature gaps or acquire rugged and specialty portfolios. New entrants that can demonstrate credible safety validation, efficient thermal design, and clear ecosystem compatibility will have the best chance of breaking through in a crowded field.
Strategic Outlook: Three Trends to Watch
Higher Power, Smarter Charging, and Ecosystem Alignment
Over the next three to five years, the market will likely see continued escalation in output levels and more sophisticated charging negotiation between power banks and devices. Magnetic attachment, protocol certification, and intelligent power management will become standard expectations in premium tiers. This creates commercial opportunities for brands that can deliver reliable high-wattage performance without sacrificing portability or safety. The risk is that feature claims outpace real-world reliability; products that cannot sustain high output, manage heat, or negotiate power properly with diverse devices will face credibility and return-rate challenges. Winners will pair bold specifications with validated performance and clear user guidance.
Compliance as a Design Imperative and Sales Enabler
Safety standards and transport rules will increasingly shape product architecture, packaging, and distribution logistics. Companies that design for stricter abusive-condition testing, articulate service life expectations, and align packaging with carriage requirements will reduce downstream friction and build trust with retailers and corporate buyers. There is also an opportunity to use compliance documentation and clear handling instructions as selling points, especially for travel, corporate, and field-deployment customers. The uncertainty lies in the pace and variation of regional requirements, which can create uneven launch timing and added engineering overhead for global portfolios.
Supply Chain Diversification and Material-Resilient Design
Material cost volatility and export policy shifts will continue to influence sourcing strategy and product economics. Firms that build multi-source cell supply, qualify alternative anode and cathode inputs where feasible, and maintain flexible manufacturing footprints will be better positioned to manage cost swings and continuity risk. Design choices that improve material efficiency, support serviceability, and reduce dependency on constrained components can also provide long-term resilience. The main risk is over-concentration in any single region or supplier for critical cells and materials, which can expose launches and inventory plans to disruption. Strategic sourcing, combined with transparent cost modeling, will be a key capability for maintaining margins as the market scales.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Leaders
- Prioritize validated performance over headline capacity. Invest in thermal design, sustained output testing, and protocol certification that matches the device ecosystems your customers use most.
- Build compliance into the product lifecycle early. Align engineering, packaging, and documentation with emerging safety and transport requirements to smooth launches and reduce channel friction.
- Diversify cell and material sourcing while buffering critical SKUs. Scenario-plan for commodity volatility and policy changes, and consider design choices that improve material efficiency and serviceability.
For Investors and Strategic Capital Allocators
- Focus on differentiation that commands retention and margin, such as certified wireless leadership, laptop-class output, rugged field-use reliability, and clear compliance credentials.
- Watch for consolidation and partnership activity as scale players fill feature gaps and specialty brands seek broader distribution. Evaluate whether target companies have defensible engineering, supply resilience, and channel access.
- Assess exposure to material and policy risk in the value chain. Companies with diversified sourcing, transparent risk management, and adaptive manufacturing footprints are better positioned for the next growth phase.
For Procurement and Enterprise Buyers
- Specify performance and safety criteria that match real-world use, including sustained output under load, thermal behavior, transport-compliant packaging, and clear service-life documentation.
- Align purchasing with travel and deployment rules. Account for passenger limits, carry-on storage requirements, and shipment state-of-charge rules when planning inventory and field kits.
- Evaluate supplier continuity and compliance readiness, not just unit price. Reliable certification, documented testing, and flexible sourcing reduce operational risk in distributed teams and travel-heavy operations.
The portable power bank market is entering a phase where performance, compliance, and supply resilience converge to determine competitive outcomes. For organizations ready to move quickly, the most valuable next step is to secure detailed segmentation, regional dynamics, and company-level scenario data that can translate these broad trends into product roadmaps, sourcing plans, and investment theses. A comprehensive research report with granular segmentation and customized recommendations can support that work, helping teams convert market momentum into executable strategy.
For detailed analysis of this topic, please visit the official page: Portable Power Bank Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com