

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Optical Isolators Market: Why 5.38% CAGR Reshapes Key Regions & Applications

Optical Isolators Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The optical isolators market has matured into a foundational component segment for photonics-intensive industries, driven by the non-negotiable need to suppress back-reflections and protect laser systems across wavelength ranges from ultraviolet to near-infrared. Over the historical period from 2020 to 2025, the market expanded from approximately 535.88 million to 692.91 million, reflecting steady compounding growth fueled by telecommunications infrastructure expansion, industrial laser adoption, and medical photonics applications. The forecast horizon from 2026 to 2032 projects continued expansion toward roughly 1001.42 million, with a sustained CAGR of 5.38 percent. This trajectory signals a market that is no longer experiencing explosive disruption but rather consolidating around performance differentiation, supply resilience, and integration efficiency.
Beneath the aggregate numbers, the industry is navigating a cluster of structural challenges that will shape competitive positioning through the end of the decade. First, raw material dependency has emerged as a critical vulnerability. Critical inputs for Faraday rotators, including yttrium iron garnate and rare earth elements such as terbium and dysprosium, face geopolitical sourcing risks and supply chain volatility. Supply interruptions at Japanese YIG factories have already extended single-stage optical isolator lead times to over 14 weeks, with an estimated 14 percent annual cost increase projected through 2026. This concentration of material risk forces manufacturers and buyers to rethink inventory philosophy, qualification pathways, and supplier diversification strategies.
Worldwide Polarization Maintaining Fiber Isolator Market
Second, the market is experiencing a performance-versus-footprint tension. Applications in data centers, industrial laser processing, and military and aerospace systems increasingly demand higher isolation, broader wavelength coverage, and greater power handling, while simultaneously pushing for reduced size, weight, and power consumption. Free-space and fiber-based isolators must now coexist with chip-scale integration ambitions, creating a bifurcated innovation landscape where traditional bulk-optic designs compete with waveguide and micro-optics approaches. Companies that cannot reconcile high-power or high-isolation requirements with packaging efficiency risk marginalization in increasingly integrated photonic assemblies.
Third, regulatory and quality assurance requirements continue to raise the barrier for entry and expansion. ISO 9001 certification remains mandatory for high-reliability optical isolator production processes, and the granting of European Patent EP3872558NWB1 on optical isolators for lower-loss mounting in December 2025 signals tightening intellectual property boundaries around manufacturing and assembly techniques. For established players, these developments reinforce brand trust and qualification leverage; for new entrants, they raise the cost and time required to achieve commercial readiness in demanding application segments.
Key Growth Drivers
Several interconnected forces are shaping the market’s evolution and creating distinct avenues for value capture. The first is technological innovation and performance breakthroughs across the wavelength and power spectrum. Manufacturers are expanding the operational envelope of optical isolators to cover UV through NIR wavelengths while pushing isolation levels and power handling higher. High-performance tunable free-space optical isolators with single-stage isolation above 35 dB and double-stage designs exceeding 60 dB are becoming relevant for laser integration scenarios that demand precise feedback prevention. At the same time, high-power fiber-to-free-space and fiber-to-fiber isolators with power handling reaching up to 80 W, and in some demonstrations extending to 150 W average power, are addressing industrial laser and ultrafast fiber laser requirements. These advances directly enable more robust laser systems, reduce downtime from back-reflection damage, and broaden the addressable use cases for isolators in both CW and pulsed regimes.
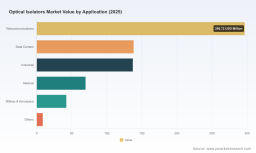
The second driver is shifting demand-side behavior across end-use industries. Telecommunications remains a core anchor, with optical isolators supporting stable signal transmission and minimizing parasitic reflections in high-speed networks. Data centers and industrial applications are growing in importance as laser-based processing, sensing, and photonic interconnects become more pervasive. Medical photonics is another segment where compact, reliable isolators contribute to laser cavities and diagnostic systems that require stable beam quality. Across these sectors, the common theme is operational resilience: buyers prioritize components that reduce failure modes, extend system lifetime, and integrate cleanly into final assemblies. This preference is nudging procurement teams toward suppliers that can offer not just isolation performance but also environmental stability, SWaP optimization, and documented quality processes.
The third driver is supply chain restructuring and cost dynamics. The combination of rare-earth sourcing risks, regional manufacturing concentration, and lead-time elongation is prompting a reassessment of supplier geography and buffer strategies. Companies are increasingly evaluating dual-sourcing, qualification of alternative rotator materials, and inventory buffers for critical SKUs. At the same time, cost pressure is encouraging design efficiencies such as lower-loss mounting architectures and integrated packaging solutions. The granting of patents focused on reduced-loss mounting and the broader emphasis on manufacturing reproducibility indicate that incremental process innovations can translate into measurable performance and cost advantages. In this environment, suppliers that can stabilize lead times, communicate clear qualification milestones, and provide transparent cost trajectories gain a meaningful commercial edge.
A fourth driver is the accelerating integration of isolators into broader photonic module architectures. Rather than treating optical isolators as standalone components, system designers are embedding them alongside lasers, thermoelectric coolers, and other control elements within integrated modules. This shift reflects a broader industry movement toward co-packaged and module-level solutions that reduce assembly complexity and improve overall system performance. As isolators become part of larger functional blocks, the competitive metric evolves from isolated component specs to system-level reliability, thermal management, and ease of integration. This trend is particularly visible in ultrafast fiber lasers and high-power laser systems, where feedback prevention must be achieved without compromising power handling or footprint.
Competitive Landscape and Leading Strategies
The competitive field for optical isolators is diverse, spanning established optics manufacturers, photonics specialists, and regional players with focused product portfolios. The market is moderately fragmented, with a competitive structure where leading firms hold meaningful but not dominant shares. This fragmentation creates space for differentiation on wavelength coverage, isolation performance, power handling, and packaging philosophy. Companies are not competing on a single axis; rather, they are building defensible positions by combining technical capabilities with application-specific solutioning.
Thorlabs has built a broad free-space optical isolator portfolio spanning narrowband and broadband options across 365 nm to visible and NIR wavelengths. Its strategic positioning leans on breadth, compatibility across multiple laser platforms, and the ability to serve laboratories, industrial users, and system integrators with a single sourcing relationship. TOPTICA Photonics SE has emphasized high-performance tunable free-space isolators with strong isolation specifications, targeting laser integration scenarios from UV to NIR where precise feedback control is critical. Its differentiation rests on tunable performance and high isolation tiers, appealing to users who need configurable or application-tuned behavior rather than fixed-characteristic components.
Coherent has focused on Faraday optical isolators for feedback prevention in ultrafast fiber lasers and high-power laser systems, with power handling capabilities extending to elevated average power levels. Its positioning aligns with the growing demand for robust laser protection in demanding power and repetition-rate regimes. CrystaLaser contributes compact Faraday optical isolators and rotators designed and produced in the USA, covering UV, visible, and IR wavelengths. Its compact, domestic manufacturing narrative appeals to buyers prioritizing supply assurance and footprint-sensitive designs. OZ Optics has carved out a strong position in high-power fiber-to-free-space and fiber-to-fiber isolators for 1030 to 1090 nm lasers, with power handling up to 80 W and isolation in the 30 to 50 dB range. This wavelength- and power-focused specialization makes it relevant for industrial and laser-processing applications that operate in the sub-1100 nm band.
LightComm Technology extends the high-power narrative with fiber-to-fiber and fiber-to-free-space optical isolators for 1060 to 1550 nm, supporting up to 100 W with high isolation and environmental stability. Its profile highlights the importance of wavelength alignment to telecom-adjacent and industrial bands, combined with ruggedized performance. Edmund Optics offers both free-space and fiber optical isolators for reducing feedback and blocking reflections in laser cavities, including compact SWaP-optimized models. Its 2025 product launch of compact high-performance optical isolators optimized for SWaP-critical applications in ultrafast and CW lasers reinforces a strategy of delivering performance within tight footprint constraints.
Newport Corporation manufactures Faraday optical isolators for precise laser protection across various wavelengths, positioning around precision, reliability, and broad applicability. Electro-Optics Technology, Inc. develops Faraday rotators and optical isolators for protecting laser diodes, fiber lasers, and solid-state lasers from back reflections, emphasizing protection-oriented design across multiple laser classes. Agiltron specializes in fiber optical isolators and circulators with narrowband and broadband options for telecom and sensing applications, aligning its portfolio with wavelength-sensitive network and sensing use cases. GLSUN provides micro-optics optical isolators, including array, single-channel, chip-scale, and custom designs for high-speed optical networks, reflecting an orientation toward dense integration and scalable form factors.
Digital Isolators Market
AC Photonics offers PM and multimode optical isolators as part of integrated photonic solutions, positioning around polarization-maintaining and multimode needs within broader photonic assemblies. AEPONYX has moved toward chip-scale integration with femtosecond laser direct-written optical waveguide isolators in TSAG crystals, and its 2025 announcement of spiral waveguide isolators achieving high isolation underscores an emerging pathway toward compact, integrated isolator architectures. These companies illustrate how competitive advantage is increasingly defined by the ability to match isolator architecture to application constraints: wavelength, power, isolation, polarization, footprint, and integration style.
Recent developments reinforce the pace of differentiation. In April 2025, Edmund Optics introduced compact high-performance optical isolators optimized for SWaP-critical applications in ultrafast and CW lasers, signaling that miniaturization without sacrificing performance is a near-term commercial priority. In November 2025, AEPONYX announced femtosecond laser direct writing for spiral waveguide isolators in TSAG crystals, highlighting continued progress in integrated photonic isolator fabrication. At Photonics West in January 2026, Advanced Fiber Resources debuted high-power optical isolators with average power handling up to 150 W, including dual-stage TGG designs, demonstrating that power scaling remains an active battleground. In March 2026, Coherent featured isolators in 2026 CPO/NPO module demos with internal laser, isolator, and TEC integration, illustrating the shift toward tightly integrated photonic module architectures. Together, these moves show a landscape where incumbents are extending performance boundaries while innovators explore chip-scale and module-integrated forms.
The market concentration structure suggests room for both consolidation and specialization. With a competitive environment where leading firms hold meaningful but not overwhelming shares, acquisition activity, partnership formation, and vertical integration into module-level solutions are plausible pathways. At the same time, regional specialization and application-focused niches will likely persist, especially where wavelength coverage, power handling, or certification requirements create natural moats. New entrants that bring differentiated fabrication methods, such as waveguide-based isolators or novel rotator materials, may gain traction if they can meet reliability and qualification expectations without incurring prohibitive lead times or cost penalties.
PW Consulting
Future Trends and Commercial Opportunities
Looking ahead three to five years, the optical isolators market is likely to be shaped by a combination of performance scaling, integration acceleration, and supply-chain recalibration. The first trend is the continued push toward higher power handling and multi-stage isolation architectures. As industrial laser systems, ultrafast sources, and high-power fiber lasers become more capable, isolators must withstand greater average and peak power while preserving isolation effectiveness. Dual-stage designs, advanced rotator materials, and refined thermal management will be critical enablers. The commercial opportunity here lies in offering power-rated isolator families with clear qualification boundaries, application-matched isolation levels, and documented reliability under realistic operating conditions. Suppliers that can provide transparent power-scaling roadmaps and robust testing narratives will be well positioned to secure long-term supply agreements in demanding segments.
The second trend is the movement from discrete component supply toward integrated module and chip-scale solutions. As system designers seek to reduce assembly complexity, improve repeatability, and optimize footprint, isolators will increasingly appear within co-packaged photonic modules alongside lasers, coolers, and control electronics. This creates opportunities for suppliers that can design isolators with integration in mind: consistent mechanical interfaces, compatible thermal behaviors, and packaging that supports automated assembly. Chip-scale waveguide isolators and micro-optics approaches are likely to gain share in high-speed optical networks and densely integrated systems, especially where SWaP constraints are stringent. Companies that can bridge the gap between traditional free-space or fiber isolator performance and the form-factor demands of integrated photonics will open new commercial pathways, particularly in telecom, data center interconnects, and compact sensing platforms.
The third trend is supply chain diversification and qualification-led differentiation. Given the volatility surrounding rare-earth sourcing and regional manufacturing concentration, buyers and suppliers alike are likely to place greater emphasis on multi-source strategies, buffer inventories for critical SKUs, and qualification of alternative materials or manufacturing sites. This trend creates opportunities for suppliers that can demonstrate stable lead times, robust quality systems, and clear documentation for high-reliability production processes. Certification readiness, consistent test data, and predictable cost trajectories will become differentiators in procurement decisions, especially in military, aerospace, medical, and industrial applications where downtime and qualification risk are costly. At the same time, the patent environment around lower-loss mounting and related assembly techniques suggests that process IP will play a larger role in shaping competitive access to performance gains.
These trends are accompanied by meaningful uncertainties. Geopolitical disruptions in raw material supply could extend lead times and increase costs beyond current projections, particularly if sourcing diversification lags behind demand growth. Technology transitions toward integrated isolators may fragment demand between established free-space and fiber products and newer waveguide or micro-optic alternatives, creating transitional risk for suppliers heavily exposed to one architecture. Regulatory and certification requirements may continue to raise the bar for market entry, favoring firms with established quality infrastructure while slowing the pace at which new solutions reach volume deployment. Finally, demand growth in telecommunications and data centers may be sensitive to broader infrastructure investment cycles, making it important to monitor capital expenditure patterns and network deployment schedules as leading indicators of near-term orders.
Actionable Guidance for Decision-Makers
For manufacturers and product leaders, the priority is to align isolator portfolios with the convergence of power scaling, integration, and supply resilience. This means developing clearly documented power-rated families, expanding wavelength coverage where application demand justifies it, and investing in packaging and assembly approaches that support module-level integration. Companies should also strengthen qualification narratives and quality documentation to meet the expectations of high-reliability buyers, while exploring alternative sourcing or buffer strategies for critical raw materials. Differentiation will increasingly come from the ability to deliver predictable performance within SWaP constraints and to support customers with transparent lead times and test data. A practical next step is to map current product capabilities against the highest-growth application requirements and identify gaps in power handling, wavelength coverage, or integration readiness that can be addressed in the near term.
For investors and strategic planners, the market presents a moderate-growth but structurally evolving opportunity where value capture depends on positioning rather than broad exposure. Attention should be directed toward suppliers with credible power-scaling roadmaps, integrated module capabilities, and resilient supply strategies, as these attributes are likely to command premium positioning as demand shifts toward higher-performance and more tightly integrated systems. Equally important is monitoring technology transitions toward chip-scale and waveguide-based isolators, which could create new leaders in high-speed networks and compact photonic assemblies. Investment theses should weigh the balance between established free-space and fiber isolator franchises and emerging integration-focused approaches, recognizing that both may coexist with different growth profiles across application segments. Tracking lead-time trends, raw-material cost trajectories, and patent activity around mounting and integration techniques will provide early signals of competitive shifts.
For procurement and sourcing leaders, the strategic imperative is to reduce exposure to single-point supply risk while maintaining the performance and reliability required by end applications. This includes qualifying secondary sources for critical isolator SKUs, establishing clear acceptance criteria for isolation, power handling, and environmental stability, and incorporating lead-time and cost-trajectory data into sourcing decisions rather than relying on price alone. Long-term agreements should be structured to reflect the reality of raw-material volatility and manufacturing concentration, with explicit provisions for buffer inventory, qualification milestones, and performance reporting. In applications where integrated modules are becoming the norm, procurement teams should also evaluate supplier capabilities for co-packaged solutions and alignment with module-level assembly requirements, since these factors increasingly influence total system cost and reliability.
Navigating this market successfully requires timely, granular insight into how performance requirements, supply dynamics, and integration trends are evolving across application segments. Detailed segmentation data, company-level capability comparisons, and application-specific demand signals can sharpen sourcing, investment, and product decisions well beyond what aggregate market figures reveal. For teams seeking deeper segmentation data, regional and application-level breakdowns, and tailored recommendations aligned with specific business objectives, the full research report provides expanded figures, competitive profiles, and scenario-based guidance to support more precise planning.
For detailed analysis of this topic, please visit the official page: Optical Isolators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com