

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
SCBA Market Set for 6.5% CAGR Through 2032: The Strategic Shifts Driving Growth

Navigating the Self Contained Breathing Apparatus (SCBA) Market: Strategic Trends and Commercial Opportunities Through 2032
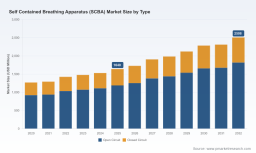
The Self Contained Breathing Apparatus (SCBA) market has entered a phase of structural transformation, driven by tightening regulatory frameworks, evolving operational environments, and rapid advancements in respiratory protection technology. With the market valued at approximately 1.64 billion USD in 2025 and projected to reach 2.51 billion USD by 2032, the sector is expanding at a compound annual growth rate of 6.5 percent. This trajectory reflects more than steady demand growth; it signals a shift in how organizations perceive respiratory safety, equipment lifecycle management, and compliance readiness. The following analysis unpacks the market’s current state, the forces reshaping competitive dynamics, and the strategic implications for manufacturers, investors, and procurement leaders.
Market Landscape and Core Challenges
The SCBA market’s expansion over the 2020–2025 period has been consistent, moving from roughly 1.27 billion USD to 1.64 billion USD, with a steady upward slope expected through 2032. This growth is not uniform across all segments, nor is it insulated from structural friction. The market remains moderately fragmented, with the top three players holding a combined share of approximately 24.6 percent and the top five reaching 35.5 percent. Such concentration levels indicate that while established players maintain strong positions, the market still accommodates regional specialists, niche innovators, and emerging competitors. The absence of extreme consolidation leaves room for strategic differentiation, but it also means that scale advantages, certification readiness, and supply chain resilience increasingly separate market leaders from followers.
Several structural challenges are reshaping how companies operate and plan for the near future. First, the regulatory environment has become a primary driver of product development cycles and replacement demand. The consolidation of legacy standards into updated frameworks has forced manufacturers to accelerate redesign efforts, particularly around facepiece thermal performance and lens durability. Compliance is no longer a static checklist; it is a moving target that influences procurement timelines, inventory planning, and total cost of ownership calculations.
Second, supply chain volatility continues to pressure cost structures and lead times. High-performance materials, including advanced polymers, sealing components, and specialized valve assemblies, remain subject to price fluctuations and geopolitical disruptions. Companies that rely on single-source suppliers or rigid manufacturing footprints are facing margin compression and delayed product rollouts. In contrast, organizations that have diversified sourcing, invested in regional assembly capabilities, or redesigned components for broader material compatibility are better positioned to absorb shocks.
Worldwide Battery Fire Containment Bag Market
Third, the end-user mindset is shifting from reactive replacement to lifecycle optimization. Fire departments, industrial operators, and extractive industries are increasingly evaluating SCBA not just on upfront price, but on durability, serviceability, integration with monitoring systems, and ease of recertification. This behavioral change is compressing the window for low-feature, low-cost offerings and rewarding manufacturers that can demonstrate long-term reliability and support infrastructure. Together, these challenges create a market where compliance agility, supply chain transparency, and total-cost positioning are becoming decisive competitive variables.
Key Drivers Shaping Market Dynamics
Several interconnected forces are accelerating change in the SCBA market. Understanding their interaction is essential for anticipating where demand will concentrate and which product attributes will command premium positioning.
Regulatory Evolution as a Catalyst for Replacement and Innovation
The regulatory landscape is moving from periodic updates to more frequent, performance-based requirements. Recent standard revisions have consolidated previous guidelines and introduced stricter criteria for facepiece lens radiant heat resistance and elevated temperature heat and flame resistance, effective from early 2026. This shift is prompting a wave of recertification activity across major product lines. For manufacturers, this means product roadmaps must account for mandatory upgrade cycles, not just incremental feature improvements. For buyers, it creates a natural replacement cadence that can be planned rather than deferred. The regulatory trajectory is also pushing testing and certification bodies to maintain continuously updated equipment lists, reinforcing the importance of transparent compliance documentation and real-time model tracking.
Technology Innovation Focused on Usability, Durability, and Integration
Technological progress in SCBA is increasingly centered on reducing operator burden while maintaining or improving protection levels. Advances in harness ergonomics, reduced breathing resistance, lighter yet stronger structural materials, and improved regulator stability are becoming baseline expectations rather than differentiators. Beyond core performance, integration with digital monitoring, status indicators, and maintenance tracking is gaining traction in high-stakes environments where equipment readiness directly affects operational continuity. The emphasis is shifting toward systems that are easier to inspect, simpler to maintain, and more predictable over repeated use cycles. This trend favors manufacturers that can combine robust mechanical design with intuitive service interfaces and documented reliability.
Demand-Side Shifts Across Professional Safety and Operational Environments
Demand is being shaped by a broadening set of operational requirements. Fire services remain a foundational application area, but industrial manufacturing, oil and gas operations, and mining activities continue to expand their reliance on self-contained respiratory protection in environments where atmospheric hazards are variable or unpredictable. In many cases, procurement decisions are influenced by the need to standardize equipment across teams, reduce training complexity, and ensure compatibility with existing maintenance ecosystems. Organizations are also placing greater weight on equipment that can withstand frequent deployment, harsh conditions, and rapid turnaround between uses. As a result, the market is seeing stronger demand for units that balance protection, comfort, and serviceability rather than focusing solely on peak specification numbers.
Cost Structure and Supply Chain Realignment
Cost dynamics are being reshaped by material availability, certification-related development costs, and logistics complexity. Manufacturers are under pressure to manage component costs without compromising compliance or field performance. Those that succeed are typically redesigning products to reduce dependency on constrained materials, qualifying alternative suppliers, and improving assembly efficiency. At the same time, buyers are increasingly factoring in total cost of ownership, including maintenance intervals, part availability, training requirements, and recertification pathways. This broader cost lens is rewarding suppliers that can provide predictable lifecycle economics and penalize those whose low initial pricing masks higher operational friction over time.
Competitive Landscape and Leading Strategies
The SCBA market’s moderate concentration suggests a competitive arena where brand trust, certification readiness, and service networks matter as much as raw product specifications. Several manufacturers have established strong positions by aligning product development with regulatory milestones, operational ergonomics, and long-term customer support.
Strategic Positioning Among Core Players
3M Scott Fire & Safety continues to leverage a broad safety ecosystem and a strong heritage in emergency response equipment. Its SCBA portfolio emphasizes integrated performance, field-tested reliability, and alignment with evolving certification requirements. The company’s recent certification activity around updated facepiece and system standards illustrates a strategy centered on maintaining compliance leadership while preserving familiarity for entrenched user bases.
MSA Safety has built a reputation around durable, mission-critical respiratory protection and a strong focus on certification alignment. Its approach highlights rapid response to updated standards, ensuring that core platforms remain eligible for deployment in regulated environments. By prioritizing NIOSH approval and recognized certification marks, MSA reinforces trust with buyers who need assurance that equipment will remain compliant through changing regulatory cycles.
Dräger brings a global engineering presence and a long history in respiratory and safety technology. Its SCBA offerings reflect a focus on robust construction, consistent performance under demanding conditions, and a product philosophy that emphasizes long-term serviceability. The company’s certification updates for its mainstream SCBA platform demonstrate an emphasis on keeping established designs aligned with new performance criteria without disrupting user workflows.
Biomarine Inc. and Interspiro round out a competitive field that includes both specialized and regionally influential players. Biomarine’s positioning tends to emphasize targeted offerings and responsive customer support, while Interspiro draws on a strong European engineering base and a focus on lightweight, operator-friendly systems. These players illustrate that competitive advantage does not always require the largest scale; it can also come from focused application expertise, ergonomic refinement, and agile certification management.
How Competitive Advantage Is Being Redefined
The market is increasingly rewarding companies that can synchronize three elements: certification readiness, product usability, and lifecycle support. First-mover or fastest-follower advantages in certification can translate into procurement eligibility and replacement-cycle influence. At the same time, ergonomics, breathing comfort, and ease of maintenance are becoming decisive in multi-unit deployments where user acceptance affects compliance and operational efficiency. Finally, service infrastructure—including parts availability, inspection support, and training—often determines whether a procurement decision stays locked in over multiple renewal cycles.
PW Consulting Automotive & Machinery Research Center
Market evolution is likely to continue along two parallel paths. One is consolidation among players seeking broader geographic reach, integrated safety portfolios, and stronger service networks. The other is differentiation by specialized applications, ergonomic innovation, and regional responsiveness. New entrants and smaller specialists can still compete by targeting underserved application needs, offering faster customization, or providing more flexible support models. However, they must navigate certification complexity and supply chain constraints carefully to avoid being outpaced by larger incumbents with established compliance pipelines.
Worldwide Compressed Breathing Air Testing Market
Future Outlook: Trends and Commercial Opportunities
Over the next three to five years, the SCBA market is likely to be shaped by a small number of high-impact trends. Each carries both opportunity and risk, and the companies that navigate them well will be those that treat compliance, customer experience, and cost structure as integrated design variables rather than separate functions.
Accelerated Certification-Driven Replacement Cycles
As updated performance requirements take hold, replacement and upgrade activity is expected to intensify across fire services and industrialsafety fleets. This creates a commercial opportunity for manufacturers that can offer clear migration paths, compatible component ecosystems, and predictable certification timelines. For buyers, the opportunity lies in planning fleet refreshes in coordination with regulatory milestones rather than reacting under time pressure. The principal risk is adaptation lag: companies that underestimate recertification lead times or fail to align production with updated standards may face eligibility gaps and procurement delays.
Elevated Emphasis on Ergonomics and Operational Efficiency
User comfort and operational efficiency are likely to become stronger purchase criteria as organizations deploy SCBA more frequently and across broader teams. Lighter weight, reduced fatigue, better balance, and simpler donning and doffing processes can improve adoption and reduce error risk in high-stress environments. Manufacturers that invest in these attributes can differentiate even in a market where protection levels are already high. The risk is over-indexing on comfort at the expense of durability or compliance robustness. The most successful offerings will balance human-centered design with verified performance under extreme conditions.
Lifecycle Service Models and Equipment Intelligence
The market is moving toward more structured lifecycle management, where maintenance planning, component traceability, and readiness verification play a larger role in procurement decisions. Opportunities are emerging for suppliers that can provide transparent service pathways, predictable part availability, and tools that simplify inspection and recertification workflows. In some environments, enhanced status visibility and maintenance tracking may also support better fleet management and reduce unplanned downtime. The risk lies in overpromising digital or service features without the operational backbone to deliver them consistently. Buyers will increasingly distinguish between surface-level add-ons and genuine lifecycle support.
Strategic Actions for Decision Makers
The current environment rewards organizations that align product strategy, procurement planning, and investment decisions with the market’s regulatory and operational momentum. Tailored actions can help different stakeholders convert market change into advantage.
For Manufacturers
Prioritize certification readiness as a core product strategy rather than a compliance afterthought. Align development cycles with anticipated standard updates, ensure component designs can accommodate material or performance changes, and maintain transparent documentation that supports procurement eligibility. At the same time, invest in ergonomics, serviceability, and predictable lifecycle economics, since these attributes increasingly influence repeat purchasing and fleet standardization. Diversifying supply sources and qualifying alternative materials can also reduce exposure to cost shocks and production delays.
For Investors
Focus on companies that demonstrate disciplined responses to regulatory change, resilient supply chain practices, and strong end-user retention. The most durable value creation is likely to come from organizations that can convert certification momentum into replacement-cycle share while maintaining margin discipline through cost structure control. Evaluate not only product names and brand presence, but also service networks, component availability, and the ability to scale certified offerings across regions. In a moderately concentrated market, strategic acquisitions and partnership models may also create opportunities for portfolio expansion and regional reach.
For Procurement and Operational Leaders
Plan replacement and upgrade cycles in coordination with regulatory timelines to avoid emergency purchasing and compatibility disruptions. Evaluate SCBA on total cost of ownership, including maintenance burden, parts availability, training implications, and the likelihood of continued certification over the equipment’s service life. Standardization across teams can reduce training complexity and simplify maintenance, but it should be pursued only when the chosen platform demonstrates clear compliance durability and operational fit. Request documented certification status, service pathways, and lifecycle support commitments to ensure that procurement decisions remain resilient as standards evolve.
For decision makers seeking deeper segmentation data, regional demand patterns, and customized scenario planning, comprehensive research coverage can help translate these market-level dynamics into precise product, investment, and procurement strategies. Detailed analysis of segment trajectories, competitive positioning, and regulatory impact timelines provides the granularity needed to move from market awareness to execution-ready decisions.
For detailed analysis of this topic, please visit the official page: Self Contained Breathing Apparatus (SCBA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com