

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Digital Valve Positioner Market: Why 5.2% CAGR and Industry Shifts Redefine Growth

Navigating the Digital Valve Positioner Market: Strategic Trends and Commercial Opportunities Through 2032
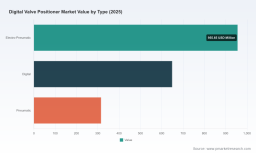
The global market for digital valve positioners has entered a phase of steady, structurally supported expansion. Valued at approximately $1.92 billion in 2025, the sector is projected to reach $2.73 billion by 2032, reflecting a compound annual growth rate of 5.2 percent over the forecast horizon. This trajectory is not merely a continuation of historical demand; it signals a fundamental shift in how industrial flow control systems are designed, operated, and maintained. As process industries prioritize precision, safety compliance, and operational visibility, digital valve positioners are transitioning from auxiliary instrumentation to core components of modern control architectures.
Understanding where this market is headed requires looking beyond aggregate figures. The growth is uneven across regions, unevenly distributed across application verticals, and increasingly shaped by certification requirements, protocol standardization, and the pace of industrial digitization. For executives and investors, the opportunity lies not in the market’s size alone, but in the alignment of technology roadmaps, regulatory timelines, and procurement cycles that will determine which players capture margin, which segments accelerate, and where integration risks emerge.
Market Snapshot and Structural Headwinds
The market’s baseline reflects a mature but evolving ecosystem. Over the past five years, revenue growth has been anchored by incremental upgrades in chemical processing, energy generation, and hydrocarbon handling facilities, where legacy analog and early electro-pneumatic systems are being replaced or retrofitted with digitally enabled controllers. The base-year valuation of $1.92 billion masks a more nuanced reality: adoption is concentrated in applications where failure penalties are high, regulatory scrutiny is intense, and downtime costs justify the premium for diagnostic and positioning accuracy.
Yet the sector faces several inflection points that will shape competitive outcomes over the next three to five years:
-
Certification bottlenecks and harmonization gaps. Hazardous-area approvals remain a gatekeeper for market entry and regional expansion. While leading controllers now carry ATEX, IECEx, CSA, and marine certifications, the fragmentation of testing requirements across jurisdictions increases time-to-market and compliance overhead for manufacturers seeking global scale.
-
Protocol proliferation versus interoperability demands. Facilities are deploying mixed communication stacks, from HART and Profibus PA to Foundation Fieldbus and emerging proprietary digital links. The absence of a single dominant protocol creates integration complexity for end users, while raising the engineering burden on OEMs that must maintain multi-protocol firmware and validation suites.
-
Legacy infrastructure and retrofit economics. A significant portion of installed valve assets were designed for pneumatic or basic electro-pneumatic actuation. The business case for retrofitting depends on site-specific downtime windows, spare-parts compatibility, and the ability to demonstrate measurable gains in positioning accuracy, leak reduction, or predictive maintenance payback.
Digital Pressure Gauges Market
Core Drivers Reshaping Demand and Competitive Logic
The market’s trajectory is being pulled by a combination of technological, regulatory, and demand-side forces. These drivers do not operate in isolation; they reinforce one another and create distinct value pools for suppliers that can sequence product development, certification, and service models effectively.
Piezo Positioners Market
Technology Innovation and the Diagnostic Premium
The most visible driver is the shift from positioning accuracy alone to holistic device intelligence. Contemporary controllers increasingly bundle on-board pressure sensing, closed-loop feedback, and real-time diagnostic outputs that enable condition monitoring without additional field instrumentation. This evolution is not cosmetic; it changes the economic calculus for plant operators. A positioner that can surface drift, hysteresis trends, or air supply anomalies reduces the need for manual rounds and unplanned shutdowns, while creating a clearer path to predictive maintenance programs.
Recent product activity illustrates this direction. In March 2025, Emerson introduced the Fisher FIELDVUE DVC7K digital valve controller engineered for on/off applications, unifying control behavior with position feedback in a single platform. A month later, the company published an updated instruction manual for the DVC7K-H variant, signaling sustained investment in documentation, field usability, and service clarity. These moves reflect a broader industry pattern: manufacturers are competing not only on hardware robustness, but on the transparency and reliability of diagnostic workflows, including software-linked insights that help operators interpret device health without specialized instrumentation expertise.
Regulatory Pressure and Safety-Critical Positioning
Regulatory and safety expectations are simultaneously a constraint and a demand catalyst. In hazardous environments, positioners must demonstrate robust performance under flameproof, intrinsic safety, and dust ignition conditions, while supporting functional safety targets where process risk warrants it. This has elevated the importance of certifications such as ATEX and IECEx, alongside region-specific approvals like CSA and marine certifications for offshore and marine installations.
For suppliers, certification depth has become a differentiator rather than a baseline. Devices that carry multiple hazardous-location approvals and are engineered to support higher safety integrity requirements unlock access to capital-intensive and tightly regulated segments. At the same time, the compliance burden favors organizations with established testing infrastructure and repeatable validation processes, creating a structural advantage for incumbents that can sustain certification portfolios across product families. This dynamic is visible across multiple offerings: Woodward’s DVP emphasizes ATEX, IECEx, CSA, and marine approvals for hazardous and marine use; Baker Hughes’ Masoneilan SVI3 is positioned as SIL3 capable with ATEX, IECEx, and US/Canada approvals for flameproof, intrinsic safety, and dust ignition proof environments; Flowserve’s PMV D3 carries ATEX and CSA/FM explosion-proof approvals for hazardous areas; and Emerson’s DVC7K integrates hazardous-area approvals with diagnostic software linkages. The pattern confirms that safety certification is now a core element of commercial positioning, not an afterthought.
Demand-Side Shifts: Reliability economics and operational visibility
On the demand side, the strongest pull comes from operators treating valve control as a reliability and energy-efficiency lever. In oil and gas, energy and power, and chemical processing, facilities are under pressure to reduce non-productive time, tighten emissions control, and improve throughput consistency. Digital positioners support these goals by improving control-loop stability, reducing calibration drift, and enabling faster commissioning through clearer configuration and feedback.
Behavior is also changing at the procurement and engineering level. Projects are increasingly specifying devices that can interface cleanly with broader automation and asset-management environments, reducing the need for isolated point solutions. This preference rewards controllers that offer modular architectures, clear protocol support, and straightforward integration paths. At the same time, end users are more willing to accept a premium where the device can demonstrate measurable improvements in positioning repeatability, diagnostic coverage, or maintenance interval extension. The result is a demand environment that rewards practical reliability over marketing language, and that favors suppliers able to tie device capabilities to operational outcomes.
Supply Chain and Cost Structure Dynamics
Supply chain and cost considerations are exerting a more subtle but durable influence. Component availability, semiconductor sourcing, and the cost of certified enclosures and hazardous-area construction materials affect both pricing and lead times. Manufacturers that can secure stable input channels, design for manufacturability across variants, and avoid over-customization at the edge gain resilience in a market where project timing and spare-parts availability matter as much as unit price.
Cost structures are also being reshaped by the move toward smarter controllers that reduce downstream engineering and maintenance burden. When a positioner lowers field calibration frequency or simplifies protocol configuration, the total cost of ownership argument improves even if the upfront device price is higher. This dynamic is particularly important in retrofit projects, where installers must weigh integration effort against long-term operational savings. Suppliers that can articulate and substantiate these lifecycle benefits are better positioned to defend margins in segments where price competition remains intense.
PW Consulting Automotive & Machinery Research Center
Competitive Landscape and Strategic Positioning
The market remains moderately fragmented, with the top three players collectively accounting for roughly a quarter of revenue and the top five approaching a third. This concentration leaves meaningful room for regional specialists, application-focused suppliers, and new entrants that compete on specific technical or commercial dimensions rather than on total portfolio breadth.
Leading manufacturers are differentiating along several complementary axes:
-
Safety and certification breadth. Companies that maintain extensive hazardous-area approvals and functional safety capability secure advantage in oil and gas, energy, and chemical segments where risk exposure is high and specification cycles are rigorous.
-
Diagnostic depth and software integration. Controllers that pair field-level sensing with accessible diagnostic software create a more compelling operational story. The ability to translate device outputs into actionable insights—supported by clear documentation and field service alignment—increasingly separates premium offerings from commodity positioning products.
-
Protocol flexibility and modular design. In environments where automation stacks are heterogeneous, multi-protocol support and modular hardware architectures reduce integration friction. This is especially relevant for brownfield projects and multi-vendor sites that cannot standardize on a single communication layer.
-
Application-specific engineering. Some suppliers compete by tailoring devices to particular valve types or operating conditions. Offerings optimized for quarter-turn valves, high-speed precise control, or on/off applications can outperform generalist devices in targeted segments, even if they lack the broadest portfolio.
The competitive map is also evolving through productization and consolidation dynamics. Large industrial automation and valve specialists are strengthening their positions by unifying hardware, software, and service narratives, while mid-tier players are carving niches around ruggedness, rapid configuration, or specific certification footprints. New entrants can still succeed by focusing on underserved application sets, simplifying installation and commissioning, or offering attractive retrofit paths for legacy systems. However, the barrier is rising: certification maintenance, multi-protocol support, and field-service credibility now form a more demanding baseline than in the past.
Strategic Outlook: Three Trends Defining the Next Three to Five Years
Looking ahead, the market’s evolution will be shaped by the intersection of technology maturity, regulatory continuity, and procurement behavior. Three trends are likely to have outsized influence on opportunity and risk.
Trend One: Diagnostics and Connected Maintenance Move from Feature to Standard Expectation
As operators accumulate field evidence that device-level diagnostics reduce troubleshooting time and improve maintenance planning, digital positioners will face growing pressure to deliver more than precise positioning. Over the forecast period, the baseline expectation will likely shift toward clearer health indicators, easier integration with asset management workflows, and documentation that supports field service without specialized interpretation. The commercial opportunity lies with suppliers that can standardize diagnostic packages across product lines, maintain firmware consistency, and provide practical software tools that do not require extensive training to use effectively. The risk is that diagnostic claims outpace field validation; devices that promise insight but deliver noisy or ambiguous outputs can erode trust and slow repeat adoption.
Trend Two: Certification and Safety Integrity Remain Market Gatekeepers
Hazardous-area approvals and functional safety capability will continue to shape where and how quickly digital positioners can be deployed. Segments with stricter risk profiles and tighter regulatory oversight will reward suppliers with well-maintained certification portfolios and clear safety documentation. Over time, the market may see modest convergence in testing expectations, but regional variation is unlikely to disappear entirely. The strategic implication is twofold: manufacturers should treat certification as a long-term portfolio investment rather than a per-product event, and end users should evaluate approval coverage as a core element of specification, not a secondary checkbox. Uncertainty remains around the pace of harmonization and the cost of maintaining approvals across multiple jurisdictions, both of which can affect launch timing and margin planning.
Trend Three: Retrofit and Brownfield Modernization Will Drive a Meaningful Share of Demand
While greenfield projects contribute to growth, a substantial portion of future demand will come from upgrading existing control loops and replacing aging analog or early electro-pneumatic devices. Retrofit economics will hinge on installation simplicity, compatibility with existing actuators and air supplies, and the ability to demonstrate payback through fewer calibration events, improved loop stability, or reduced downtime. Suppliers that offer drop-in compatibility, clear migration guidance, and predictable commissioning steps will be better positioned to capture this segment. The risk is that retrofit projects stall when integration complexity or valve-body compatibility is underestimated, which can slow adoption even when the technology case is strong.
Implications and Actionable Takeaways
The digital valve positioner market is expanding in a way that rewards commercial discipline as much as technical competence. The following implications are most relevant for different stakeholder groups.
For manufacturers and product leaders, the priority is to build coherence across hardware, certification, and diagnostic software. A strong controller that lacks robust approval coverage or reliable field documentation will underperform in regulated segments. Conversely, a well-certified device with unclear diagnostic value may struggle to justify premium pricing. Sequencing roadmap decisions around modular design, multi-protocol support, and lifecycle service clarity offers a more durable competitive position than chasing isolated feature additions.
For investors and corporate development teams, the market’s moderate concentration and application-driven growth create opportunities in companies with strong safety certification footprints, clear retrofit value propositions, or differentiated diagnostic integration. The key diligence question is whether a supplier’s technical claims translate into measurable operational outcomes that customers can repeat across sites. Revenue potential should be evaluated alongside certification maintenance costs, protocol support demands, and the realism of field-service capacity, since these factors shape both margin and scalability.
For procurement and engineering decision-makers, specification should balance compliance, integration, and total cost of ownership. Devices with broad hazardous-area approvals and proven protocol compatibility reduce project risk, while clear diagnostic and feedback capabilities can improve maintenance planning and loop stability. Retrospective value is often realized when the selected controller aligns with the site’s existing automation context and spare-parts strategy, rather than when it is chosen solely on the basis of peak specifications. Evaluating field documentation, configuration simplicity, and support pathways alongside hardware features leads to more reliable project outcomes.
Closing Perspective
The digital valve positioner market is entering a period where growth is supported by reliability economics, safety-driven specification, and the gradual shift toward smarter field devices. The $1.92 billion base year and the 5.2 percent compound trajectory through 2032 describe the scale of the opportunity, but the real strategic value lies in how that growth is distributed across applications, certifications, and integration models. Suppliers and buyers alike will benefit from focusing on the operational realities that determine adoption: hazardous-area readiness, diagnostic usefulness, retrofit practicality, and the clarity of the path from device to decision. For organizations seeking deeper segmentation detail, regional demand patterns, and tailored action plans for specific product categories, broader research coverage is available to support more precise planning.
For detailed analysis of this topic, please visit the official page: Digital Valve Positioner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com