

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
How 24.41% CAGR and 79.2% Concentration Are Redefining the Worldwide Online Audiobook Site Market Through 2032

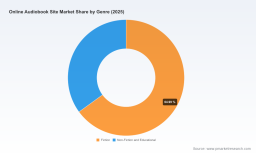
The Worldwide Online Audiobook Site Market: Strategic Trends and Commercial Opportunities
Market Overview: Scale, Momentum, and Structural Challenges
The global online audiobook marketplace has entered a defining growth phase, transitioning from a niche convenience into a mainstream content consumption channel. Between 2020 and 2025, the sector expanded from approximately $3.45 billion to over $10.5 billion in annual revenue, reflecting sustained adoption across consumer and professional segments. The trajectory forward points to continued acceleration, with an expected compound annual growth rate of 24.41% through 2032. By the end of that forecast horizon, the market is projected to surpass $48.4 billion in total annual turnover. This growth is not merely a function of demographic tailwinds or pandemic-era habit formation; it reflects a structural shift in how audiences consume long-form narrative, educational, and reference content across mobility constraints, multitasking lifestyles, and accessibility requirements.
Audiobook Apps Market
Despite the optimism, the market faces several structural inflection points that will determine which operators capture durable value. First, concentration remains high at the platform level. The top three operators command roughly two-thirds of overall platform revenue, while the top five approach eight-tenths of total activity. This concentration creates pricing power and catalog leverage for incumbents, but it also raises barriers for independent publishers and mid-tier platforms seeking distribution reach without sacrificing margin. Second, infrastructure costs are rising in tandem with streaming volumes. Data center electricity consumption tied to digital content delivery has grown substantially in recent years, with U.S. facilities alone accounting for a meaningful share of national power demand and projections pointing toward continued escalation through the end of the decade. Platforms that scale catalog depth and recommendation algorithms without addressing hosting efficiency and edge delivery will face margin compression. Third, regulatory fragmentation is becoming a practical operational constraint rather than a distant compliance issue. An expanding patchwork of state-level privacy frameworks in the United States, alongside established European data protection and operational resilience requirements, forces global platforms to rethink how listening data, user profiles, and payment information are stored, processed, and transferred across jurisdictions. Platforms that treat compliance as a secondary function will encounter friction in expansion, particularly where localization expectations intersect with multi-region content licensing.
These dynamics create a market that is simultaneously expanding and consolidating in practice. Growth is real, but it is increasingly conditional on operational discipline, data governance maturity, and the ability to convert broad catalog access into differentiated user experiences. The next phase of value creation will depend less on raw title count and more on how platforms structure monetization, manage infrastructure spend, and navigate an increasingly layered regulatory environment.
Key Drivers Shaping the Market
Technological Innovation and Listening Experience Design
The most visible driver of market expansion is the transformation of the listening experience itself. Audible has doubled down on catalog depth and ecosystem integration, offering the world’s largest audiobook library and weaving listening into the broader retail and device environment that supports exclusive originals and seamless playback. Spotify has pursued a different technical wedge: embedding audiobooks within an already-scaled music and podcast subscription, supplemented by targeted add-on tiers and limited listening hours for casual users. Its recent introduction of Page Match technology, which allows listeners to transition between a physical book or e-book and the corresponding audio track by scanning a page, signals a broader strategy of bridging analog and digital reading rather than replacing it. Coupled with new audiobook charts in key markets, the feature aims to reduce discovery friction and make audiobooks feel native within a broader content routine. Apple Books continues to emphasize cross-device continuity and high-quality narration within its hardware ecosystem, while Google Play Books focuses on accessibility, Android-level integration, and publisher-facing distribution tools. The common thread across these approaches is that technical differentiation is shifting from catalog size alone toward seamlessness, discovery, and cross-format interoperability.
Regulatory and Privacy Dynamics
Regulation is reshaping the operating environment in ways that directly affect platform architecture and expansion economics. Net neutrality challenges and regulatory rollbacks in the United States have introduced uncertainty around traffic prioritization and throttling, which matters for platforms that depend on consistent broadband delivery for uninterrupted playback at scale. More immediately, data sovereignty and localization requirements have expanded in scope and geography. Multiple U.S. states have enacted comprehensive privacy regimes, with new provisions taking effect in 2026 across additional jurisdictions, while EU frameworks continue to require control over where listening and behavioral data is processed. For global platforms, this means that a single data pipeline is no longer sufficient. Compliance now intersects with product design, customer support, recommendation engines, and partnership structures. Companies that design architecture with regional data handling from the outset gain advantages in market entry speed and partnership eligibility, while those that retrofit compliance later face integration costs and reputational exposure.
Consumer Habits and Demand-Side Shifts
Demand is being reinforced by durable changes in listening behavior. In the United States, more than half of adults aged eighteen and older have listened to an audiobook, with a meaningful subset engaging daily and a large majority identifying accessibility as an important factor in their listening choices. In the United Kingdom, weekly audio reach has expanded substantially since 2019, with average weekly listening among users approaching ten hours. These figures indicate that audiobooks are no longer an occasional substitute for reading; they are becoming a routine component of daily commutes, exercise, and work-adjacent consumption. Accessibility is particularly significant because it expands the addressable audience beyond convenience-driven users to include listeners who rely on audio for visual, cognitive, or mobility-related reasons. This broadens the market’s base and reduces sensitivity to price-only competition, provided platforms can demonstrate inclusive design and quality narration.
Supply-Side and Cost Structure Evolution
On the supply side, the publisher-distributor relationship is evolving as production scale and catalog breadth increase. RBmedia’s record results in early 2026, driven by catalog growth, bestseller traction, and award wins across major platforms, illustrate how strong production pipelines continue to feed consumption across multiple endpoints simultaneously. At the same time, the cost of hosting, streaming, and personalizing large catalogs is rising as usage intensifies. The energy footprint associated with data centers supporting digital content delivery is climbing, and the pressure to manage that footprint is becoming part of the cost structure conversation. Platforms that cannot align catalog growth with storage efficiency, streaming optimization, and smarter recommendation logic will find it harder to sustain margin expansion as competition intensifies and subscription pricing comes under scrutiny.
Competitive Landscape and Leading Strategies
The competitive environment is shaped by a mix of platform-led, ecosystem-led, and publisher-led models. Audible remains the dominant global platform, leveraging an extensive catalog and Amazon ecosystem integration to anchor subscription plans, credits, and exclusive originals. Its recent launch of a lower-priced Standard plan in key markets reflects a strategic response to integrated streaming offerings that have blurred the line between dedicated audiobook services and broader entertainment subscriptions. By creating a more accessible entry point, Audible is seeking to defend share without diluting its premium positioning.
Spotify’s approach is distinct because it treats audiobooks as one layer inside a larger listening subscription rather than a standalone product. Its Audiobooks add-on, limited casual listening hours, and original catalog of more than half a million English-language titles are supported by tools like Page Match and integrated charts that aim to strengthen discovery. The partnership with Bookshop.org, enabling physical book purchases directly through the app for U.S. and UK users, indicates a strategy of building a multi-format book journey rather than competing purely on digital playback. This positions Spotify as a habit aggregator, linking music, podcasts, and audiobooks within a single subscription logic.
Apple Books and Google Play Books continue to capitalize on device and ecosystem reach. Apple emphasizes seamless syncing across iOS and macOS, high-quality narration, and broad catalog access optimized for its user base. Google focuses on direct sales, Android integration, and distribution support for publishers, with an emphasis on accessibility and cross-device listening. Both benefit from installed base advantages, though their monetization leans more toward transactional access and ecosystem reinforcement than subscription-exclusive exclusivity.
European and multi-format players bring a different set of strengths. Storytel operates as a subscription-based audiobook and ebook streaming service with strong European presence and expanding English-language reach through acquisitions. Scribd, now operating under the Everand brand, shifted to a credit and unlock model that provides access to a rotating audiobook catalog alongside ebooks and magazines, reflecting a pivot toward controlled access economics rather than unlimited consumption. Rakuten Kobo offers Kobo Plus with dedicated audiobook plans and combined ebook and audiobook access, integrated with e-reader hardware, while Audiobooks.com, now part of Storytel, maintains a credit-based subscription model with family plans and offline listening.
Libro.fm occupies a differentiated niche by supporting independent bookstores through an affiliate model, combining purchases and subscriptions with a social impact proposition. RBmedia sits outside the direct consumer interface but remains strategically important as a major publisher with a vast catalog distributed across Audible, Spotify, Apple, Google Play, and library platforms. Its performance underscores the centrality of production and licensing quality to platform success.
The overall landscape is moving toward selective consolidation and functional differentiation. Integrated mega-platforms are competing on ecosystem bundling and discovery tools, while specialist services are competing on catalog curation, format blending, and partnership models. New entrants face steep challenges in catalog acquisition and user acquisition costs, but there is room for differentiated services that serve specific listener segments, accessibility needs, or regional licensing structures. The likely trajectory is a market with a small number of broad-scale platform leaders, a set of strong regional or format-specialist services, and a publisher layer whose influence depends on the quality and breadth of rights management.
Forecast Outlook: Trends and Commercial Implications
Over the next three to five years, one of the clearest trends will be deeper format convergence. Audiobooks will increasingly be embedded within broader listening and reading journeys, supported by tools that link physical books, e-books, and audio tracks. Platforms that make switching frictionless and provide credible cross-format discovery will capture more habitual usage and reduce churn. The commercial opportunity here is not simply more titles; it is a more integrated recommendation and purchase path that increases lifetime value without requiring exaggerated catalog inflation.
PW Consulting
A second trend is the growing importance of data governance and regional readiness as competitive factors. As privacy and localization rules broaden, platforms that can demonstrate transparent data handling, modular architecture, and compliant cross-border operations will be better positioned for expansion into regulated markets and partnership-dependent channels such as libraries and publisher networks. The opportunity lies in turning compliance maturity into market access speed and trust-based differentiation, particularly for enterprise and institutional buyers who weigh risk exposure alongside content quality.
A third trend is the continued pressure on infrastructure economics. As consumption scales, the cost of delivery, storage, and personalization will require more disciplined engineering and more intelligent catalog management. The commercial implication is that margin leadership will increasingly favor operators who can balance catalog breadth with hosting efficiency, streaming optimization, and selective personalization. Platforms that rely on indiscriminate catalog growth without cost-aware design may find growth harder to convert into profitability.
These trends carry uncertainty. Pricing pressure could intensify if bundled subscriptions continue to blur boundaries between audiobooks and adjacent content. Regulatory shifts could alter traffic delivery assumptions and increase compliance overhead. Accessibility and inclusion expectations will likely rise, which is favorable for audience expansion but may raise production and interface standards. The net result is a market with strong growth potential, but where strategic advantage depends on execution quality as much as market momentum.
Strategic Actions for Decision-Makers
For platform operators and content businesses, the priority is to treat listening experience design as a growth lever rather than a feature layer. Investments in cross-format discovery, seamless switching, and accessibility-minded interfaces are likely to yield more retention and expansion than catalog volume alone. At the same time, infrastructure and data architecture should be revisited with an eye to regional compliance and cost efficiency, because these factors are becoming gating conditions for scale rather than administrative details.
Worldwide Online Books Market
For investors and strategic partners, the relevant question is which business models are most resilient under bundling pressure and which operators have durable advantages in catalog rights, discovery quality, and ecosystem reach. Platforms with strong integration into broader habits, credible accessibility positioning, and disciplined cost structures are better placed to convert growth into sustainable economics. Evaluating exposure to regional privacy and localization requirements should also be part of due diligence, especially where expansion plans depend on multi-market data handling.
For publishers, distributors, and procurement teams, the focus should be on partnership structures that preserve reach while managing cost and compliance risk. Multi-platform distribution remains valuable, but selection should account for audience overlap, device reach, and the platform’s ability to support accessibility and discovery that aligns with target listener behavior. In a market where concentration and regulation are both intensifying, timely and granular intelligence on segment dynamics, platform strategy, and regional requirements is essential for allocating resources and negotiating terms with confidence. More detailed breakdowns of segment dynamics, platform-level positioning, and regional considerations are available in the full PW Consulting study, which provides the depth needed for planning in a market that is moving quickly and becoming more structurally complex.
For detailed analysis of this topic, please visit the official page: Worldwide Online Audiobook Site Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com