

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Conductive Acetylene Black Market: Why 11.45% CAGR Alters Li-ion Battery Competition

Global Conductive Acetylene Black Market: Strategic Trends and Commercial Opportunities (2025–2032)
Market Landscape and Core Challenges
The global conductive acetylene black market for lithium-ion batteries has entered a period of accelerated expansion, driven by the rapid electrification of transportation and the scaling of stationary energy storage. From 2020 to 2025, the market grew from approximately 251.2 million USD to 428.5 million USD, reflecting a compound annual growth rate of 11.45 percent. Forward projections extend this trajectory through 2032, with revenue expected to surpass 915 million USD by the end of the forecast period. This growth is not merely incremental; it represents a structural shift in how battery manufacturers approach conductivity enhancement, formulation optimization, and long-term supply chain resilience.
At this scale, the market is characterized by moderate concentration. The top three players command roughly 58.4 percent of global revenue, while the top five capture approximately 76.25 percent. This concentration indicates a mature yet still evolving competitive field, where established suppliers hold significant technological and distribution advantages, but where regional expansion, capacity investments, and product differentiation are actively reshaping market shares. The dominance of powder-form products over granular alternatives reflects the industry's continued preference for fine-particle additives that integrate seamlessly into slurry processing and electrode coating workflows.
Despite the robust growth trajectory, several structural challenges are creating inflection points for suppliers, buyers, and investors.
First, raw material sourcing and carbon intensity are becoming critical differentiators. Acetylene black production depends heavily on acetylene gas, which is traditionally derived from calcium carbide or emerging low-carbon plasma processes. The energy intensity and environmental footprint of acetylene generation directly affect both cost structures and regulatory compliance, especially as battery supply chains face increasing scrutiny over lifecycle emissions. Firms that cannot secure reliable, lower-carbon acetylene feedstocks or demonstrate verifiable decarbonization pathways risk marginalization in premium segments and markets with stringent sustainability requirements.
Second, the demand profile is shifting toward larger-format cells and high-energy-density chemistries, which place new performance demands on conductive additives. Electric vehicle batteries are increasingly specifying thicker electrodes, silicon-blended anodes, and high-nickel cathodes. Each of these developments alters the rheological behavior of electrode slurries and the percolation thresholds required for optimal conductivity. Conductive acetylene black suppliers must therefore balance particle morphology, surface area, purity, and electrolyte retention to meet expanding technical specifications without compromising processability or cycle life.
PW Consulting
Third, capacity expansion and geographic realignment are introducing both opportunities and execution risks. As demand scales across Asia Pacific, Europe, and North America, suppliers are investing in new production lines and regional manufacturing footprints. However, large-scale capacity additions require long lead times, substantial capital, and coordinated feedstock agreements. Delays in plant commissioning, feedstock supply disruptions, or misalignment between regional demand growth and localized production can create temporary bottlenecks, price volatility, and qualification bottlenecks in tightly controlled automotive supply chains.
These challenges are not simply headwinds; they are reshaping the strategic priorities of the market. Suppliers that proactively address feedstock sustainability, technical customization, and regional supply security are positioning themselves to capture premium value, while buyers are increasingly factoring carbon intensity, qualification timelines, and supply continuity into procurement decisions.
Key Drivers Shaping the Market
Technology Innovation and Product Performance
The most immediate driver of market growth is the continuous push for higher battery performance, particularly in energy density, power delivery, and cycle stability. Conductive acetylene black serves as a critical enabler in lithium-ion electrode architectures by establishing conductive pathways, improving slurry dispersion, and maintaining contact between active materials and current collectors over repeated cycling. As battery manufacturers pursue higher-voltage cathodes, silicon-containing anodes, and more aggressive fast-charging profiles, the functional requirements for conductive additives become more demanding.
Lithium Ion Battery Market
Ultra-pure acetylene black grades with minimal metallic impurities are gaining importance in these applications. Lower impurity levels reduce side reactions at electrode interfaces, improve electrolyte retention, and support more consistent electrochemical performance. This has encouraged suppliers to advance purification processes, control particle morphology more tightly, and develop grades tailored to specific cell formats and chemistries. The result is a market that is moving away from commoditized carbon additives toward application-specific, performance-differentiated products.
Another technological shift is the growing emphasis on low-carbon production. Several industry initiatives are targeting cleaner acetylene generation pathways, including plasma-based processes that can reduce reliance on traditional carbide routes. When paired with efficiency improvements in reactor design and downstream processing, these approaches can lower both operating costs and emissions intensity. For battery makers under increasing pressure to demonstrate supply chain decarbonization, low-carbon acetylene black can become a differentiating input, particularly for premium electric vehicle and energy storage programs.
Policy and Regulatory Environment
Policy frameworks are accelerating demand while simultaneously shaping supply-side behavior. Broader electrification targets, vehicle emission standards, and energy storage deployment incentives continue to expand the addressable market for lithium-ion batteries. At the same time, governments and development agencies are increasingly supporting industrial projects that reduce carbon exposure in critical material supply chains.
Public support for low-carbon acetylene technologies illustrates this dynamic. Subsidies and cooperative financing have been directed toward initiatives that accelerate mass-production technology for lower-carbon acetylene used in conductive carbon black. Such interventions matter because they reduce the commercial risk associated with scaling new feedstock routes and can shorten the timeline between process development and commercial availability. For established suppliers, these programs can provide additional leverage to invest in capacity and process upgrades. For newcomers, they can help bridge the gap between pilot-scale validation and meaningful market entry.
Regulatory attention is also influencing qualification and procurement practices. Automotive and energy storage customers are extending their supplier assessment criteria beyond cost and performance to include traceability, environmental impact, and supply continuity. In this environment, suppliers that can document consistent quality, transparent sourcing, and credible decarbonization actions are better positioned to secure long-term contracts and participate in multi-year platform programs.
Demand-Side Changes in Consumer and Enterprise Behavior
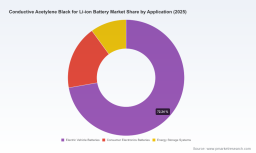
Demand for conductive acetylene black is being pulled upward by two distinct but converging channels. In the mobility sector, electric vehicle production continues to scale across passenger cars, commercial fleets, and two-wheelers, with battery packs growing in both absolute volume and cell count. Manufacturers are increasingly designing platforms that require consistent, high-quality conductive additives across large production runs, reinforcing the need for reliable supply and repeatable material performance.
In the stationary storage segment, growth is being driven by grid integration, renewable firming, and commercial and industrial energy management. While energy storage systems currently represent a smaller share of acetylene black consumption than electric vehicle batteries, the segment is expanding as project developers seek batteries with longer service life and more stable performance over frequent charge-discharge cycles. This introduces a different set of priorities: durability, consistency, and cost efficiency over extended operational horizons. Suppliers that can demonstrate value across both high-energy mobility applications and long-duration storage applications are expanding their addressable market beyond a single end-use vertical.
Supply Chain Reconfiguration and Cost Structure Dynamics
The supply chain for conductive acetylene black is undergoing geographic and structural change. Traditional supply hubs remain important, but new production capacity is being added in regions selected for feedstock proximity, customer access, and logistics efficiency. This is particularly visible in the establishment of dedicated acetylene black facilities that are designed to serve regional battery manufacturing ecosystems.
A notable example is the construction of a new acetylene black production facility in Texas, intended for battery-grade conductive additives. Once operational, the plant is expected to combine with existing European capacity to substantially increase total manufacturing output and improve service levels for North American and global customers. Its development is supported by long-term acetylene supply arrangements with a neighboring industrial site, highlighting how feedstock integration can reduce cost volatility and improve supply reliability. Projects of this type signal a broader trend: capacity expansion is increasingly tied to feedstock security, regional customer proximity, and the ability to qualify materials within demanding automotive supply chains.
At the same time, financing and partnership structures are evolving to support growth. In one recent case, a major public lender provided financing to support a joint venture focused on acetylene black manufacturing and sales for lithium-ion and next-generation batteries. Such arrangements reflect the capital intensity of scaling capacity and the importance of aligning funding with regional demand strategies. They also demonstrate how established players are using partnerships and joint ventures to extend geographic reach while maintaining technical control over product quality.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a small group of well-established producers and a set of strategic moves designed to protect differentiation while expanding reach. Leading companies are not simply competing on volume; they are building position around purity, application engineering, regional supply, and feedstock-backed capacity.
Denka Company Limited stands out for its focus on ultra-pure acetylene black designed specifically for lithium-ion and next-generation batteries. Its product strategy emphasizes minimal metallic impurities, high electrical conductivity, and strong electrolyte retention, all of which are directly relevant to performance-sensitive cell programs. Denka has also been extending its manufacturing footprint through a joint venture in Thailand, creating an additional production base to support stable supply amid rising global demand. Complementing this geographic expansion, the company has pursued support for lower-carbon acetylene mass-production technology, aligning product quality with evolving sustainability expectations.
Orion Engineered Carbons is pursuing a different but complementary strategy centered on regional capacity expansion and integrated feedstock access. Its battery-grade acetylene-based conductive carbon black is positioned for lithium-ion applications, with production operations in France and a major new facility under construction in Texas. The Texas project is intended to meaningfully increase effective manufacturing capacity for acetylene-based additives, supported by a long-term acetylene supply relationship with a neighboring chemical site. This approach illustrates how established carbon black producers can leverage site integration, regional customer proximity, and process scale to strengthen their position in the battery materials segment.
IRPC Public Company Limited has focused on premium-grade acetylene black for use as conductive carbon in battery manufacturing, emphasizing product quality and reliability within its regional operating context. Soltex Inc. serves the market by supplying acetylene black raw materials for lithium-ion and other battery applications, with a product range that supports multiple grades and use cases. These suppliers demonstrate that the market is not limited to a single business model; there is room for producers with different scale positions, regional advantages, and level of vertical integration, provided they can meet specification requirements and qualification standards.
Binders for Lithium Ion Batteries Market
Several developments in recent years highlight how these strategies are playing out in practice. Orion has showcased its new Texas facility as a key step in expanding battery-grade acetylene black capacity, with production expected to begin in the second quarter of 2026. Denka has meanwhile advanced its Thai joint venture with financing support, reinforcing its intent to scale manufacturing and sales capabilities for battery-grade acetylene black and next-generation applications. Together, these moves indicate a market where capacity expansion is accelerating, but where expansion is also increasingly tied to feedstock security, regional service, and sustainability positioning.
Looking at broader structural trends, the competitive landscape appears likely to evolve along three directions. First, integration and scale will continue to matter, particularly for suppliers that can ensure feedstock continuity and manage the capital demands of new capacity. Second, differentiation will increasingly depend on technical service, purity control, and the ability to support customer qualification across diverse cell designs. Third, the market may see selective new entry or capacity-led pressure in specific regions, especially where local demand growth and feedstock availability create favorable conditions. However, full commoditization is unlikely in the near term because battery manufacturers continue to reward suppliers that can deliver consistent performance, low impurities, and credible sustainability credentials.
Future Trends and Commercial Implications
Over the next three to five years, the conductive acetylene black market is likely to be shaped by the intersection of performance requirements, decarbonization pressure, and regional supply chain build-out. Three trends stand out.
The first trend is the widening gap between standard and premium conductive additives. As cell designs become more advanced and qualification standards tighten, battery manufacturers will increasingly distinguish between general-purpose carbon black and tailored grades that offer higher purity, better electrolyte retention, and more controlled morphology. This will reward suppliers that invest in application engineering and consistent manufacturing quality, while pressuring those that remain competing primarily on price in undifferentiated segments.
The second trend is the growing commercial relevance of lower-carbon production pathways. Even where regulatory mandates are not yet explicit, procurement teams are beginning to consider carbon intensity as part of multi-criteria supplier evaluation. Suppliers that can verify lower-emission acetylene routes, efficient processing, and transparent lifecycle data will be better positioned to participate in premium programs and long-term partnerships. The practical opportunity here is not just environmental; it is commercial differentiation in a market where sustainability claims must be substantiated by process and sourcing choices.
The third trend is a more regionally balanced supply footprint. Demand growth is not uniform across geographies, and battery manufacturers increasingly prefer suppliers that can deliver consistent volumes with shorter logistics loops and stronger local technical support. As new capacity comes online and joint ventures expand, the market may become less dependent on a narrow set of supply origins. This could improve supply resilience for buyers while also raising the bar for competitors that cannot match regional responsiveness or feedstock security.
These trends create commercial opportunities for suppliers that can combine product performance with supply reliability and credible sustainability attributes. For buyers, the opportunity lies in securing qualified materials early, aligning formulation strategies with evolving cell designs, and reducing exposure to single-source risk. The main uncertainties include the pace of new capacity commissioning, potential volatility in feedstock availability and cost, and the possibility that demand growth diverges from current expectations if vehicle adoption patterns or energy storage deployment shift. Any of these factors could alter pricing dynamics and the relative attractiveness of different capacity investments.
Strategic Actions for Decision-Makers
For battery material manufacturers and additive suppliers, the priority is to align product development with the performance and sustainability expectations of next-generation cells. This means investing in ultra-pure grades, improving process consistency, and building the technical service capabilities needed to support qualification across multiple customer platforms. Suppliers should also evaluate feedstock strategies carefully, since long-term access to reliable acetylene sources and lower-carbon production options can become a durable competitive advantage rather than a peripheral consideration.
For investors, the market offers exposure to a structurally growing segment, but returns will depend on choosing the right entry points and business models. Capacity expansion alone is not a guaranteed path to value creation if it is not supported by feedstock integration, regional demand alignment, and differentiated product positioning. Due diligence should focus on qualification status, customer concentration, sustainability credentials, and the credibility of expansion timelines. Projects that combine technical differentiation with defensible supply chains are more likely to translate market growth into durable margin potential.
For procurement and supply chain leaders, the strategic imperative is to move beyond short-term price optimization and build resilience into conductive additive sourcing. Multisourcing strategies, early qualification of alternative grades, and close collaboration with suppliers on formulation and performance requirements can reduce risk in high-volume programs. Procurement teams should also consider how carbon intensity and supply continuity may affect future sourcing criteria, particularly in markets where battery customers are extending sustainability expectations through the value chain.
Given the speed at which capacity plans, qualification pipelines, and sustainability expectations are evolving, decision-makers benefit from detailed, segmented data on demand by region and application, product form dynamics, and supplier-level capacity and strategy. A comprehensive market study can help translate these trends into more precise sourcing plans, investment theses, and product roadmaps. For those evaluating next steps, accessing the full report provides a deeper view of segmentation, competitive positioning, and the operational and commercial variables that will shape the market through the end of the decade.
For detailed analysis of this topic, please visit the official page: Worldwide Conductive Acetylene Black for Li-ion Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com