

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
N-Hexadecane Market: How 4.8% CAGR and Asia Pacific’s Lead Redefine Industry Growth

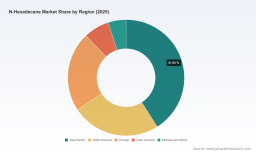
Global N-Hexadecane Market Outlook: Strategic Trends and Commercial Opportunities Through 2032
Market Dynamics: Navigating Growth Amid Structural Challenges
The global n-hexadecane market has demonstrated steady expansion over the past half-decade, with total revenue climbing from approximately 172.5 million USD in 2020 to 218.45 million USD in 2025. This progression reflects a compound annual growth rate of 4.8 percent across the assessment window, positioning the sector for continued expansion through the 2026–2032 forecast horizon. By 2032, market valuation is projected to approach 303 million USD, representing a meaningful acceleration in absolute revenue terms despite a moderation in growth pace during the latter half of the forecast period.
Commercial scale alone does not capture the underlying dynamics shaping demand. The market operates within a moderately concentrated environment, where the largest three participants command roughly 42.8 percent of total revenue and the top five collectively control 58.5 percent. This concentration structure creates a landscape where established players retain pricing influence and customer relationships, yet significant headroom remains for specialized producers and regional distributors to capture niche volumes. The balance between scale economies and application-specific customization remains one of the defining features of the competitive environment.
Several structural challenges and inflection points currently test the resilience of market participants. Sourcing constraints tied to petroleum-derived feedstock availability continue to introduce volatility, particularly as refining margins fluctuate and downstream separation processes face tighter energy and efficiency requirements. The reliance on fractional distillation from crude oil streams means that n-hexadecane pricing and supply consistency are indirectly linked to broader crude market behavior, geopolitical supply disruptions, and regional refining capacity utilization. Companies that depend on single-source feedstock channels or operate without hedging mechanisms find themselves exposed to margin compression when input costs rise unexpectedly.
Quality differentiation has also emerged as a critical battleground, particularly as downstream users demand tighter specifications for analytical, regulatory, and thermal management applications. Higher purity grades require additional refinement steps, more rigorous quality control, and consistent batch-to-batch reproducibility, all of which raise production complexity. Firms that cannot reliably deliver above-99 percent purity with certified documentation risk losing contracts to competitors that have invested in process control, analytical verification, and compliance readiness. This purity divide is widening, and it increasingly determines which companies can access premium revenue pools versus those confined to commoditized volume segments.
PW Consulting
A third tension centers on regulatory framing and end-use perception. While n-hexadecane serves primarily industrial, analytical, and research applications, its presence in certain food-contact and nonfood-article testing frameworks means that regulatory expectations around documentation, purity certification, and traceability carry weight beyond traditional chemical supply chains. Buyers in regulated sectors increasingly require suppliers to demonstrate alignment with recognized standards, which raises the compliance burden for manufacturers and distributors that lack established quality systems. At the same time, this regulatory visibility can function as a barrier to entry that protects capable incumbents from undifferentiated competition.
Core Drivers Reshaping Demand and Supply Structures
Technological innovation in phase change materials and thermal energy storage represents one of the most consequential demand-side catalysts. As industries seek compact, stable, and predictable heat storage solutions, n-hexadecane's favorable melting behavior and chemical stability have positioned it as a reference compound and functional component in thermal management formulations. Advanced building materials, electronics cooling systems, and controlled-temperature packaging are among the application areas where phase transition performance directly influences product design. Continued R&D activity around composite phase change materials, encapsulation techniques, and integration with renewable heating and cooling systems is expanding the addressable use cases for high-purity n-hexadecane, reinforcing demand beyond traditional laboratory and analytical volumes.
Parallel innovation is occurring in analytical reference standards and combustion quality testing. The compound's well-defined physical properties make it a valuable benchmark for gas chromatography, diesel combustion evaluation, and purity testing of related substances. Laboratories and industrial testing operations increasingly require tightly controlled reference materials to support compliance, process optimization, and product validation. This demand profile favors suppliers that can deliver certified specifications, lot-specific documentation, and consistent assay results. Companies that align their manufacturing and quality assurance capabilities with these expectations are capturing a growing share of high-margin reference-standard orders, creating a structural advantage over less specialized producers.
Policy and regulatory environments are progressively shaping procurement behavior, particularly where testing protocols intersect with safety, food-contact assessment, and industrial material evaluation. Regulatory specifications that reference n-hexadecane for mineral oil testing and synthetic fatty alcohol purity testing create a compliance-driven pull for documented purity grades. While the compound is not positioned as a direct food additive, its role in testing frameworks means that laboratories, manufacturers, and quality assurance teams must source materials that satisfy recognized specification expectations. This dynamic encourages procurement teams to prioritize suppliers with traceable documentation, established certification coverage, and clear standard alignments, gradually shifting purchasing decisions away from price-only comparisons toward value and compliance assurance.
Worldwide N-Tridecane Market
On the demand side, enterprise behavior is shifting toward longer-term supply partnerships rather than transactional spot purchasing. Buyers in analytical, industrial, and research segments are increasingly concerned with supply continuity, batch consistency, and technical support. This trend benefits distributors and manufacturers that can offer multi-country stocking, logistics coordination, and responsive service layers. As a result, companies that combine reliable production with flexible distribution capabilities are gaining preference in procurement decisions, especially in regions where localized inventory reduces lead times and mitigates shipping risk. The preference for dependable partners is especially pronounced in applications where a material interruption can delay testing cycles, product validation, or thermal system prototyping.
Cost and supply chain dynamics remain equally influential. Recent market observations from China indicate that domestic n-hexadecane pricing in the early months of 2026 has hovered in the range of roughly 17,000 to 18,000 yuan per ton, with a three-month average near 19,480 yuan per ton and short-term daily fluctuations. This pricing behavior underscores the sensitivity of the market to regional feedstock conditions, operational throughput, and short-term demand swings. Suppliers that manage production scheduling efficiently, control impurity profiles without excessive rework, and maintain disciplined inventory positioning are better equipped to preserve margins through price cycles. At the same time, cost structures are being reevaluated as buyers weigh purity premiums against total cost of ownership, particularly when lower-purity material introduces testing variability or application performance trade-offs.
Competitive Landscape: Positioning, Differentiation, and Structural Shifts
The competitive field is shaped by a mix of regional manufacturers, globally oriented distributors, and specialty chemical suppliers serving laboratory and industrial end markets. Production and export capacity concentrated in China provides a substantial base of supply, while distribution-oriented companies extend reach across multiple geographies through warehousing and logistics partnerships. Specialty producers in Japan and the United States add depth to the market by serving research, synthesis, and high-specification industrial applications with strong documentation and application support. This combination of manufacturing depth and distribution breadth defines the current landscape, where no single business model dominates every customer segment.
Leading players are differentiating along several axes. One is specification control and certification readiness. Manufacturers that emphasize assay consistency, impurity limits, and recognized standard alignments are better positioned to serve analytical and regulated testing segments. Another axis is supply chain reliability. Importers and distributors that maintain multi-country inventory, coordinate logistics, and offer flexible order fulfillment can reduce lead-time risk for buyers who prioritize continuity over the lowest unit price. A third axis is application orientation. Some suppliers tailor their positioning toward reference-standard and combustion-testing use cases, while others focus on solvent, intermediate, or thermal-management contexts. This segmentation allows companies to compete on technical fit rather than engaging solely in undifferentiated price competition.
The competitive dynamic is also evolving through consolidation pressure and selective new entry. Larger participants benefit from scale in production planning, bulk procurement, and regulatory documentation, which can make it difficult for smaller undifferentiated producers to compete on cost and compliance simultaneously. At the same time, specialty demand creates openings for new entrants that bring targeted purity capabilities, strong analytical support, or regional distribution advantages. The market is therefore not moving toward uniform concentration; instead, it is bifurcating into a scale-and-compliance tier and a specialty-and-service tier. Companies that can bridge both, or that excel in one while maintaining credible performance in the other, are likely to capture disproportionate share over the forecast period.
Geographic reach and supply chain structure further differentiate competitors. Firms with manufacturing bases in China benefit from feedstock proximity and established production infrastructure, but they must navigate export logistics, customer documentation expectations, and regional pricing dynamics. Distributors with global stocking models can respond faster to localized demand and offer buyers simplified sourcing across multiple markets, though they remain dependent on reliable upstream supply. Specialty chemical companies with established laboratory and synthesis channels can command premium positioning by delivering consistent quality and technical legitimacy, particularly for research-intensive customers. The interplay among these models suggests that future share shifts will be determined not only by production volume but also by the ability to reduce friction in procurement, testing, and compliance verification.
Worldwide N-Hexyl Alcohol Market
Forward Outlook: Three Defining Trends for the Next Three to Five Years
The first major trend is the continued elevation of purity and documentation as commercial differentiators. As thermal, analytical, and regulated testing applications expand, buyers will increasingly treat certified high-purity material as a requirement rather than an optional upgrade. This will reward producers with robust process control and traceability, while pressuring marginal suppliers to either improve quality systems or retreat to lower-specification volume channels. The commercial opportunity lies in building repeatable certification pathways, lot-level documentation, and application-specific specification packages that simplify procurement for technical buyers.
The second trend is the growing integration of n-hexadecane into thermal management and phase change material ecosystems. If development activity in building efficiency, electronics cooling, and temperature-sensitive logistics continues to advance, demand for reliable phase transition materials will strengthen. This creates a pathway for n-hexadecane to benefit from broader energy efficiency and thermal regulation trends, especially where its physical properties align with performance targets. The associated opportunity is to link supply planning with downstream formulation and integration cycles, enabling more predictable demand forecasting and longer-term customer engagement. The uncertainty here lies in the pace of commercialization for advanced phase change systems and the extent to which n-hexadecane-based solutions compete with alternative materials or blended formulations.
The third trend is supply chain localization and resilience planning. Recent pricing fluctuations and feedstock sensitivity have reminded buyers that reliance on single channels can expose operations to disruption and cost variability. Over the next few years, procurement strategies are likely to place greater weight on multi-source sourcing, regional inventory buffers, and supplier accountability for continuity. This favors companies that can demonstrate flexible fulfillment, transparent pricing dynamics, and the ability to maintain specification consistency across locations. The risk is that heightened localization expectations increase operational complexity and compress margins if not managed with disciplined logistics and production coordination.
Strategic Actions for Decision Makers
For manufacturers, the priority is to align purity capability with commercial positioning. Invest in process control and analytical verification that support above-99 percent specifications consistently, and structure documentation so it meets the expectations of regulated and testing-driven buyers. Where cost pressures exist, avoid competing on price alone; instead, differentiate through specification reliability, batch repeatability, and application-specific packaging of technical information.
For investors, focus on participants that combine scale with compliance readiness or that have clear specialty positioning in thermal management, reference standards, or regional distribution. The most resilient opportunities will likely belong to companies that can defend margins through specification value rather than volume competition, and that can demonstrate supply continuity in a feedstock-sensitive environment. Monitor pricing behavior, certification breadth, and customer diversification as indicators of competitive durability.
For procurement and supply chain leaders, treat sourcing as a risk-management decision as much as a cost decision. Evaluate suppliers on documentation quality, lot consistency, logistics flexibility, and the ability to support testing or application requirements without introducing variability. Where possible, maintain diversified sourcing paths and secure visibility into pricing trends and inventory positioning to reduce exposure to short-term market swings. Engaging with detailed market intelligence on segmentation, pricing dynamics, and supplier capability can sharpen sourcing strategy and support more confident capital and contract decisions.
For detailed analysis of this topic, please visit the official page: Worldwide N-Hexadecane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com