

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Molecular Sieve Washing and Drying Machine Market: Why 5.92% CAGR Changes Everything

Strategic Trends and Commercial Opportunities in the Global Molecular Sieve Washing and Drying Machine Market
Market Overview and Core Challenges
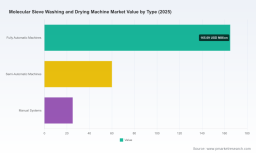
The worldwide molecular sieve washing and drying machine market has demonstrated consistent expansion over the past half-decade, transitioning from a niche industrial equipment segment to a strategically significant component across multiple manufacturing verticals. Valued at approximately 178.6 million USD in 2020, the market climbed steadily through 2021 and 2022, reaching 202.9 million USD as industrial demand for moisture-sensitive processing intensified. The upward trajectory accelerated noticeably in 2023 and 2024, with revenue crossing the 226.73 million and 235.35 million USD thresholds respectively, before settling at an estimated 250.28 million USD in the base year. Looking ahead, the forecast horizon through 2032 projects the market to scale to 374.35 million USD, reflecting a compound annual growth rate of 5.92 percent. This growth profile positions the segment as a mature yet structurally expanding market, where incremental innovation and regional demand shifts will dictate competitive outcomes rather than explosive volume surges.
Despite the favorable growth trajectory, the industry stands at a critical inflection point defined by three interconnected challenges. First, the transition from legacy drying architectures to fully integrated washing and drying systems has created operational friction for incumbent manufacturers. Companies that historically specialized in standalone molecular sieve regeneration units or discrete drying hoppers must now engineer closed-loop moisture management ecosystems that coordinate washing, separation, and low-temperature drying within unified machinery footprints. This architectural shift demands substantial retooling of design philosophies, supply chain coordination, and after-sales service frameworks, leaving many mid-sized players scrambling to align product portfolios with evolving buyer expectations.
Second, raw material volatility is reshaping cost structures across the equipment value chain. The construction of durable drying vessels, filtration housings, and precision frame components relies heavily on stainless steel grades that are subject to regional pricing divergence and macroeconomic demand swings. As industrial equipment manufacturers navigate fluctuating input costs, pricing strategies for end-user washing and drying machines have become increasingly complex, forcing vendors to balance margin preservation with competitive positioning in price-sensitive geographic markets. Equipment reliability expectations have simultaneously risen, meaning that cost-cutting shortcuts in material selection carry heightened reputational and performance risks for manufacturers.
Third, the application landscape is fragmenting in ways that strain traditional sizing and configuration models. Buyers across insulating glass production, industrial gas processing, and petrochemical operations each demand distinct moisture removal tolerances, throughput capacities, and sanitation protocols. A one-size-fits-all machine specification no longer satisfies procurement requirements, compelling equipment suppliers to develop modular architectures and application-specific tuning capabilities. This customization imperative increases engineering overhead and lengthens sales cycles, while simultaneously raising the barrier for new entrants who lack the technical depth to deliver validated, sector-tailored solutions.
Key Growth Drivers
The expansion trajectory of the molecular sieve washing and drying machine market is sustained by a cluster of interlocking drivers that extend beyond simple volume growth. At the forefront is a wave of technical innovation centered on low-temperature drying integration and energy optimization. Traditional high-temperature regeneration and drying methods have long dominated industrial practice, but recent engineering advances have demonstrated that molecular sieve-based low-temperature drying can achieve comparable moisture removal while reducing energy consumption and minimizing thermal stress on processed materials. This capability is especially relevant in environments where material integrity, color stability, or chemical composition must be preserved during moisture extraction. Equipment developers are increasingly embedding smart control algorithms, real-time humidity feedback loops, and hybrid thermal management systems into washing and drying machines, transforming them from mechanical workhorses into precision process instruments.
Policy and regulatory dynamics are amplifying the appeal of these efficiency-oriented systems. Environmental compliance frameworks across multiple jurisdictions are tightening standards around industrial energy usage, emissions associated with drying processes, and resource waste in manufacturing workflows. Facilities that rely on older, energy-intensive drying equipment face mounting pressure to document energy performance, reduce carbon footprints, and align with broader sustainability mandates. Molecular sieve washing and drying machines that deliver measurable reductions in thermal energy demand and process waste are increasingly positioned as compliance-enabling assets rather than optional upgrades. Procurement teams in regulated sectors now evaluate drying equipment through the lens of total cost of ownership, lifecycle energy consumption, and audit readiness, which shifts negotiations away from upfront purchase price toward long-term operational performance.
On the demand side, enterprise behavior is evolving as manufacturers prioritize process reliability and automation readiness. Moisture control is no longer viewed as a peripheral utility but as a critical determinant of downstream yield, product consistency, and operational continuity. This mindset is particularly visible in sectors that handle hygroscopic materials or operate moisture-sensitive gas streams, where even minor fluctuations in water content can trigger product defects, catalyst degradation, or process interruptions. Buyers are therefore seeking washing and drying machines that integrate seamlessly with automated production lines, offer predictive maintenance signals, and reduce manual intervention in sieve replacement or regeneration cycles. The result is a demand profile that favors equipment providers capable of delivering standardized performance baselines with configurable automation layers, rather than vendors restricted to fixed, manually intensive designs.
Supply chain and cost structure dynamics are simultaneously reshaping competitive conditions. The equipment manufacturing ecosystem depends on materials such as stainless steel for pressure vessels, structural frames, and corrosion-resistant internal components. Regional pricing disparities in these inputs create uneven cost bases across production locations, influencing where manufacturers locate assembly operations, how they price finished systems, and which customer segments they can profitably serve. At the same time, the broader industrial machinery ecosystem is experiencing renewed investment in automation components, filtration media, and precision sensors, which expands the availability of high-performance subsystems that washing and drying machine builders can incorporate. This subsystem proliferation enables faster product differentiation but also raises the technical coordination burden, as integrating externally sourced components into unified machines requires rigorous validation and compatibility testing.
Recent market activity reflects these drivers in tangible ways. At a major appliance and industrial equipment exhibition in Shanghai during early 2026, a flagship washer-dryer combination was introduced that integrates super hydrolysis with molecular sieve low-temperature drying, illustrating how the technology narrative is bridging consumer-facing appliance innovation and industrial process optimization. Around the same period, a prominent hardware manufacturer expanded into the washer-dryer category with a new series built around molecular sieve heat pump drying sets, signaling that the conceptual boundary between household appliance drying and industrial moisture management is becoming more porous in terms of technology adoption. On the industrial side, updates from purification technology specialists emphasize the broadening deployment of molecular sieve dryer systems to support automation and moisture-sensitive processes across diverse manufacturing sectors. These developments collectively indicate that molecular sieve drying is being recontextualized as a versatile enabling technology rather than a narrow industrial utility.
Competitive Landscape and Leading Strategies
The competitive structure of the molecular sieve washing and drying machine market is characterized by moderate concentration and a blend of specialized equipment manufacturers, established industrial component suppliers, and regional players with strong domain expertise. The market environment reflects a CR3 near 41.25 percent and a CR5 near 56.8 percent, suggesting that while leading firms hold meaningful share, a substantial portion of the market remains accessible to focused challengers and application-specific specialists. This structure rewards companies that can combine technical credibility with flexible commercial models rather than those relying solely on scale.
Among the companies shaping the competitive field, several distinct strategic positions have emerged. One Chinese manufacturer focused on plastic resin drying systems builds molecular sieve drying solutions that combine dehumidification, heat-preserving drying hoppers, cyclone filtration integration, and feeder components into cohesive machine platforms. This integrated approach targets processors who want a single source for drying architecture rather than pieced-together subsystems, emphasizing compatibility and simplified installation. Another China-based producer with nearly three decades of experience in compressed air purification has built its positioning around high-quality molecular sieve air dryers and desiccant drying equipment, leveraging long-standing domain familiarity and a product lineage tuned to air and gas purification requirements. Its competitive advantage lies in process familiarity and an established understanding of moisture removal standards in compressed air applications.
In the Americas, a U.S.-based company has carved out a differentiated role by supplying molecular sieve desiccants designed specifically for regenerative dryers in industrial gas and air drying contexts. Rather than competing purely on machine manufacturing, this player strengthens its relevance through material-grade specificity, particularly with sodium aluminosilicate-based options tailored for regenerative performance. Its strategy illustrates how control over the desiccant specification layer can anchor customer relationships and create downstream attachments to broader drying systems. Meanwhile, an India-based manufacturer and supplier offers molecular sieve dryers for industrial process applications in both standard and custom-built configurations, positioning itself as a flexible partner for buyers who need baseline reliability but also require adaptation to local operating conditions or plant layouts. This dual standard-and-custom model enables the company to serve a broad customer base while retaining higher-margin opportunities in specialized orders.
PW Consulting
A large multinational filtration and separation company reinforces the equipment ecosystem from a protection and support angle, providing high-efficiency coalescers and systems that safeguard molecular sieve dryers in refinery and hydrocarbon gas drying processes focused on water removal. Its role highlights a critical competitive dimension: molecular sieve performance depends heavily on upstream contamination control, and companies that can ensure cleaner feed streams or extend sieve life indirectly shape buying decisions across the equipment chain. This dynamic creates partnership and bundling opportunities between machine manufacturers and upstream protection specialists, especially in hydrocarbon and chemical processing environments where maintenance cost and sieve replacement frequency are major concerns.
Molecular Sieve Adsorbents Market
Strategic differentiation across the competitive set tends to cluster around three axes. The first is technological integration, where leaders combine drying, filtration, heat management, and control logic into cohesive machines that reduce installation complexity and improve operational predictability. The second is application specialization, where companies align product documentation, validation data, and service support with specific industries such as insulating glass production or industrial gas processing, thereby reducing procurement risk for sector buyers. The third is supply chain and service reach, where vendors leverage regional presence, rapid spare-part availability, and field engineering support to win long-term relationships in markets where downtime costs are high and local responsiveness matters more than list pricing.
The landscape is evolving through a combination of consolidation, segmentation, and calculated new entry. Consolidation pressures are likely to intensify as larger industrial equipment groups seek to add moisture management capabilities to their portfolios and as specialized manufacturers look for broader distribution or complementary product lines. At the same time, market segmentation is deepening because buyer requirements are diverging across applications and regions, enabling focused players to defend niches with superior application fit rather than competing head-to-head on general-purpose specifications. New entrants are most viable when they bring a clearly defined technology advantage, a strong regional service footprint, or a unique material and control-system combination that existing suppliers are slow to replicate. Companies that merely replicate existing drying hardware without differentiated performance, sanitation, automation, or service layouts face a challenging path to sustainable share.
Future Outlook for the Next Three to Five Years
Over the next three to five years, the molecular sieve washing and drying machine market is likely to be shaped by a small number of decisive trends that will separate adaptive players from those locked into legacy designs. The first trend is the accelerating integration of low-temperature drying and energy-recovery logic into mainstream equipment offerings. As energy costs remain a persistent concern and regulatory scrutiny around industrial efficiency increases, machines that can deliver reliable moisture removal with reduced thermal input will gain preference in procurement evaluations. This will push manufacturers to standardize heat pump-compatible architectures, smarter regeneration scheduling, and modular component layouts that simplify upgrades and reduce retrofit friction for existing installations.
A second trend is the widening of application coverage beyond traditional core uses. Molecular sieve drying systems are increasingly relevant in processes that demand precise moisture control for automation readiness, product consistency, and sensitive-material handling. As more manufacturing lines adopt closed-loop process control and quality traceability, washing and drying machines will be evaluated not only for throughput but also for their ability to provide stable, repeatable moisture outcomes that integrate with upstream and downstream automation. This expands the addressable scope for vendors who can document performance in moisture-critical environments and tailor control interfaces to plant-level systems.
A third trend is the intensification of regional cost and service dynamics. Differences in material pricing, labor availability, and local compliance expectations will continue to influence where equipment is engineered, assembled, and supported. Vendors that can localize service delivery, configure machines to regional material constraints without compromising reliability, and offer transparent total-cost-of-ownership models will be better positioned to capture share in price-conscious markets while maintaining margin discipline. The flip side is that macroeconomic divergence could pressure cross-regional pricing strategies and complicate supply planning for manufacturers operating across multiple sourcing environments.
Commercial opportunities emerging from these trends include bundled service agreements that pair equipment supply with predictive maintenance, sieve lifecycle management, and performance certification; modular product lines that allow buyers to start with baseline configurations and scale automation or filtration capability over time; and application-focused documentation that reduces procurement risk in sectors where moisture control is tied directly to yield and compliance. At the same time, uncertainty persists around raw material price swings, the pace of regulatory tightening in key regions, and the potential for fast-follower products to compress differentiation windows. Companies that treat these variables as manageable inputs rather than external surprises will navigate the next cycle more effectively.
Actionable Recommendations for Decision-Makers
For equipment manufacturers, the priority is to align product roadmaps with integrated low-temperature drying, automation-ready controls, and modular serviceability. Investing in application-specific validation data and clear documentation for moisture-critical use cases can materially shorten sales cycles and improve win rates against generic competitors. Manufacturers should also evaluate strategic partnerships with upstream filtration and contamination-control suppliers, since protecting sieve performance is increasingly part of the purchasing decision in refinery, gas, and chemical environments.
Zeolite Molecular Sieves Market
For investors, the market's moderate concentration and ongoing segmentation suggest selective opportunities in companies with defensible application fit, strong regional service capacity, and credible energy-efficiency differentiation. Due diligence should focus less on headline volume projections and more on unit economics, material cost exposure, service-margin trajectories, and the ability to convert technological advancement into repeatable commercial wins. Companies that have built proprietary control logic, validated low-temperature drying performance, or strong upstream protection integration warrant closer scrutiny than undifferentiated hardware assemblers.
For procurement and operations leaders, the most effective buying strategy centers on total cost of ownership, lifecycle energy performance, and service responsiveness rather than initial capital price alone. Evaluating machines for compatibility with automation systems, ease of sieve replacement, and documented performance in relevant application conditions can reduce operational risk and improve long-term reliability. Engaging suppliers early to align machine configuration with plant-specific moisture targets and sanitation requirements typically yields better outcomes than selecting off-the-shelf specifications after the fact.
For all stakeholders, the strategic value of detailed segmentation, pricing dynamics, and regional demand patterns cannot be overstated. Macro growth signals provide direction, but the real allocation decisions depend on granular insight into which applications, machine types, and geographic pockets are expanding fastest, where margins are most defensible, and how competitor movements are likely to reshape local pricing and service expectations. Comprehensive market intelligence that connects technology trends with commercial segmentation enables sharper capital deployment, more targeted product plans, and better negotiation leverage across the supply chain.
For detailed analysis of this topic, please visit the official page: Worldwide Molecular Sieve Washing and Drying Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com