

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Reinforced Polypropylene Market: Why 6.28% CAGR Through 2032 Changes Everything

Navigating the Reinforced Polypropylene Material Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
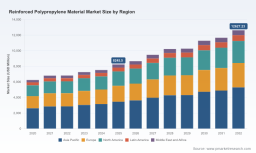
The global reinforced polypropylene material market demonstrates robust expansion characteristics, projecting a compound annual growth rate of 6.28% from a 2025 valuation exceeding USD 8.2 billion into the 2030s. Historical data confirms a resilient upward trajectory, with market value growing from approximately USD 6.25 billion in 2020 to nearly USD 7.5 billion by 2024. The forecast period extending to 2032 anticipates the market surpassing USD 12.6 billion, reflecting sustained industrial demand and technological maturation. This growth trajectory is underpinned by the material's ability to combine polymer flexibility with enhanced mechanical strength, making it indispensable across burgeoning industrial sectors.
Geographically, the market exhibits a heavily weighted distribution favoring the Asia Pacific region, which commands the largest share of total revenue. This dominance stems from concentrated manufacturing capabilities, rapid industrialization, and robust domestic consumption patterns in major economies. Europe and North America follow as significant contributors, driven by mature automotive supply chains and stringent performance standards that support the adoption of reinforced grades. Emerging regions in Latin America and the Middle East and Africa represent smaller but growing pockets of opportunity, often tied to infrastructure development and localized manufacturing investments.
Application-wise, the automotive sector remains the primary revenue engine, absorbing the largest portion of global consumption. This dominance is fueled by continuous efforts toward vehicle lightweighting, fuel efficiency improvements, and the shift toward electric mobility platforms that demand high-strength, low-weight materials. Household appliances constitute the second-largest segment, leveraging the thermal stability and electrical insulation properties of reinforced polypropylene for durable consumer goods. Electrical and electronics applications, along with industrial and construction uses, complete the demand landscape, each drawing on specific performance attributes aligned with end-use requirements.
Reinforcement technologies segment the market into distinct value pools, with glass fiber reinforced formulations capturing the dominant position. These materials offer a compelling balance of cost-effectiveness, mechanical enhancement, and processability, making them the default choice for high-volume manufacturing. Mineral reinforced variants serve niche applications requiring specific stiffness or thermal properties, while carbon fiber reinforced grades occupy premium positions where weight reduction and maximum structural integrity justify higher material costs.
Despite the optimistic growth outlook, the industry currently confronts several critical challenges that define the strategic inflection points for stakeholders.
Supply Chain Resilience and Input Cost Volatility
The cost structure of glass fiber reinforced polypropylene manufacturing is heavily skewed toward raw material inputs, with polypropylene resin and glass fiber costs accounting for over 80% of total production expenses. This concentration exposes producers to significant margin risk when feedstock prices fluctuate. Recent market analysis indicates European polypropylene prices for injection moulding grades rose approximately 3% in the first quarter of 2025, driven by expanding feedstock propylene costs. Such price movements directly impact downstream compounding economics and can disrupt long-term supply agreements if not hedged or managed through strategic sourcing.
Polypropylene Pipes Market
Regional Supply-Demand Imbalances
The propylene industry in China exemplifies the complex supply dynamics facing the market. Capacity reached 77.58 million tons in 2025, creating a supply-demand imbalance that exerts downward pressure on prices impacting downstream reinforced polypropylene producers. While lower input costs might appear beneficial, such imbalances can signal overcapacity risks, price wars, and margin compression across the value chain. Producers operating in or dependent on Chinese supply chains must navigate these pricing pressures while maintaining product quality and service levels.
Regulatory and Trade Policy Uncertainty
Trade policy shifts introduce additional layers of complexity to the market. U.S. reciprocal tariffs implemented in 2025 include additional duties on certain plastic resins and petrochemical feedstocks, with uneven impacts across Chapter 39 HTS codes for polymers. Separately, the U.S. imposed full tariffs on PET and recycled PET imports effective September 2025 under specific HS codes, creating potential spillover effects on related polymer supply chains. These regulatory developments necessitate proactive supply chain reconfiguration, tariff engineering, and diversification strategies to preserve cost competitiveness and market access.
Key Drivers of Market Transformation
The reinforced polypropylene market is not merely expanding; it is being reshaped by interconnected forces that demand strategic agility from participating companies. Understanding these drivers is essential for identifying where value will be created over the forecast period.
Technological Innovation in Reinforcement Architectures
Material science advancements are redefining what reinforced polypropylene can achieve. The introduction of long fiber thermoplastic formulations marks a significant departure from traditional short-glass fiber approaches, offering superior mechanical properties and enabling structural applications previously dominated by metals. In early 2025, Polyplastics launched Plastron LFT, a long fiber thermoplastic polypropylene with glass fibers, emphasizing environmental benefits for reinforced applications. This product underscores a dual industry imperative: performance enhancement coupled with sustainability alignment. Long fiber technologies allow for reduced wall thickness in molded components, contributing to weight savings and material efficiency without sacrificing strength.
Parallel developments in additive technology are enabling finer control over compound properties. The collaboration between LCY Company and Milliken & Company in January 2026 produced the 737U high-performance polypropylene grade, enhanced with additive technology suitable for reinforced compound applications in automotive parts and containers. Such grades demonstrate how targeted molecular and additive engineering can expand the functional envelope of reinforced polypropylene, addressing specific processing challenges or performance requirements that generic grades cannot meet.
For manufacturers, these innovations represent both opportunities and imperatives. The ability to offer differentiated grades with proven performance advantages creates competitive moats and opens doors to higher-value applications. However, it also demands investment in compounding expertise, quality assurance, and application support capabilities to translate material properties into customer value.
Regulatory Pressures and Sustainability Mandates
Environmental regulations and corporate sustainability commitments are accelerating material substitution trends that favor reinforced polypropylene. Automotive OEMs face increasingly stringent emissions standards and fuel economy targets, making lightweighting a non-negotiable engineering priority. Reinforced polypropylene compounds, particularly glass fiber reinforced variants, enable the replacement of heavier metal components with plastics that maintain structural integrity while reducing overall vehicle weight.
Circular economy initiatives are also influencing material development roadmaps. Leading producers are integrating recycled content, bio-based feedstocks, and design-for-recyclability principles into their product portfolios. This shift is not purely altruistic; it aligns with customer procurement policies, regulatory requirements in key markets, and brand positioning strategies. Companies that proactively develop sustainable reinforced formulations will find themselves better positioned for contracts requiring environmental attribute verification or carbon footprint assessments.
However, sustainability transitions carry execution risks. Achieving consistent quality with recycled inputs, validating performance in demanding applications, and navigating varying regulatory definitions of recyclability require technical rigor and supply chain coordination. Premature claims or inconsistent execution can damage credibility and erode customer trust.
Demand-Side Evolution in Automotive and Industrial Sectors
Consumer and enterprise behavior is driving nuanced demand patterns. In the automotive space, the transition to electric vehicles is altering component design priorities. Battery enclosures, structural reinforcements, and lightweight body panels demand materials that offer impact resistance, thermal stability, and electrical insulation. Reinforced polypropylene grades are being evaluated and adopted for these roles, supported by long-term testing and validation programs that build confidence among design engineers.
The industrial and construction sectors are experiencing renewed interest in composite materials for infrastructure projects, equipment housings, and corrosion-resistant components. Economic development initiatives in emerging markets stimulate demand for durable, low-maintenance materials that can withstand harsh environments. Reinforced polypropylene, with its corrosion resistance and mechanical versatility, appeals to specifications that were historically filled by metals or more expensive engineering thermoplastics.
In household appliances, consumer expectations for durability, aesthetic finish, and energy efficiency continue to push manufacturers toward materials that can support thinner walls, complex geometries, and consistent performance over long service life. Reinforced grades contribute to these goals by enhancing stiffness and heat resistance, enabling design freedom without compromising reliability.
Supply Chain and Cost Structure Dynamics
Beyond raw material costs, broader supply chain dynamics are reshaping competitive positioning. The concentration of polypropylene production capacity in specific regions, coupled with geopolitical factors and trade policy developments, influences availability and pricing on a global scale. Producers with diversified sourcing strategies, regional compounding footprints, or vertical integration advantages are better insulated from localized disruptions.
Conversely, smaller or regionally concentrated players face the challenge of accessing competitive input costs while maintaining service levels expected by demanding customers. Strategic partnerships with resin suppliers, glass fiber manufacturers, or additive providers can mitigate some of these pressures, provided relationships are structured to ensure reliability and cost transparency. Logistics costs, inventory management, and lead time variability further complicate the cost equation, requiring disciplined operational execution and demand forecasting capabilities.
Competitive Landscape and Leading Strategies
The market structure is characterized by a mix of global giants, regional specialists, and technology-focused compounders. Concentration metrics indicate a moderately fragmented landscape where no single entity dominates, yet leading players exert significant influence through scale, technology portfolios, and customer relationships.
Strategic Positioning of Incumbent Players
Large multinational producers leverage their global reach and integrated capabilities to serve diverse customer bases across multiple regions. LyondellBasell Industries Holdings B.V. operates as a major global producer of polypropylene compounds, including glass fiber reinforced and mineral reinforced grades tailored for automotive, industrial, and consumer applications. Its advanced compounding capabilities and sustainability-focused offerings position it to serve customers seeking both performance and environmental alignment.
SABIC offers short-glass fiber-reinforced polypropylene compounds such as G3430X and G3440X grades optimized for automotive interior, exterior, and under-hood applications, emphasizing improved processing, performance, and lightweighting. Such targeted product development demonstrates how incumbents translate application insights into value propositions that resonate with specific customer pain points.
Borealis AG specializes in polypropylene compounds including glass fiber reinforced variants for automotive and industrial sectors, focusing on high-performance materials and circular economy solutions. Mitsui Chemicals, Inc. produces reinforced polypropylene compounds, including long glass fiber reinforced grades for mobility and automotive applications, with expansions in compounding facilities. This geographic and technological expansion reflects a strategy of being closer to growing demand centers while building differentiated capabilities.
Sumitomo Chemical Co., Ltd. supplies high-performance polypropylene compounds and reinforced grades for automotive materials, supported by production facilities catering to global mobility sector needs. Kingfa Sci. & Tech. Co., Ltd. stands as a leading manufacturer of reinforced polypropylene compounds, including glass fiber and modular glass fiber reinforced formulations for diverse industrial and automotive uses. The presence of strong regional players like Kingfa underscores the importance of local market knowledge, responsive service, and cost-competitive manufacturing in capturing share within high-growth regions.
Technology Specialists and Niche Innovators
A parallel tier of companies competes through engineering depth and customization. LG Chem produces polypropylene compounds with reinforced variants for automotive and technical applications. Mitsubishi Chemical Group Corporation develops and supplies glass fiber reinforced polypropylene compounds for mobility, including high-performance long glass fiber grades. Washington Penn Plastic Co., Inc. specializes in custom polypropylene compounds, including mineral and glass fiber reinforced grades for automotive and industrial markets. RTP Company provides engineered thermoplastic compounds, including glass fiber reinforced polypropylene for structural and high-performance applications. Avient Corporation offers specialty polypropylene compounds with glass fiber reinforcement for demanding industrial and automotive uses.
Celanese Corporation supplies glass fiber reinforced polypropylene materials focused on engineering applications and lightweighting solutions. Trinseo S.A. manufactures polypropylene compounds including reinforced grades for automotive and specialty markets. Repsol produces polypropylene and reinforced compounds for various industrial sectors. TotalEnergies supplies polypropylene resins and compounds, including reinforced variants for packaging, automotive, and construction. These players illustrate the breadth of technological approaches and application focuses that coexist within the market.
The strategic difference lies in the balance between scale-driven cost efficiency and technology-driven differentiation. Large players pursue volume leadership and broad application coverage, while specialists compete on customization, technical support, and performance validation in demanding use cases. Both approaches can be viable, but each carries distinct execution requirements and risk profiles.
Long Glass Fiber Reinforced Polypropylene Market
Market Evolution Trends
Several structural trends are shaping how competition will unfold. Vertical integration is gaining attention as companies seek to control critical input costs and secure supply continuity. Partnerships and joint ventures are emerging as vehicles to access new technologies, geographic markets, or application expertise without full capital commitment. The recent product launches by Polyplastics, SABIC, and the LCY-Milliken collaboration reflect an industry culture of continuous innovation, suggesting that innovation cycles are accelerating and that companies must maintain active development pipelines to stay relevant.
Market consolidation may continue in select segments where scale advantages become decisive, particularly in regions with high energy or logistics costs. However, fragmentation is likely to persist in specialty niches where customization and service responsiveness outweigh pure cost considerations. New entrants may arise from adjacent material sectors or from regional players expanding their compound portfolios, adding competitive pressure and pushing incumbents to justify their value propositions beyond brand recognition.
Future Trends and Commercial Opportunities
Looking ahead three to five years, several trends will define the market trajectory and create actionable opportunities for stakeholders who align their strategies appropriately.
Accelerated Adoption in Electrified Mobility Applications
As electric vehicle platforms proliferate, reinforced polypropylene will see expanded use in battery housings, structural components, and under-hood parts where thermal and mechanical demands intersect. Long glass fiber grades are particularly well-positioned to capture this demand, offering higher strength and stiffness than short-fiber alternatives. Opportunities exist for compounders who can provide validated grades with consistent quality, comprehensive technical support, and clear value cases demonstrating total cost of ownership benefits beyond unit price.
However, EV adoption rates vary by region, and platform designs differ significantly among OEMs. This heterogeneity means that material suppliers must maintain flexibility in their product portfolios and remain responsive to evolving specification requirements. Overcommitting to a single application or platform standard carries the risk of stranded inventory or obsolete formulations if designs change.
Performance Benchmarking Against Engineering Thermoplastics
Reinforced polypropylene will increasingly be evaluated against higher-cost engineering thermoplastics in applications where weight reduction and cost efficiency are paramount. Advances in long fiber technology and additive packages are narrowing the performance gap in certain structural and semi-structural roles. If this trend continues, reinforced polypropylene could displace more expensive materials in a broader range of components, expanding its addressable market.
This shift presents opportunities for producers to develop application-specific grades that clearly outperform traditional polypropylene and compete credibly with engineering alternatives. Success will depend on rigorous testing data, application engineering support, and the ability to demonstrate measurable benefits in real-world conditions. Failure to invest in such capabilities could leave reinforced polypropylene confined to lower-performance applications and vulnerable to displacement by premium grades.
PW Consulting
Sustainability as a Competitive Differentiator
Environmental attributes will transition from optional enhancements to expected baseline characteristics in many customer procurement processes. Carbon footprint reductions, recycled content sourcing, and circular design principles will influence supplier selection, particularly in automotive and consumer goods sectors where brand and regulatory scrutiny are high. Companies that proactively measure, validate, and communicate the environmental performance of their reinforced formulations will gain advantage in tenders and long-term supply agreements.
The opportunity lies not only in offering sustainable materials but in helping customers meet their own sustainability targets. Co-development projects, life cycle assessments, and transparent reporting can position a supplier as a strategic partner rather than a transactional vendor. The risk is that sustainability claims must be substantiated; inconsistent data, unverified assertions, or failure to meet emerging regulatory definitions can erode credibility and expose companies to reputational and compliance issues.
Actionable Strategies for Decision-Makers
The reinforced polypropylene market offers substantial growth potential, but realizing it requires precise strategic positioning and informed execution. Different stakeholder groups face distinct imperatives based on their roles in the value chain.
For Material Manufacturers and Compounders
Invest in long fiber and advanced additive technologies to differentiate your portfolio and access higher-value applications. Establish rigorous validation programs that provide customers with confidence in performance under real-world conditions. Develop supply chain flexibility to manage input cost volatility, including diversified sourcing, strategic hedging, and regional compounding footprints that reduce logistics exposure. Align product development with sustainability expectations, ensuring that environmental claims are backed by verifiable data and consistent with evolving regulatory frameworks.
For Investors and Strategic Planners
Evaluate companies based on technology differentiation, application support capabilities, and regional market positioning rather than scale alone. Look for players with active innovation pipelines, demonstrated customer co-development engagements, and cost structures that can withstand raw material price cycles. Consider the potential for consolidation in segments where scale becomes critical, but remain attentive to niche players who command premium positioning through specialization. Assess exposure to trade policy developments and regional supply-demand imbalances that could impact margin trajectories.
For Procurement and Supply Chain Leaders
Engage suppliers early in component design to explore lightweighting and performance opportunities enabled by reinforced polypropylene. Demand transparent data on material properties, processing behavior, and sustainability attributes to support informed specifications. Diversify sourcing where feasible to mitigate exposure to regional cost volatility or supply disruptions, and include flexibility clauses in contracts to accommodate evolving requirements. Build internal technical capability to evaluate and validate new grades efficiently, reducing reliance on supplier assessments alone.
The reinforced polypropylene market is dynamic and multifaceted, with technology evolution, regulatory shifts, and regional dynamics converging to shape competitive outcomes. Decision-makers who invest in deep market intelligence, maintain proactive supplier relationships, and align their strategies with emerging performance and sustainability requirements will be best positioned to capture value as the market evolves toward 2032 and beyond. Detailed segmentation data, regional analysis, and customized strategic guidance are available in the full comprehensive research report for organizations seeking to translate these insights into precise action plans.
For detailed analysis of this topic, please visit the official page: Worldwide Reinforced Polypropylene Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com