

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
SAS-RAID Controller Market: Why 4.6% CAGR and 84.5% Concentration Redefine 2032 Outlook

Global SAS-RAID Controller Market: Navigating the Inflection Point Toward 2032
The worldwide SAS-RAID controller market has entered a decisive phase of evolution. Valued at 2,620.0 million in 2020, the market expanded to 3,350.0 million by 2025, reflecting a compound annual growth rate of 4.6 percent across the 2026-2032 forecast horizon. This trajectory signals sustained demand, yet the growth path is uneven and increasingly shaped by technological transitions, infrastructure modernization cycles, and structural supply constraints. For enterprise decision makers, the market represents both a stable foundation for storage architectures and a shifting landscape where legacy assumptions no longer hold. The next several years will reward organizations that align procurement, product roadmaps, and investment thesis with the underlying forces reshaping controller capabilities, interface standards, and deployment models.
Despite the clear upward trajectory, the sector faces three structural challenges that demand strategic attention. First, the transition from mature 12Gb/s SAS to higher-speed 24Gb/s and Tri-Mode architectures is creating a dual-track environment. Organizations must balance the operational reliability of installed bases against the performance and future-proofing requirements of new deployments. Second, semiconductor supply dynamics continue to influence product availability and lead times, with MCU lead times averaging 13 to 14 weeks in August 2025 amid ongoing constraints for components used in controller designs. These delays affect time-to-market for new controller revisions and complicate capacity planning for channel partners. Third, the concentration of market share among a small group of incumbents, with the top three players accounting for 84.5 percent and the top five reaching 92.15 percent, limits price competition but raises dependency risks for customers seeking multi-vendor flexibility or specialized form factors. Together, these forces create a market that is growing steadily but requires disciplined navigation to avoid stranded investments or supply-driven disruptions.
Strategic Context: What the Numbers Reveal
The market's expansion from 2020 through 2025 demonstrates resilience, but the forecast period through 2032 highlights a more complex pattern. Growth is expected to accelerate in certain intervals, with notable upward movement projected around 2029 and sustained gains into the early 2030s. This non-linear path reflects the interplay of data center capacity additions, refresh cycles for enterprise servers, and the gradual retirement of slower interface generations. For strategists, the takeaway is that aggregate growth masks segment-specific timing differences. Organizations that treat the market as a single block risk misaligning product introductions, procurement cycles, and capacity commitments. A more effective approach segments decision making by interface readiness, deployment environment, and supply risk tolerance.
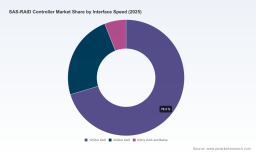
Regional dynamics further complicate the picture. Demand is distributed across multiple geographies, with the Asia Pacific region and North America representing substantial portions of total revenue, while Europe and the rest of world contribute meaningful but smaller shares. Application demand spans internet data centers, enterprise servers, and financial and government storage environments, each with distinct performance, redundancy, and compliance requirements. The product mix tilts toward external controllers, though internal controllers maintain a significant share, reflecting the coexistence of appliance-style storage and integrated server architectures. Interface speed distribution underscores the migration narrative: 12Gb/s SAS remains the volume leader, 24Gb/s SAS is gaining share in performance-sensitive deployments, and 6Gb/s SAS and below is being systematically phased out as vendors designate older series for end of life. This structure sets the stage for the drivers that will shape the next cycle.
Key Drivers Shaping the Market Trajectory
The market's direction is being pulled by a combination of technology breakthroughs, regulatory and policy shifts, demand-side behavior changes, and supply-side cost dynamics. These forces do not operate in isolation; they reinforce one another and create inflection points that separate organizations with clear roadmaps from those reacting late.
Technological Innovation: The Tri-Mode and 24Gb/s Shift
The most consequential technical development is the maturation of Tri-Mode controllers that integrate SerDes technology to manage SAS, SATA, and NVMe drives within a unified architecture. This capability bridges legacy storage investments with modern performance requirements, allowing data center operators to extend the useful life of installed media while incrementally introducing NVMe for latency-sensitive workloads. In parallel, 24Gb/s SAS-4 connectivity is becoming the standard for new enterprise deployments, with controller families like the Adaptec SmartRAID 3200 series designed to support comprehensive feature sets for data center environments. The broader adoption of PCIe 4.0 and 5.0 Tri-Mode solutions from major vendors further expands the performance envelope for direct-attached storage and hybrid configurations.
For decision makers, the implication is clear: interface speed is no longer a purely technical specification but a strategic lever. Organizations that standardize on 24Gb/s and Tri-Mode today reduce future migration friction, while those that delay may face longer transition windows and higher integration costs later. The technology trajectory also favors vendors that can deliver firmware maturity, broad drive compatibility, and robust management tooling, since performance gains are only realized when the surrounding software stack can exploit higher throughput without introducing bottlenecks.
Policy and Regulatory Environment: End-of-Life Designations and Compliance Pressures
Regulatory and vendor policy signals are accelerating obsolescence cycles and shaping procurement norms. Broadcom has designated all 6Gb/s MegaRAID SAS controllers and earlier series as end of life and end of support since 2020, a move that systematically pushes customers toward 12Gb/s, 24Gb/s, and Tri-Mode alternatives. This is not merely a product roadmap decision; it has operational consequences for organizations that rely on long-life hardware for compliance, audit, and continuity requirements. Financial and government storage environments, in particular, must align refresh plans with support windows and certification cycles, creating a clearer incentive to modernize earlier.
At the same time, data residency, security, and operational resilience expectations continue to influence storage architecture choices. Enterprises are increasingly prioritizing solutions that simplify firmware governance, reduce attack surface, and enable predictable update cycles. The trend favors suppliers that publish clear support calendars, provide documented migration paths, and maintain transparent compatibility matrices. In this environment, policy-driven obsolescence and compliance expectations converge to compress decision timelines and reward proactive planning.
Demand-Side Behavior: Infrastructure Refresh and AI-Adjacent Workloads
On the demand side, two behavioral shifts are reshaping purchasing patterns. First, enterprise servers and internet data centers are undergoing staggered refresh cycles that favor controllers capable of supporting mixed media environments and higher throughput. The growth of data-intensive applications, including analytics and AI-adjacent workloads, is increasing the need for storage subsystems that balance capacity, reliability, and expandability. Controllers that can scale within existing enclosures and support evolving drive mixes are gaining preference over narrowly specified alternatives.
Second, procurement teams are shifting from unit-cost optimization to total-cost-of-ownership and risk-adjusted evaluations. This change reflects a broader recognition that controller choice affects firmware maintenance, drive compatibility, expansion flexibility, and support continuity. As a result, buyers are weighting supplier stability, documentation quality, and update cadence more heavily than in prior cycles. The demand shift benefits vendors that can demonstrate consistent firmware delivery, broad qualification across drive families, and clear guidance for migration from legacy interfaces.
Supply Chain and Cost Structure: Component Constraints and Lead-Time Management
Supply-side dynamics remain a critical variable. MCU lead times averaged 13 to 14 weeks in August 2025 amid ongoing constraints for semiconductor components used in controllers. These lead times influence design-in decisions, inventory planning, and the pace at which new controller revisions can reach market. For manufacturers, the practical challenge is to balance performance upgrades with component availability, while for procurement teams the priority is to secure supply commitments that match deployment timelines. Cost structures are also affected by the need to qualify higher-speed transceivers, manage SerDes integration, and maintain firmware support across multiple generations. Organizations that coordinate supply planning with product roadmaps gain a measurable advantage in avoiding launch delays and stockouts.
Competitive Landscape and Leadership Strategies
The market is characterized by a concentrated set of established players, each pursuing distinct positioning strategies. Broadcom, headquartered in San Jose, California, offers MegaRAID SAS/SATA RAID controllers and HBAs, including PCIe 4.0/5.0 Tri-Mode solutions that support 24Gb/s SAS, SATA, and NVMe for enterprise direct-attached storage environments. Its recent documentation updates for storage solutions selection guides and Tri-Mode user guides in April 2026 reflect a focus on clarity and deployment guidance, reinforcing its position as a scale provider with broad enterprise reach.
Microchip Technology, based in Chandler, Arizona, competes through the Adaptec SmartRAID portfolio, with the 3200 series supporting 24G SAS-4 connectivity and the 3100 series addressing 12G deployments. Microchip's activity in 2025 and 2026 illustrates a dual strategy of incremental firmware refinement and targeted product expansion. Firmware version 03.01.44.40 for the SmartRAID 3200 and SmartHBA 2200 series was released in December 2025, addressing fixes and enhancements, while earlier firmware and software updates in May 2025 covered the SmartHBA 2100 and SmartRAID 3100 series. In August 2025, the company launched the Adaptec SmartRAID 4300 series of NVMe RAID storage accelerators aimed at scalable, secure solutions in AI data center environments. This sequence signals a deliberate push to extend the portfolio's relevance into higher-performance and AI-adjacent use cases while maintaining reliability improvements for existing deployments.
Marvell Technology, located in Santa Clara, California, supplies enterprise SAS I/O and RAID-on-Chip controllers targeted at mission-critical storage applications. Its value proposition centers on integration depth and reliability for workloads where availability and deterministic performance are paramount. Areca Technology Corporation, based in New Taipei City, Taiwan, manufactures SAS RAID adapters, including Tri-Mode Gen4 NVMe/SAS/SATA solutions and Thunderbolt RAID storage products, positioning itself around flexibility and specialized connectivity options. Advantech, also in Taipei, focuses on hardware RAID controllers for industrial and embedded computing applications, where environmental robustness and form-factor suitability matter more than raw throughput alone. ATTO Technology, headquartered in Amherst, New York, and HighPoint Inc., based in Fremont, California, round out the field with SAS/SATA RAID controllers and storage connectivity solutions for server and workstation environments, serving segments that value compatibility, configuration simplicity, and competitive pricing.
Differentiation and Strategic Positioning
The leaders differentiate along several axes. Scale vendors emphasize broad compatibility, documentation quality, and the ability to serve large enterprise deployments with predictable support cycles. Mid-tier and specialized players compete on targeted value propositions: industrial ruggedness, Thunderbolt connectivity, Tri-Mode flexibility, or embedded form factors. Across the field, firmware maturity has become a key differentiator because higher interface speeds and mixed-media environments amplify the consequences of software bugs and compatibility gaps. Vendors that publish regular updates, clarify migration paths from legacy series, and maintain transparent compatibility matrices are better positioned to retain enterprise trust.
PW Consulting
Another axis of differentiation is architecture alignment. Tri-Mode controllers with SerDes technology enable unified management of SAS, SATA, and NVMe drives, helping customers bridge legacy investments with modern storage needs. Vendors that articulate this bridging capability clearly can reduce perceived migration risk and accelerate adoption in environments where complete rip-and-replace is impractical. Conversely, suppliers that cling to narrower portfolios without clear upgrade pathways face pressure as end-of-life designations and interface transitions accelerate.
Market Structure Evolution: Consolidation Pressures and Niche Opportunities
The concentration profile of the market suggests that consolidation pressures will persist, particularly among customers who prioritize supply assurance and support continuity. At the same time, the diversity of deployment environments—from hyperscale data centers to industrial embedded systems—creates room for specialists to thrive in niches where general-purpose solutions underperform. New entrants are likely to focus on specific form factors, interface combinations, or software-managed storage experiences rather than attempting to compete head-on across the full enterprise spectrum. The overall trend points toward a core of dominant incumbents complemented by a resilient layer of specialists, with differentiation increasingly determined by firmware discipline, migration support, and supply reliability rather than headline specifications alone.
Future Trends and Strategic Opportunities (2026-2032)
Looking ahead, three trends are likely to define the market's evolution and open specific commercial opportunities.
-
Accelerated migration to 24Gb/s and Tri-Mode architectures. As legacy 6Gb/s series are retired and 12Gb/s deployments age, the share of 24Gb/s SAS and Tri-Mode controllers will continue to rise. This creates opportunities for suppliers that can provide clear migration roadmaps, broad drive compatibility, and management tooling that reduces integration friction. For customers, standardizing on these architectures early can shorten future refresh cycles and reduce the cost of mixed-media transitions.
Network Interface Controller Nic Market -
AI-adjacent and data-intensive workload expansion. The growth of analytics, inference, and other data-intensive workloads will increase demand for storage subsystems that balance capacity, reliability, and expandability. Controllers that scale within existing enclosures and support evolving drive mixes will see stronger uptake. Vendors that align product introductions with the operational realities of AI data center environments—such as the SmartRAID 4300 series—can capture early mindshare and qualification momentum.
-
Firmware-centric competition and supply assurance as strategic assets. As hardware specifications converge, competitive advantage will increasingly depend on firmware quality, update cadence, and the reliability of component supply. Organizations that treat firmware governance and supply-chain coordination as core capabilities, rather than backend tasks, will be better positioned to protect revenue and customer trust. Procurement teams that embed supply risk into evaluation criteria will reduce exposure to lead-time volatility.
Ethernet Controller Market
These trends also carry risks. Migration timelines may slip if component availability remains constrained or if compatibility validation reveals edge cases across drive families. Market growth could moderate if macroeconomic conditions slow data center capex or if alternative storage architectures gain traction in segments traditionally served by SAS-RAID controllers. Additionally, the high concentration among incumbents could create dependency concerns for customers seeking to diversify suppliers or negotiate more favorable terms. Decision makers should monitor interface adoption curves, firmware release patterns, and lead-time trends as leading indicators of near-term pressure points.
Actionable Recommendations for Decision Makers
For manufacturers and product leaders, the priority is to align roadmaps with the 24Gb/s and Tri-Mode transition while protecting the installed base through disciplined firmware delivery. This means publishing clear compatibility matrices, maintaining regular update cycles, and articulating migration paths from legacy series. Supply planning should be integrated into product launches, with explicit attention to MCU and transceiver availability to avoid timing gaps between design-in and volume production.
For investors, the market offers steady growth with pockets of acceleration tied to interface upgrades and AI-adjacent storage demand. Due diligence should focus on firmware maturity, support calendars, supply resilience, and the ability to serve mission-critical environments rather than on headline speed claims alone. Companies that can demonstrate consistent delivery, broad qualification, and credible bridging strategies between legacy and modern media are better positioned to sustain share in a concentrated market.
For procurement and IT leaders, the practical move is to evaluate controllers on total-cost-of-ownership, support continuity, and migration readiness rather than unit price in isolation. Prioritize suppliers that provide documented end-of-life schedules, transparent firmware release history, and clear guidance for mixed-media environments. Build supply commitments that match deployment timelines and consider multi-vendor coverage where feasible to reduce dependency risk without sacrificing performance requirements.
For organizations seeking a deeper read on segmentation timing, regional demand patterns, interface adoption curves, and company-level positioning, the full research report provides the granular data and scenario detail needed to translate these insights into procurement calendars, investment theses, and product roadmaps. The market is moving at a pace that rewards early clarity; the organizations that define their posture now will have more options when the next wave of interface transitions and workload shifts arrives.
For detailed analysis of this topic, please visit the official page: Worldwide SAS-RAID Controller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com