

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Phenolic Curing Agent Market: Decoding the 5.12% CAGR and Asia Pacific’s 417 Million Share

Navigating the Global Phenolic Curing Agent Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global market for phenolic curing agents is entering a phase of steady expansion, anchored by a projected compound annual growth rate of 5.12% from 2026 through 2032. Building on a base year valuation of 2025, the sector has demonstrated consistent annual revenue growth since 2020, reflecting the material's entrenched role in high-performance industrial applications. The trajectory suggests a maturing market that is nonetheless experiencing periodic inflection points driven by raw material volatility, regulatory shifts, and evolving end-use demands. Understanding these underlying currents is essential for stakeholders seeking to align capacity, pricing, and product development with long-term demand signals.
Three structural challenges are currently reshaping how manufacturers and buyers navigate this space. First, feedstock price instability has become a persistent operational concern. Phenol and formaldehyde, the foundational building blocks for most phenolic curing chemistries, have experienced pronounced price swings that ripple directly into production economics. Second, the regulatory environment is tightening around specific chemical formulations, introducing compliance overhead and prompting reformulation efforts across downstream applications. Third, demand fragmentation across multiple industrial verticals is creating uneven growth patterns, where high-value segments expand faster than commoditized applications, forcing suppliers to balance volume with margin protection. These dynamics collectively compress the window for reactive decision-making and elevate the premium on forward-looking market intelligence.
The market's concentration profile further underscores the importance of strategic positioning. A relatively small group of multinational producers accounts for a substantial share of global supply, while a broader tier of specialized and regional manufacturers competes on customization, toll production, and niche application expertise. This layered structure means that competitive advantage is rarely derived from scale alone. Instead, it emerges from the ability to manage input cost exposure, maintain regulatory agility, and align product portfolios with the functional requirements of high-growth end markets. For executives and investors, the immediate implication is clear: operational resilience and portfolio alignment are becoming as critical as raw production capacity.
Key Demand Drivers and Structural Shifts
Technological Innovation and Performance Optimization
Advancements in curing chemistry are steadily redefining the value proposition of phenolic agents. Formulators are increasingly prioritizing systems that deliver faster cycle times, lower peak cure temperatures, and enhanced thermal and chemical resistance without compromising mechanical integrity. These performance gains are particularly valuable in electronics encapsulation and advanced composite fabrication, where processing efficiency and final-part reliability directly influence total cost of ownership. Parallel developments in modified phenolic architectures and hybrid crosslinker systems are expanding the design space for engineers, enabling lighter, more durable components in demanding environments. As downstream manufacturers seek to reduce energy consumption during curing and extend service life in harsh conditions, suppliers that can translate formulation flexibility into measurable processing savings are capturing disproportionate attention.
Policy and Regulatory Evolution
Regulatory frameworks are exerting a growing influence on product design and supply chain planning. Recent administrative actions have introduced new reporting requirements for certain sulfonated phenolic resin derivatives, signaling heightened scrutiny around downstream usage patterns and potential exposure pathways. While these measures do not broadly restrict conventional phenolic curing agents, they reinforce a broader trajectory toward greater transparency, lifecycle accountability, and material stewardship. Manufacturers operating across multiple jurisdictions are responding by accelerating compliance documentation, streamlining ingredient disclosure, and investing in alternative chemistries where regulatory risk is elevated. The practical effect is a market where regulatory readiness is increasingly factored into customer selection criteria, particularly for applications in coated surfaces, adhesives, and consumer-adjacent industrial goods.
Demand-Side Transformation Across End-Use Verticals
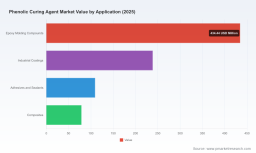
Demand patterns are being reshaped by structural growth in several key application areas. Epoxy molding compounds continue to anchor a large share of consumption, driven by sustained expansion in electronic component manufacturing and the ongoing miniaturization and reliability requirements of advanced packaging. Industrial coatings represent another powerful demand engine, as infrastructure maintenance, automotive refinish, and protective surface treatments increasingly rely on high-crosslink-density formulations that withstand prolonged environmental exposure. Adhesives and sealants, along with composite materials, are experiencing steady uptake linked to lightweighting initiatives, modular construction methods, and the integration of advanced resins in transportation and industrial equipment. Collectively, these demand shifts favor curing agents that offer consistent batch-to-batch performance, compatibility with modern processing equipment, and adaptability to customized cure profiles.
Supply Chain and Cost Structure Pressures
Cost dynamics remain a defining feature of market behavior. Regional feedstock pricing has diverged noticeably, with Northeast Asia and European phenol markets registering substantial year-over-year increases, while other regions exhibit more moderate or even slightly softening trends over shorter intervals. Formaldehyde price movements have also periodically disrupted production economics, underscoring the sensitivity of phenolic resin and curing agent margins to upstream chemical markets. These conditions are encouraging suppliers to pursue long-term sourcing agreements, optimize batch scheduling, and explore regional production footprints that reduce logistics exposure. At the same time, buyers are recalibrating inventory strategies and qualification cycles, seeking partners who can provide pricing visibility and consistent availability amid fluctuating input markets.
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a mix of broad-portfolio resin producers and specialists focused on phenolic curing chemistries. Large multinational firms leverage integrated production networks, diversified application platforms, and established technical service capabilities to serve coatings, adhesives, composites, and electronics markets simultaneously. Their scale and geographic reach provide a buffer against regional demand fluctuations and allow them to cross-sell complementary epoxy and performance product lines. For customers with multi-application needs, these suppliers often function as one-stop partners capable of supporting formulation development, regulatory coordination, and volume reliability.
Alongside these broad-based players, a second tier of companies competes through specialization and application depth. Some manufacturers concentrate on novolac and resole crosslinkers tailored for high-performance coating systems, where cure speed, gloss development, and chemical resistance are paramount. Others focus on phenolic resins positioned explicitly as epoxy curing agents for electronics and composite fabrication, emphasizing purity, thermal stability, and processing consistency. Toll manufacturers and regional producers add further differentiation by offering flexible batch sizes, rapid turnaround, and customized formulation support, which can be decisive for mid-size manufacturers and niche application developers. The result is a landscape where competitive advantage is increasingly tied to technical alignment with specific end-use requirements rather than generic commodity positioning.
Strategic differentiation is unfolding along several clear lines. Leading suppliers are investing in performance-tiered product architectures that allow customers to match cure chemistry to processing constraints and service conditions. Others are strengthening technical service teams and application laboratories to shorten qualification cycles and support customer reformulation efforts. A further strategic vector involves supply chain configuration, with companies adjusting production locations, inventory buffers, and contract structures to mitigate input cost volatility and logistics risk. In a market where a concentrated group of firms holds a meaningful share of global supply, these operational and technical choices are becoming central to 고객 selection and long-term partnership stability.
Market structure appears to be evolving along a dual path. Consolidation pressure persists among larger producers seeking to capture efficiencies, broaden geographic coverage, and integrate complementary resin portfolios. At the same time, fragmentation remains viable for firms that can serve specialized applications, regional demand pockets, or custom manufacturing requirements. New entrants typically face high barriers in the form of formulation expertise, regulatory familiarity, and established qualification relationships, but opportunities continue to arise in tailored curing systems, sustainable formulation support, and regional supply resilience. The overall trend suggests that both scale-oriented and specialization-oriented strategies can succeed, provided they are tightly coupled to the performance and compliance priorities of target end markets.
Worldwide Phenolic Molding Compound Market
Forward Outlook: Trends Shaping 2026–2032
Looking ahead, several interconnected trends are likely to define the market's evolution. The first is the continued differentiation of curing chemistries by application performance rather than by generic chemistry class. As processors demand lower energy consumption, shorter cycle times, and longer service life, suppliers will be judged on their ability to deliver tailored cure profiles and predictable behavior under real-world conditions. This shift favors companies that can combine formulation expertise with application-level testing and technical support.
The second trend is the deepening influence of input cost volatility and regional pricing divergence on procurement and manufacturing strategy. Phenol and formaldehyde markets are expected to remain susceptible to supply disruptions, energy cost shifts, and geopolitical factors that affect chemical feedstock availability. Buyers will increasingly prioritize suppliers that offer transparent pricing mechanisms, flexible contract terms, and credible supply continuity plans. Manufacturers, in turn, will continue to refine regional sourcing, inventory management, and process efficiency to protect margins.
The third trend involves regulatory and sustainability considerations becoming embedded into routine purchasing decisions. Rather than acting as episodic compliance events, environmental and safety requirements are evolving into ongoing criteria that shape product selection, documentation expectations, and qualification processes. This creates opportunities for firms that can provide clear ingredient transparency, assist customers with regulatory navigation, and support the development of lower-impact formulations where feasible.
Phenolic Resins Market
These trends converge on a shared commercial implication: value will accrue to organizations that can anticipate application-specific performance needs, manage input cost exposure, and maintain credible regulatory readiness. The upside is significant for suppliers and buyers who align strategy with these directions, but uncertainty remains around the pace of feedstock price normalization, the scope of future regulatory actions, and the timing of demand acceleration in individual end-use verticals. Scenario planning and continuous market monitoring will be essential to navigate this environment effectively.
Strategic Recommendations for Decision-Makers
For Manufacturers and Formulators
Prioritize application-aligned product development and technical service capabilities. Curing agent selection is increasingly driven by processing efficiency, thermal and chemical performance, and compatibility with modern production lines. Investing in formulation flexibility, application testing, and customer qualification support can differentiate offerings in a market where scale alone is not sufficient tosecure long-term preference.
For Investors and Strategic Planners
Focus on suppliers and end-use segments where performance differentiation and regulatory readiness translate into durable margins. The market's growth trajectory favors companies that can manage feedstock exposure, serve high-value applications such as electronics encapsulation and protective coatings, and maintain agile compliance processes. Diversification across geographies and application verticals can help cushion periodic input cost shocks and demand variability.
PW Consulting
For Procurement and Supply Chain Leaders
Strengthen supplier partnerships around pricing transparency, availability consistency, and qualification speed. Given ongoing feedstock volatility and regional price divergence, multi-source strategies, clear contract terms, and proactive inventory planning can reduce disruption risk. Engaging suppliers early in reformulation or process optimization initiatives can also yield processing savings and improve long-term cost predictability.
For organizations seeking a more granular view of regional demand patterns, type-level segmentation, application-specific growth paths, and detailed competitive benchmarking, the full PW Consulting market research report provides expanded datasets and tailored analysis designed to support planning, sourcing, and investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Phenolic Curing Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com