

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Refined Lanolin Market: Why 5.12% CAGR and Asia Pacific Shifts Redefine Growth

Strategic Trends and Commercial Opportunities in the Worldwide Refined Lanolin Market
Market Overview: A Resilient Specialty Ingredient Amid Structural Pressures
The global refined lanolin market has demonstrated steady growth over the past half-decade, expanding from approximately USD 212.15 million in 2020 to USD 273.35 million in 2025, with a projected trajectory reaching USD 387.72 million by 2032. This translates to a compound annual growth rate of 5.12 percent through the forecast horizon. The expansion reflects a combination of steady demand from established end-use sectors and incremental adoption in higher-margin specialty applications. Rather than experiencing the volatility typical of bulk commodity markets, refined lanolin has maintained a relatively stable upward curve, underpinned by its irreplaceable functional properties in barrier protection, moisture retention, and formulation compatibility.
Despite this positive trajectory, the industry is navigating a set of interconnected challenges that will define competitive positioning over the next several years. First, the market is characterized by moderate concentration, with a handful of established refiners accounting for a substantial share of global output. This structural reality limits pricing flexibility for smaller producers while simultaneously creating supply dependencies for formulators who rely on consistent, pharmacopeia-grade material. Second, raw material sourcing remains inherently tied to sheep farming cycles, wool harvesting volumes, and downstream scouring operations. Fluctuations in primary production, coupled with freight costs and regional processing capacity, introduce periodic cost variability that ripples through finished ingredient pricing. Third, the regulatory and compliance landscape continues to evolve across key import markets. While certain jurisdictions have streamlined animal-by-product classifications for non-feed applications, manufacturers must still navigate divergent pharmacopeial standards, documentation requirements, and certification regimes to access premium pharmaceutical and cosmetic channels. These factors collectively place a premium on operational transparency, purification consistency, and supply chain resilience.
For commercial leaders, the immediate implication is clear: in a market where volume growth is predictable but margin quality depends on application positioning and technical differentiation, success will hinge on how effectively companies can decouple value creation from commodity cycles. The next phase of market development will reward players who treat refined lanolin not merely as a raw input but as a formulation enabler with distinct performance and compliance attributes.
Key Drivers Shaping Market Trajectory
Several converging forces are accelerating the market’s evolution, each reinforcing the others in ways that create both near-term operational imperatives and longer-term structural opportunities.
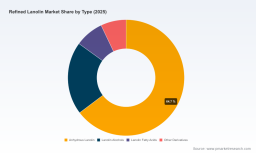
Advanced purification and grade specialization have emerged as critical differentiators. The industry has moved well beyond basic refining toward a more 세분화된 grade architecture that spans anhydrous forms, lanolin alcohols, fatty acids, and targeted derivatives. Manufacturers investing in solvent-free purification, chromatographic separation, and controlled deodorization are capturing premium pricing in pharmaceutical and high-end personal care segments. The commercial logic is straightforward: tighter control over residual impurities, oxidative stability, and sensory profile allows ingredient suppliers to align more closely with formulators’ stability, safety, and consumer-preference requirements, thereby reducing down-stream reformulation costs and increasing switching costs.
Policy and regulatory dynamics are reshaping cross-border trade and compliance expectations. In certain markets, classifications of wool grease and derived fatty substances have shifted toward lower-risk categories for non-animal-feed applications, reducing routine inspection burdens and smoothing import pathways. At the same time, pharmacopeial alignment remains a gatekeeper for pharmaceutical and medical-grade positioning. Companies that proactively map ingredient specifications to regional standards and maintain auditable documentation are better positioned to serve regulated channels without disproportionate compliance friction. Conversely, fragmented regulatory interpretations across markets can create hidden costs for exporters who lack region-specific grade portfolios or certification coverage.
Demand-side evolution is expanding the addressable market beyond traditional volumes. Consumer preferences increasingly favor ingredients perceived as naturally derived, skin-compatible, and sustainably sourced. This has reinforced the role of refined lanolin in cosmetics, personal care, and baby care products, where its occlusive and emollient properties align well with clean and barrier-support narratives. Simultaneously, sustained reliance on lanolin in pharmaceutical ointments and dermatological formulations provides a stable demand floor. Formulators in these segments value predictable performance, irritation profiles, and compatibility with active ingredients, which sustains demand even when alternative emollients enter the market. The net effect is a bifurcated demand environment: a high-growth, value-sensitive consumer segment and a regulated, specification-driven pharmaceutical segment, each rewarding different supplier capabilities.
Supply chain and cost structure shifts are also redefining competitive dynamics. Global trade in wool grease derivatives has reached meaningful scale, and primary material pricing has reflected broader agricultural and logistics conditions in recent years. For refiners, the margin equation increasingly depends on yield optimization, byproduct valorization, and geographic positioning relative to both wool sourcing and end-use demand centers. Capacity expansions and facility upgrades in high-growth regions are responding to localized demand and logistics considerations, while multi-site production strategies help mitigate concentration risk and improve lead-time reliability. Suppliers that integrate purification technology with flexible logistics and application support are better equipped to absorb input variability without eroding customer trust.
Competitive Landscape and Strategic Positioning
The competitive field reflects a mix of established multinational refiners, specialized regional producers, and formulation-focused suppliers. Rather than competing solely on volume, leading players are pursuing distinct strategic lanes that align with application requirements and regional demand patterns.
Several manufacturers have positioned themselves around high-purity pharmaceutical-grade material supported by advanced refining technologies. These players emphasize solvent-free processes, low pesticide residuals, and adherence to international pharmacopeia standards, allowing them to serve regulated ointment and dermatological applications with fewer specification compromises. Others have focused on derivative breadth, offering lanolin alcohols, fatty acids, and customized intermediates that enable formulators to fine-tune viscosity, spreadability, and compatibility without shifting base ingredients. A third group emphasizes supply reliability and global distribution infrastructure, leveraging warehouse networks, multi-site production, and application technical support to reduce formulation risk for cosmetics and industrial users.
Recent corporate actions illustrate how these positioning choices are being operationalized. One established multinational expanded its premium offerings with an ultra-refined lanolin oil designed for skincare and medical-grade formulations, targeting enhanced purity, reduced odor, and improved oxidative stability. Around the same period, the same company opened a new manufacturing facility in India to support regional demand growth and sustainable innovation pathways. Meanwhile, a China-based specialist relocated and upgraded its plant to incorporate patented technology aimed at ultra-pure pharmaceutical grades, while another long-standing manufacturer advanced capacity planning following earlier expansion phases. Collectively, these moves signal a market in which technology investment, geographic balancing, and grade differentiation are being treated as interlocking levers rather than isolated initiatives.
PW Consulting
The landscape is gradually evolving along both consolidation and fragmentation axes. On one side, larger integrated refiners are strengthening their ability to serve cross-regional demand with standardized grades and application support, which favors buyers seeking supply consistency across multiple markets. On the other, smaller or regionally focused producers continue to enter or expand in niche grades, certification-driven segments, or specific application verticals where technical service and responsiveness outweigh pure scale. For buyers and investors alike, this duality means that supplier evaluation increasingly turns on three questions: how reliably can the supplier meet pharmacopeial or cosmetic specifications at scale, how responsive is the supplier’s technical and logistics capability to formulation changes, and how exposed is the supplier to single-region sourcing or single-application concentration.
Refined Linseed Oil Market
Forward Outlook: Three Trends to Monitor
Looking ahead to the 2026–2032 horizon, several trends are likely to shape both opportunity and risk.
First, grade specialization will deepen as a margin strategy . As formulators push for cleaner sensory profiles, tighter impurity limits, and more predictable oxidative behavior, suppliers that can consistently deliver differentiated grades will capture disproportionate value. The commercial opportunity lies in pairing high-purity base material with application-specific technical guidance, especially in premium skincare, medical ointments, and baby care, where specification trust directly influences formulary decisions. The risk is execution: maintaining grade consistency across batches while managing raw material variability requires disciplined process control and analytical capability.
Second, regional capacity rebalancing will continue as demand growth and logistics economics shift relative attractiveness across geographies. Investments in processing capacity closer to high-growth demand centers, combined with multi-site manufacturing strategies, are likely to improve lead-time reliability and reduce exposure to single-node disruptions. This trend creates opportunities for buyers to diversify supply bases and for producers to strengthen regional customer relationships through faster technical response and localized support. The uncertainty lies in coordination: capacity additions must be matched by appropriate demand segmentation and certification coverage, or the result may be fragmented supply with limited premium capture.
Worldwide Refined Kerosene Market
Third, regulatory and compliance architecture will increasingly function as a market-access filter . Where import classifications ease for certain animal-derived fatty substances, frictionless trade can expand commercial reach. Where pharmacopeial and certification expectations remain stringent, documented specification control and audit readiness will separate suppliers that can enter regulated channels from those that cannot. The commercial implication is that compliance is no longer a back-office function; it is a frontline competitive attribute. Potential downside arises if regulatory interpretations diverge further across markets, forcing suppliers to maintain multiple parallel documentation and testing regimes that compress operating efficiency.
Actionable Guidance for Decision-Makers
Different stakeholders will need to translate these trends into concrete moves, but a few principles apply across the board.
For manufacturers and ingredient suppliers, the priority is to align technology investment with the grade profiles that command the strongest specification trust in target applications. Upgrading purification consistency, expanding derivative breadth, and building regional application support can convert technical capability into repeat commercial relationships. Equally important is designing supply flexibility so that raw material variability does not translate into specification risk for regulated customers.
For investors and corporate development teams, the strategic question is less about whether the market will grow and more about where value will concentrate. Opportunities are most compelling where companies can demonstrate defensible differentiation: high-purity grades tied to pharmacopeial compliance, application-specific technical service, and geographic diversification that reduces single-market exposure. Due diligence should focus on process control maturity, certification coverage, customer concentration, and the credibility of capacity plans relative to actual demand segmentation.
For procurement and formulation leaders, supply resilience and specification reliability should be weighted alongside unit economics. Diversifying across suppliers with complementary strengths, validating grade consistency through in-house or third-party testing, and securing clear documentation for regulated applications can reduce reformulation risk and downstream disruption. Shortlisting suppliers on technical responsiveness and regional logistics capability, not just headline pricing, tends to pay off when formulation requirements shift or supply conditions tighten.
The global refined lanolin market is entering a phase where growth is no longer enough on its own; value capture will favor those who can pair purification precision, compliance readiness, and application insight with supply discipline. Stakeholders seeking to navigate this environment with greater confidence will find that detailed segmentation data, regional grade mapping, and supplier capability assessments provide the granularity needed to move from broad trends to precise decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Refined Lanolin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com