

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide NTP & PTP Time Servers Market: Why the 8.12% CAGR Trajectory Changes Enterprise Timing Strategy

Navigating the Worldwide NTP & PTP Time Servers Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview: Scale, Growth Trajectory, and Critical Crossroads
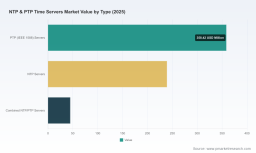
The global market for Network Time Protocol (NTP) and Precision Time Protocol (PTP) time servers has entered a phase of sustained, structurally supported expansion. Valued at approximately $642.5 million in 2025, the market is projected to reach $1,109.7 million by 2032, reflecting a compound annual growth rate of 8.12 percent. This trajectory is not merely a function of incremental IT refresh cycles; it reflects a fundamental shift in how modern digital infrastructure defines, distributes, and relies upon highly synchronized time signals. Over the past five years, the market has matured from a niche hardware category into an essential timing infrastructure layer that underpins telecommunications, financial trading ecosystems, power grid management, and hyperscale data center operations.
Several structural challenges are simultaneously testing the industry and creating inflection points for competitive differentiation. First, the transition toward sub-microsecond and nanosecond synchronization requirements is forcing a reevaluation of legacy NTP-centric architectures. While NTP remains dominant for general enterprise synchronization, the growing demand for deterministic latency, transactional integrity, and real-time workload orchestration is accelerating adoption of PTP (IEEE 1588) and hybrid time distribution models. This shift introduces complexity in deployment, calibration, and ongoing maintenance, particularly for organizations managing distributed footprints across multiple geographical regions.
Second, supply chain resilience and component sourcing have emerged as persistent risk factors. Time servers rely heavily on precision oscillators, GNSS receiver modules, and specialized networking hardware. Geopolitical volatility, semiconductor allocation constraints, and evolving GNSS signal integrity concerns have pressured manufacturers to balance performance specifications against lead times, cost control, and long-term availability. Companies that fail to secure stable component pipelines or design graceful degradation pathways risk downstream customer churn when timing reliability is compromised during signal outages.
Third, regulatory and compliance expectations are tightening the link between timing accuracy and operational accountability. Financial market regulators and critical infrastructure oversight bodies increasingly treat synchronized time as a control objective rather than a convenience feature. This regulatory realism is elevating the cost of non-compliance and pushing procurement teams to prioritize resilience, auditability, and verifiable accuracy over lowest upfront price. The market is therefore moving past a commodity mindset and toward a solutions-oriented posture where time servers are evaluated alongside cybersecurity posture, holdover performance, and integration with broader network orchestration frameworks.
Core Drivers Shaping Market Evolution
Four interconnected forces are driving demand, shaping product roadmaps, and redefining commercial opportunity across the timing infrastructure landscape.
Technological Innovation and the Push for Higher Precision
The most visible driver is the accelerating performance gap between conventional NTP deployments and mission-critical PTP requirements. As applications such as 5G radio synchronization, high-frequency trading, and real-time analytics place tighter constraints on latency variance and clock offset, vendors are investing in hardware timestamping, improved GNSS acquisition algorithms, and more stable oscillator technologies. Recent product introductions illustrate this trajectory. Meinberg expanded its PTP grandmaster portfolio with a new series designed to enhance hardware timestamping and improve power efficiency, specifically targeting high-frequency trading environments and 5G infrastructure. Shortly thereafter, the company introduced the microSync XS, a compact GNSS-synchronized time server featuring dual PTP-capable network ports. These releases reflect a broader industry movement toward smaller physical footprints, greater port density, and more deterministic timing performance without sacrificing deployment flexibility.
At the infrastructure level, the integration of GNSS receivers with holdover mechanisms such as OCXO, rubidium, or cesium oscillators has become a practical necessity rather than an optional premium. When external references are disrupted, holdover performance determines whether a facility maintains compliance or experiences cascading synchronization failures. Vendors that can demonstrate measurable holdover stability under real-world conditions are gaining trust in sectors where timing discontinuities create direct operational or regulatory exposure.
Regulatory Pressure and the Compliance-Driven Timing Premium
Policy and regulatory environments are reinforcing demand for higher-grade time synchronization, particularly in finance and critical infrastructure. Financial regulators in multiple jurisdictions have established timestamp accuracy expectations in the microsecond range for trade reporting and audit trail integrity. Meeting those requirements frequently depends on PTP or enhanced NTP architectures that can deliver consistent, auditable synchronization across trading systems, risk platforms, and surveillance infrastructure. The regulatory dimension is important because it changes purchasing logic: timing equipment is no longer selected solely on price or basic feature checklists, but on demonstrable reliability, traceability, and alignment with compliance frameworks.
In parallel, data center operators are increasingly migrating from NTP to PTP to support workloads that demand tighter synchronization windows. This migration is not just about speed; it is about enabling deterministic behavior across distributed application stacks, virtualization layers, and interconnect fabrics. As timing becomes more deeply embedded in service-level commitments, the cost of synchronization errors rises, and the incentive to invest in robust timing architectures strengthens.
Demand-Side Shifts Across Verticals
Demand is broadening beyond traditional telecom and finance use cases, though those segments remain central. Telecommunications and 5G network deployments continue to represent a major consumption center because radio access network synchronization, backhaul alignment, and fronthaul timing requirements place continuous pressure on precise timing distribution. Financial services and high-frequency trading remain highly sensitive to timestamp accuracy, and their procurement patterns often favor solutions that combine precision with security hardening and fault tolerance.
PW Consulting
Power and energy grids are also emerging as a meaningful demand source. As grid modernization efforts expand, synchronization is needed for substation automation, phasor measurement units, and distributed energy resource coordination. Data centers and IT infrastructure contribute steady demand, particularly where virtualization density, storage coherence, and multi-site replication require consistent time alignment. Transportation and industrial automation add further diversity to the demand base, with synchronization needs spanning signaling systems, operational technology convergence, and facility-wide clock distribution. The key strategic implication is that no single vertical dictates the entire market cycle; diversified demand dampens sector-specific volatility and creates cross-vertical product leverage for vendors with adaptable platforms.
Supply Chain Realities and Cost Structure Evolution
Cost dynamics are being reshaped by both component economics and architectural expectations. Manufacturers are managing trade-offs among GNSS module availability, oscillator precision, network interface complexity, and software-driven management capabilities. There is also a growing emphasis on security-hardened designs, with time servers increasingly expected to fit within zero-trust architectures and resist manipulation of timing signals or management interfaces. Microchip's enterprise SyncServer portfolio, for example, has emphasized advanced security features for mid-to-large scale networks, reflecting the reality that timing infrastructure must now be evaluated alongside broader cybersecurity strategy.
This shift affects pricing architecture. Solutions that deliver strong holdover, secure management, and integration-friendly APIs can command stronger margins than basic reference appliances. Conversely, vendors that compete primarily on specification sheets without addressing resilience, security, or lifecycle support may find pricing pressure intensifying as buyers become more sophisticated.
Competitive Landscape and Leading Strategies
The competitive environment is moderately concentrated but broad enough to support specialized positioning. Industry concentration indicates that a limited group of established players captures a meaningful share of revenue, while a long tail of regional and application-focused suppliers competes on differentiation, responsiveness, and vertical expertise. This structure creates both stability and opportunity: the leading companies benefit from scale, brand trust, and broad product portfolios, while smaller or regionally anchored firms compete by serving niche requirements more precisely.
Atomic Clock Market
Several strategic postures stand out. Meinberg has reinforced its positioning around scalable NTP and PTP deployments with hardware timestamping and compact form factors designed for industrial, broadcast, power, and data center environments. Its recent grandmaster and microSync releases demonstrate a focus on performance efficiency and deployment flexibility in high-demand settings. Microchip has leaned into enterprise-grade resilience and security, offering NTP/PTP time servers aligned with zero-trust principles for mid-to-large networks. This security-forward approach is particularly relevant for organizations that view timing infrastructure as a control-plane asset rather than a passive peripheral.
Safran, through its navigation and timing business, continues to emphasize high-performance GPS time servers with NTP/PTP support and sub-nanosecond accuracy, targeting critical applications where resilience and precision carry direct operational weight. Brandywine Communications maintains a strong orientation toward transportation, space, and defense use cases, offering NTP and PTP server options with GPS-referenced synchronization. EndRun Technologies and TimeMachines serve overlapping but distinct segments, with emphasis on secure in-firewall time distribution and government, military, and public safety applications respectively.
In Europe, several manufacturers have carved out positions around integrated timing, displays, and facility-wide synchronization. Bodet Time and Galleon Systems illustrate the breadth of this approach, providing NTP and PTP-capable servers for enterprise, industrial, and institutional environments. Oscilloquartz, ADVA's timing unit, and Masterclock are focused on high-precision synchronization for mobile and fixed network operators, finance, IoT, and broadcast-adjacent applications. The presence of regional specialists such as Valiant Communications in India, Heol Design in France, PTF in the United States, hopf Elektronik in Germany, and Arbiter Systems reflects the market's need for localized support, application-specific profiling, and tailored integration services.
The competitive landscape is evolving along three axes. First, differentiation is increasingly tied to precision, resilience, and security rather than protocol support alone. Second, convergence is occurring where timing hardware is bundled with software management, monitoring, and service delivery models. Equinix's precision time offering is a notable example of how data center platforms can package secure PTP and NTP synchronization as a service, extending timing availability to distributed enterprise workloads without requiring every site to operate its own standalone infrastructure. Third, the market remains open to new entrants that can address underserved verticals or deliver innovative integration models, especially where legacy suppliers are too slow to adapt to PTP migration, security expectations, or compact industrial designs.
Forward-Looking Trends and Strategic Implications
Looking toward the next three to five years, several trends are likely to define how the market expands and where value concentrates.
First, PTP adoption will continue to deepen in environments that require deterministic timing, while NTP will retain strength in broader enterprise synchronization. The practical outcome is a dual-stack reality: organizations will manage both protocols, often with overlapping infrastructure, and vendors that can simplify that complexity through unified management, hybrid server designs, and clear migration guidance will gain advantage. Combined NTP/PTP offerings are well positioned to capture customers who want precision where it matters without discarding existing NTP investments.
Second, timing resilience will become a more explicit purchasing criterion. GNSS dependency, signal interference risk, and holdover performance are driving demand for architectures that can sustain accurate time distribution during external reference disruptions. Solutions that combine robust GNSS locking with high-quality oscillator holdover and secure fallback behavior will be increasingly favored in telecom, finance, energy, and defense applications.
Third, time synchronization is likely to be consumed more frequently as an embedded service or managed capability rather than solely as discrete hardware. Data center platforms, cloud-adjacent infrastructure, and service providers have an opportunity to bundle timing into broader service portfolios, reducing deployment friction for distributed enterprises. This shift creates commercial opportunities for providers that can offer secure, auditable, and scalable synchronization with clear service commitments.
These trends carry inherent risks. Overconcentration on a small number of GNSS constellations or component suppliers could expose supply chains to disruption. Regulatory expectations may continue to tighten, increasing compliance costs for late adopters. In addition, aggressive price competition in lower-end segments may compress margins for vendors that cannot articulate a strong resilience, security, or integration story. Buyers and manufacturers alike will need to balance performance ambitions with realistic total cost of ownership and long-term supportability.
Real Time Clock Market
Actionable Guidance for Decision-Makers
Manufacturers should prioritize architectures that address the precision-resilience-security triad. Product roadmaps that improve hardware timestamping, strengthen holdover performance, and embed security controls for zero-trust environments will align more closely with where enterprise and critical infrastructure buyers are heading. Equally important is the ability to support hybrid NTP/PTP deployments in a way that reduces integration burden for customers transitioning between synchronization standards.
Investors should evaluate exposure to verticals where timing accuracy is tied to regulatory compliance and operational reliability, particularly telecommunications, financial services, and grid modernization. The strongest commercial opportunities will likely accrue to companies that can demonstrate differentiated precision, stable supply chains, and clear alignment with emerging PTP-driven workloads. Attention should also be paid to service-oriented models and data center ecosystem partnerships, which can expand addressable demand beyond traditional hardware sales.
Procurement and infrastructure leaders should treat time synchronization as a strategic control function rather than a commodity purchase. Selection criteria should extend beyond price to include holdover behavior, security posture, management integration, and the vendor's ability to support future PTP migration. Organizations operating across multiple sites or relying on distributed transaction integrity will benefit from early alignment with architectures that can scale precision where needed while maintaining operational consistency across the network.
For decision-makers seeking detailed segmentation, regional demand patterns, competitive benchmarking, and tailored scenario analysis, the complete PW Consulting market study provides the deeper evidence base needed to translate these strategic signals into investment, procurement, and product decisions.
For detailed analysis of this topic, please visit the official page: Worldwide NTP & PTP Time Servers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com