

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Why Rotary Separator Market's 4.71% CAGR Reshapes Global Growth by 2032

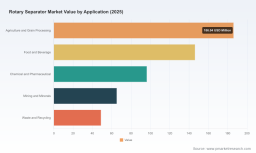
Worldwide Rotary Separator Market: Strategic Trends and Commercial Opportunities
Market Overview: Current Landscape and Core Challenges
The global rotary separator market has demonstrated steady expansion over the past five years, transitioning from a $425.1 million valuation in 2020 to $542.4 million in 2025. Looking ahead, the trajectory points toward sustained growth, with valuations projected to reach $748.57 million by 2032, implying a compound annual growth rate of 4.71 percent between 2026 and 2032. This expansion reflects broader industrial shifts toward automated material handling, enhanced product purity requirements, and the ongoing modernization of legacy processing infrastructure.
Despite the positive growth narrative, the industry faces several structural challenges that will define competitive positioning in the coming years. First, the market exhibits moderate concentration, with the top three players collectively holding approximately 28.4 percent of global revenue and the top five reaching 39.5 percent. This fragmented concentration suggests that no single manufacturer dominates the value chain, creating both opportunities for consolidation and risks for mid-tier suppliers struggling to differentiate. Second, capital expenditure cycles in end-use industries remain sensitive to macroeconomic conditions. Processing facilities in agriculture, food manufacturing, and recycling sectors often delay equipment upgrades when operating margins compress, creating lumpy demand patterns that complicate production planning and inventory management for rotary separator manufacturers.
A third critical challenge lies in the tension between standardization and specialization. Rotary separators are deployed across diverse applications, from grain processing and pharmaceutical powder screening to manure solids separation and waste removal in packaging lines. Each application carries distinct performance requirements, material compatibility constraints, and regulatory expectations. Generic equipment offerings may win on upfront price, but they frequently underperform in terms of throughput efficiency, clean-in-place capability, and durability under abrasive or corrosive conditions. Manufacturers that fail to balance modular design with application-specific engineering risk margin erosion as customers migrate toward suppliers offering tighter integration with automation systems and downstream processing equipment.
Finally, raw material dynamics introduce cost volatility that challenges pricing stability. Stainless steel serves as the primary construction material for rotary drum and separator bodies, and its supply-demand balance directly affects bill-of-materials costs. While global stainless steel production reached 64.2 million metric tons in 2025, reflecting a 2.1 percent increase from 2024, pricing discipline depends on alloy composition, regional availability, and downstream fabrication capacity. These factors collectively shape a competitive environment where operational efficiency, material sourcing strategy, and engineering precision are becoming equally important as brand reputation.
Key Drivers of Market Transformation
Technology Innovation and Engineering Breakthroughs
Advancements in rotor geometry, screening media, and drive-system efficiency are reshaping what rotary separators can achieve in terms of throughput and product purity. Recent product updates in agricultural combine manufacturers illustrate this shift clearly. In October 2025, major combine manufacturers introduced CR10 and CR11 Twin Rotor combines with enhanced rotary separator technology entering production. These units feature larger rotors designed to increase processing capacity while improving grain quality protection during harvest. This development signals a broader trend: rotary separation is no longer treated as a passive screening step but as an engineered stage that directly influences yield, contamination levels, and downstream processing economics.
Beyond equipment design, integration with automation and process control systems is accelerating. High-capacity processing in plastic, paper, packaging, and agricultural sectors increasingly relies on separators that communicate with upstream conveyors, downstream sorters, and inline quality sensors. When rotary separators are configured to support automated waste removal and solids-liquid separation with minimal manual intervention, end users gain measurable reductions in labor intensity and operational variability. For manufacturers, this creates an opportunity to transition from standalone equipment suppliers to performance-based solution providers, where differentiation comes from system integration rather than mechanical design alone.
Regulatory and Hygiene Standards as Adoption Accelerators
Food safety and hygiene expectations continue to raise the baseline for equipment specifications in powder, slurry, and ingredient processing. Regulatory frameworks such as FDA and EFSA guidelines emphasize sanitary design, cleanability, and contamination control. These requirements directly drive adoption of sanitary rotary sifters and separators that are engineered for powder and slurry processing in food and pharmaceutical applications. Equipment that supports rapid disassembly, clean-in-place protocols, and smooth surface finishes without dead zones is becoming a procurement requirement rather than an optional upgrade.
This regulatory pull extends beyond compliance checklists. Operators in food and pharmaceutical sectors are increasingly linking equipment specifications to audit readiness, traceability, and brand protection. A separator that meets hygiene standards but introduces processing bottlenecks or cleaning delays can create hidden costs that outweigh its capital price advantage. Consequently, procurement decisions are shifting toward total cost of ownership assessments that factor in sanitation cycles, downtime, and material contact safety. Manufacturers that design for hygiene from the outset, rather than retrofitting it, are capturing premium positioning in these regulated segments.
Centrifugal Separator Market
Demand-Side Shifts and Applicational Diversification
Demand patterns are being reshaped by both volume growth and operational complexity. In agriculture and grain processing, the scale of operations continues to expand as producers seek to manage larger harvests with fewer labor inputs. Rotary drum separators and related equipment are being specified not only for primary processing but also for byproduct recovery, fines removal, and material classification before storage or further milling. This broadening scope increases the relevance of rotary separation across the value chain rather than confining it to a single processing node.
Simultaneously, waste and recycling applications are gaining prominence. Automation and high-capacity processing in plastic, paper, packaging, and agriculture sectors increase demand for efficient rotary separators to handle waste removal and solids-liquid separation. As material recovery targets become stricter and feedstock variability rises, separators must tolerate mixtures that change frequently in composition and moisture level. This dynamic favors designs with robust construction, replaceable screening components, and adjustable operating parameters that can be tuned during campaigns rather than requiring lengthy changeovers.
Supply Chain and Cost Structure Realities
Cost structures are being influenced by material pricing, alloy requirements, and fabrication lead times. Stainless steel production expanded in 2025, yet cost stability depends on alloy availability and regional supply logistics. Nickel prices are projected to remain in the $15,000 to $20,000 per metric ton range, influenced by constraints such as Indonesian mining restrictions and electric vehicle demand. For rotary separators, nickel is critical in stainless steel alloys used in food-grade and corrosion-resistant construction. This means that even when overall steel volumes increase, alloy-sensitive segments may still experience pricing pressure if specific grades become constrained.
PW Consulting
Material specification also affects application economics. For manure and agricultural applications, 304 stainless steel construction is standard for rotary drum separators to ensure durability and clean-in-place efficiency. The choice of alloy is therefore not simply a durability decision; it is a total-cost decision that influences maintenance frequency, replacement cycles, and compliance with sanitation expectations. Manufacturers that manage alloy procurement carefully and align grade selection with actual application requirements can protect margins without unnecessarily inflating equipment cost. At the same time, end users evaluating procurement options increasingly recognize that lower initial capital may be offset by higher lifecycle costs if material selection compromises longevity or cleanability.
Competitive Landscape and Leading Strategies
The market is populated by a diverse group of manufacturers spanning food and grain processing, industrial screening, pharmaceutical sanitary equipment, agricultural separation, waste handling, and magnetic separation. This breadth reflects the versatility of rotary separation technology, but it also fragments competitive focus. Leading players differentiate not by being broadly present across every application, but by building credible depth in segments where performance requirements are most demanding.
In the food and grain sector, companies such as Profile Industries, Rotex Group, Kason Corporation, and Ocrim S.p.A. emphasize application coverage that spans sorting, sifting, cleaning, and material handling. Profile Industries manufactures rotary sorters for food, seed, grain, hemp, and industrial applications worldwide, positioning itself where product purity and gentle handling matter. Rotex Group offers gyratory and reciprocating industrial separators, screeners, sifters, and cleaners for high-capacity applications including grain and minerals, appealing to operations that prioritize throughput and robust screening performance. Kason Corporation supplies centrifugal sifters and separators for bulk solids, slurries, food, chemical, pharmaceutical, and industrial applications, leveraging a broad application portfolio that bridges wet and dry separation needs. Ocrim S.p.A. manufactures rotary separators for grain processing, flour milling, and material handling in turnkey plants, illustrating a strategy that ties separation equipment into integrated processing solutions rather than standalone machine sales. These approaches show that leadership in grain and food sectors often comes from combining application expertise with system-level thinking.
In sanitary and controlled-processing environments, regulatory expectations create a narrower but higher-value competitive arena. Coperion, through its Kemutec KEK line, offers pressure-design rotary sifters for hygienic screening of powders and granules in food and pharmaceutical applications. Russell Finex produces rotary sifters such as the Turbo Sifter using centrifugal force for screening powders and slurries in food and industrial sectors. Both manufacturers illustrate a differentiation path built on screening precision, cleanability, and compatibility with sensitive materials. In these environments, the value proposition is less about raw capacity and more about consistency, contamination control, and process reliability. Companies that invest in sanitary engineering, validation support, and service-ready designs can command stronger positioning even if their installed base is smaller than broad-line competitors.
Agricultural and waste-handling applications introduce a different competitive logic. McLanahan Corporation manufactures rotary drum separators for manure solids-liquid separation in agricultural and processing applications, with stainless steel construction. Doda USA provides rotary separators for sludge thickening and solids-liquid separation in organic waste and agricultural applications. These players compete on durability, material compatibility, and practical serviceability in demanding field conditions. Meanwhile, in waste removal for plastic, paper, and packaging industries, Kongskilde Industries produces RVS/KS rotating separators for waste removal, including high-pressure multi-purpose models. This segment rewards flexibility, ease of integration into continuous lines, and the ability to manage variable contaminant loads without excessive downtime.
Magnetic separation and specialized screening add further dimensions to the competitive mix. Great Magtech and Huate Magnet Group manufacture rotary magnetic separators for industrial magnetic separation needs, addressing applications where ferrous contamination control is central. SWECO provides round and rectangular vibratory separators, gyratory sifters, and related separation equipment with global manufacturing and support, offering an alternative motion-based approach that competes in certain screening scenarios even though it is not strictly a rotary separator in the same mechanical sense. Provisur Technologies, through Beehive and AM2C, offers rotary separators for meat, poultry, and food separation and recovery using rotary, belt, and press technologies, demonstrating how rotary separation can be combined with other mechanical systems to recover value in protein and byproduct streams. ERIMAKI Snc produces rotary separators for industrial screening applications, rounding out the field with additional European manufacturing capacity.
The strategic implication is that the market is evolving through both specialization and selective consolidation. Companies that compete across too many unrelated applications risk diluting engineering focus and service capabilities. Companies that concentrate on one or two high-value application clusters, while building complementary services such as integration, preventive maintenance, and rapid parts availability, are better positioned to protect margins. At the same time, the moderate concentration ratios suggest room for both organic growth and targeted acquisitions, particularly where regional coverage, application coverage, or aftermarket service networks are incomplete. New entrants are most likely to succeed by addressing underserved niches, such as modular sanitary screening, compact high-capacity separators for space-constrained facilities, or upgraded retrofit kits that improve the performance of legacy installed equipment.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
One clear trend is the continued elevation of rotary separators from commodity processing components to engineered system elements. As end users pursue higher throughput, better material recovery, and lower variability, separator selection will increasingly be evaluated alongside automation, sensor integration, and downstream process compatibility. Manufacturers that can demonstrate measurable improvements in yield, contamination control, and cleaning efficiency will find stronger pricing power than those competing primarily on unit price. This trend favors suppliers that invest in application engineering and can translate equipment specifications into operational outcomes.
Rotary Cutters Market
A second trend is the steady expansion of demand in regulated and sustainability-sensitive applications. Food and pharmaceutical hygiene requirements will keep driving adoption of sanitary sifting and separation solutions, while waste handling and recycling pressures will increase the need for separators that manage variable feedstocks and support material recovery. These segments are less cyclical than commodity-driven capex cycles because they are tied to compliance, product quality, and resource recovery objectives. As a result, they are likely to provide a more stable growth base, provided manufacturers can meet the associated engineering and service expectations.
A third trend involves cost and supply-chain discipline becoming a competitive differentiator. Material availability, alloy pricing, and fabrication lead times will remain factors that influence both manufacturer margins and procurement decisions. In this environment, value will accrue to firms that can align grade selection with actual service conditions, manage supplier relationships for critical alloys, and offer lifecycle-based pricing models. For buyers, the practical implication is that lowest upfront cost may not deliver the best outcome if cleaning cycles, replacement frequency, or downtime are adversely affected by material or design compromises.
Potential risks temper this outlook. Demand can soften during periods of capital spending restraint, especially in agriculture and industrial processing where equipment upgrades are sensitive to margin conditions. Overcapacity in generic screening segments could intensify price competition and compress returns for undifferentiated suppliers. Regulatory expectations may also change in ways that alter material specifications or sanitation requirements, forcing redesigns or retrofit investments. Finally, regional differences in procurement culture, service expectations, and compliance enforcement mean that global strategies must be adapted locally rather than applied uniformly.
Strategic Guidance for Decision Makers
For manufacturers, the priority should be to sharpen application focus and make engineering differentiation visible to buyers. That means developing credible reference points for throughput, cleanability, wear life, and integration with automation, rather than competing through broad catalog breadth alone. Aligning alloy choices and component design with the actual operating conditions of target applications can improve margin stability while reducing the risk of underperformance in the field. Aftermarket service, parts availability, and retrofit capability should be treated as part of the core product strategy, since recurring revenue and customer retention often depend more on support than on the initial sale.
For investors, the opportunity lies in identifying suppliers with defensible positions in regulated, high-hygiene, or high-complexity applications, where switching costs are higher and value is tied to performance rather than price. In agricultural, food, pharmaceutical, and waste-recovery segments, business models that combine equipment sales with service, upgrades, and integration capability tend to offer more resilience across capex cycles. When evaluating exposure to raw material pricing, it is useful to assess whether a company manages alloy specification intelligently and whether its cost structure can absorb nickel and stainless steel volatility without forcing destabilizing price actions.
For procurement leaders and facility operators, the most practical step is to evaluate rotary separators through total cost of ownership rather than purchase price alone. Equipment that meets hygiene, durability, and cleaning requirements can reduce hidden operational costs even if the initial investment is higher. Defining application requirements clearly, including material characteristics, cleaning frequency, throughput variability, and integration needs, will improve specification accuracy and reduce the likelihood of selecting equipment that performs adequately in testing but struggles in daily operation. Where installation constraints or legacy systems limit new equipment options, evaluating retrofit or upgrade paths can extend asset value without full replacement.
As market dynamics continue to evolve, the credibility of strategic decisions will depend on timely access to detailed segment data, regional breakdowns, and supplier-level intelligence. deeper coverage of application-level sizing, regional demand patterns, and competitive positioning is available through the full research report, enabling more precise planning for procurement, capacity investment, and market entry decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Rotary Separator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com