

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Data Storage Market 2026: Beyond the 12.5% CAGR—Where Value Flows

Worldwide Next-Generation Data Storage Market: Strategic Trends and Commercial Opportunities
Market Landscape and Defining Challenges
The global next-generation data storage market is undergoing a structural acceleration, with revenue projected to climb from approximately USD 45.1 billion in 2020 to USD 86.7 billion by 2025. The growth trajectory steepens beyond the baseline year, with the sector positioned to surpass USD 102.5 billion in 2026 and approach USD 197.7 billion by 2032, supported by a compound annual growth rate of 12.5 percent across the forecast horizon. This expansion is not a simple byproduct of data volume growth; it reflects a deliberate architectural shift as organizations replace aging, rigid storage estates with systems engineered for AI workloads, hybrid cloud deployment, and high-throughput data processing.
Three challenges define the current inflection point. First, organizations are navigating a multi-speed transformation where legacy infrastructure, mid-tier modernization, and frontier storage research coexist within the same procurement cycle. Enterprises must balance immediate performance demands against long-term positioning, creating procurement complexity and fragmented ROI horizons. Second, energy and physical infrastructure constraints are reshaping deployment economics. Grid connection delays in primary data center markets are stretching timelines for new capacity, compelling operators to evaluate behind-the-meter power generation and co-located battery storage. This bottleneck forces storage decisions to be evaluated alongside energy sourcing, thermal management, and site readiness rather than as isolated hardware purchases. Third, efficiency and sustainability expectations are becoming measurable governance requirements. International benchmarking frameworks for data center resource efficiency, along with emerging technical standards for measuring the environmental impact of AI workloads, are raising the bar for how storage infrastructure is selected, operated, and reported. High-reliability deployments are also facing tighter control clarity and evidence expectations for information security management, which increases the compliance burden for next-generation platforms handling sensitive or regulated data.
Together, these dynamics reframe the market from a capacity-and-throughput contest into a broader infrastructure proposition. Performance still matters, but it must be evaluated alongside energy intensity, deployment speed, regulatory alignment, and the ability to integrate with heterogeneous compute environments.
Key Drivers Shaping the Market
Technological Innovation and New Storage Paradigms
The most visible driver is a widening innovation frontier that extends well beyond conventional flash and disk scaling. Established silicon-based memory and storage technologies continue to advance, but a parallel wave of emerging approaches is gaining traction for specialized workloads. Persistent memory technologies are moving from proof-of-concept into validated enterprise configurations, with recent validation activity connecting magnetoresistive random-access memory to broad FPGA ecosystems for high-reliability applications. At the opposite end of the durability spectrum, synthetic DNA-based storage has crossed a commercialization threshold, with a production-scale archival service launching after spin-out and seed funding, signaling that extremely dense long-term retention is moving from laboratory curiosity to early market availability. These parallel tracks indicate that the market is not converging on a single successor technology; instead, it is segmenting by workload durability, access latency, and total cost of retention.
Policy, Standardization, and Compliance Pressure
Regulatory and standardization activity is reshaping procurement logic. Internationally recognized efficiency metrics for data center operations are increasingly used as benchmarks for infrastructure supporting advanced storage systems, making energy and water usage considerations part of vendor evaluation. At the same time, technical working groups are developing standards for measuring AI environmental impact at the model and workload level, which directly affects how storage and compute infrastructure are assessed when paired with intensive AI pipelines. Information security management expectations have also tightened, raising the evidence threshold for data center controls. For enterprises, this means storage selection is becoming more closely linked to sustainability reporting, auditability, and verifiable governance rather than raw performance claims alone.
Next Gen Supply Chain Market
Demand-Side Behavior and AI-Induced Workload Shifts
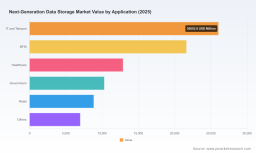
Demand patterns are being reconfigured by the expansion of AI training, inference, and analytics pipelines. These workloads generate sustained pressure for high-throughput, low-latency storage that can serve both bursty checkpointing and continuous data feeding. Beyond AI, vertical demand remains broad, with information technology and telecommunications, financial services, healthcare, government, and retail all contributing meaningfully to adoption. What distinguishes the current cycle is the way these sectors are combining scale with specificity: financial services and healthcare emphasize resilience and compliance, while media and retail environments prioritize throughput for large media assets and rapidly changing catalogs. Enterprise behavior is shifting from incremental array upgrades toward platform decisions that anticipate hybrid cloud data movement, data reduction, and unified management across on-premises and cloud-connected environments.
Supply-Side Evolution and Cost Structure Realignment
Supply-side dynamics are being reshaped by both component-level innovation and strategic partnerships. Memory and storage manufacturers continue to advance NAND, DRAM, and high-capacity drive technologies, with research into heat-assisted magnetic recording and next-generation non-volatile memory supporting capacity scaling for data center and archival use cases. Simultaneously, partnerships are accelerating the maturation of frontier technologies; for example, a recent collaboration focused on synthetic DNA storage is directed at accelerating scaling through chip design, fabrication, and integration expertise. Patent activity in next-generation memory and thermal architecture further illustrates the competitive race to protect differentiated approaches in performance, thermal management, and dual-mode memory applications. These developments suggest that cost structures will remain volatile in the near term, with advantages accruing to players that can align component roadmap timing, packaging efficiency, and ecosystem integration.
Competitive Landscape and Leading Strategies
The competitive field combines established enterprise storage incumbents, component specialists, and a small but strategically important set of frontier-technology entrants. Large system vendors are positioning around scalable arrays, hybrid cloud integration, and AI workload optimization. Their differentiation tends to rest on integrated hardware-plus-software platforms, broad deployment footprints, and the ability to align storage with broader infrastructure roadmaps. All-flash specialists are competing on performance sustainability and architectural simplicity, emphasizing refresh models that reduce forklift upgrades and support long-term operational predictability. Component manufacturers are competing on density, endurance, and roadmap visibility, using advanced flash, persistent memory, and emerging memory technologies to influence the underlying economics of finished storage systems.
PW Consulting
A notable theme is the divergence between scale-oriented storage and frontier archival research. Incumbents are refining arrays, data services, and hybrid cloud data management to serve production enterprise environments, while newer entrants and spin-outs are pursuing ultra-dense, long-term archival via synthetic DNA and high-reliability persistent memory for specialized applications. This bifurcation is creating a layered market in which mainstream enterprise buyers evaluate proven platforms for daily operations, while innovators and early adopters pilot complementary technologies for retention, compliance, and extreme-density use cases.
Strategic positioning is increasingly defined by three differentiators. The first is workload affinity: vendors that explicitly tailor storage behavior to AI pipelines, checkpointing patterns, and hybrid data services are gaining traction with buyers who need more than generic capacity. The second is operational continuity, where subscription-like refresh architectures and unified management reduce disruption and lifecycle cost. The third is technology-optionality, where companies preserve access to multiple memory and storage paths rather than betting on a single medium. That optionality is especially valuable while grid constraints, efficiency metrics, and security expectations are all tightening at once.
Market structure is evolving through both consolidation and fragmentation. Consolidation pressure exists where scale advantages in manufacturing, integration, and distribution matter most, and where buyers prefer fewer vendors for support and interoperability. Fragmentation pressure exists where new storage paradigms, specialized memory, and archival formats open breakout niches. Recent partnership announcements, product showcases for AI-optimized RAID platforms, and continued patent activity indicate that both forces are active simultaneously, with incumbents defending core segments while newer players attempt to own emerging categories.
Future Trends and Strategic Implications
Over the next three to five years, one likely trend is the normalization of workload-specific storage architectures. Rather than a uniform proliferation of a single array type, deployments will increasingly match storage medium and software behavior to workload durability and access patterns. High-performance flash and hybrid configurations will continue to anchor production environments, while object storage, persistent memory, and DNA-based archival will occupy increasingly defined roles for retention, large-scale analytics, and long-tail data. The commercial opportunity here lies in platform design that can orchestrate these tiers without creating operational friction.
A second trend is the integration of storage decisions with energy and sustainability planning. As efficiency metrics and AI environmental impact measurement become more embedded in procurement and reporting, storage vendors and buyers will need to treat power usage, cooling interaction, and site readiness as first-order selection criteria. Providers that can demonstrate verifiable efficiency behavior and support behind-the-meter or co-located energy strategies will have an advantage in constrained markets. The opportunity is not merely compliance; it is the ability to deploy and scale storage where grid timelines and operating costs would otherwise delay expansion.
A third trend is the ongoing blurring of storage, memory, and data management boundaries. As AI and analytics workloads mature, the value of raw capacity will be supplemented by the value of data placement, reduction, protection, and access optimization. This creates opportunities for suppliers that can deliver integrated data services across hybrid environments and for buyers that can consolidate management while preserving flexibility. The principal uncertainty is timing: emerging technologies may scale more slowly than optimistic roadmaps suggest, and regulatory or technical standardization may shift cost-benefit calculations before some categories reach broad commercial maturity.
Next-Generation Advanced Batteries Market
Actionable Guidance for Decision Makers
For storage manufacturers and technology suppliers, the priority is to align roadmap investments with workload-driven demand rather than assuming uniform replacement cycles. Companies should accelerate validation and ecosystem compatibility for high-reliability memory, optimize thermal and power profiles for dense deployments, and prepare commercialization pathways for frontier archival technologies without overcommitting to a single medium. Clear differentiation around AI workload support, lifecycle continuity, and verifiable efficiency will matter more than headline capacity claims.
For investors, the market offers a layered opportunity set rather than a single winner-takes-all narrative. Capital allocation should distinguish between mature platform economics, component-level technology leadership, and early-stage archival or persistent-memory plays with longer commercialization horizons. Due diligence should account for energy constraints, compliance evolution, and the pace at which emerging standards affect operating costs and procurement preferences.
For enterprise buyers and procurement leaders, the most important shift is to evaluate storage as an integrated infrastructure decision. Selection criteria should incorporate energy behavior, data services, hybrid cloud interoperability, and compliance evidence alongside performance. Piloting complementary technologies for targeted retention or high-reliability needs can preserve optionality while maintaining production stability on proven platforms.
Detailed segmentation data, region-specific dynamics, competitive benchmarking, and customized scenario analysis are available in the full PW Consulting study for teams that need to translate these strategic themes into procurement plans, investment theses, and product roadmaps.
For detailed analysis of this topic, please visit the official page: Worldwide Next-Generation Data Storage Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com