

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
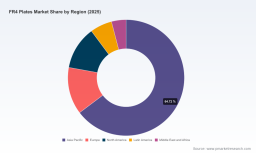
FR4 Plates Market: Why 6.15% CAGR and Asia Pacific’s 64% Share Redefine 2026 Strategy

Navigating the Worldwide FR4 Plates Market: Strategic Trends, Competitive Dynamics, and Commercial Pathways (2026–2032)
Market Landscape and Core Challenges
The worldwide FR4 plates market has evolved from a mature, commoditized segment into a strategically sensitive materials ecosystem shaped by rapid electronics expansion, regulatory tightening, and structural cost volatility. Valued at approximately USD 12,500 million in 2025, the market expanded from roughly USD 9,245.5 million at the start of the past five-year historical window. The trajectory reflects consistent demand absorption across industrial, consumer, and infrastructure electronics, with the compound annual growth rate over 2026 to 2032 projected at 6.15%. This growth rate, while solid, conceals underlying friction: the market is expanding fast enough to reward innovation, yet slowly enough that margin compression, raw material sensitivity, and compliance compliance remain persistent headwinds for suppliers that fail to align product mix with downstream performance requirements.
Worldwide Insulating Plate Market
The first structural challenge lies in cost volatility transmitted through interdependent raw material chains. FR4 laminate production depends on epoxy resin systems, electronic glass fiber cloth, and copper foil, each of which has experienced pronounced pricing swings and supply interruptions in recent periods. Regional resin price divergence, glass fiber cloth increases, and copper-linked cost pass-through have repeatedly triggered price adjustments across copper clad laminates, forcing manufacturers to balance margin preservation against competitive pressure. The second challenge centers on performance differentiation versus cost optimization. As end-use electronics increasingly demand higher thermal stability, improved moisture resistance, and smaller, more densely routed board architectures, standard-grade FR4 faces incremental pressure from enhanced-Tg, halogen-free, and multifunctional variants. Suppliers must continuously justify premium positioning without alienating cost-sensitive buyers. The third challenge involves regulatory and environmental compliance. Global frameworks continue to mandate restrictions on hazardous substances and push formulation changes toward halogen-free and lead-free chemistries. Maintaining compliance while preserving electrical, mechanical, and thermal performance requires ongoing R&D investment and tighter materials control, especially for large-volume producers serving multi-region OEMs.
Aluminum Plates Market
Against this backdrop, the overall market structure remains moderately concentrated, with the largest players consolidating meaningful share and a broader base of regional producers and distributors competing on availability, service responsiveness, and specialty grades. Concentration tends to amplify the strategic importance of certifications, formulation flexibility, and supply reliability, because large downstream customers increasingly view laminate suppliers as partners in yield optimization and manufacturing continuity rather than interchangeable commodity vendors. The market is not fragmented in the traditional sense, but neither has it consolidated into a single-price environment; instead, multiple pricing tiers and specialty lanes coexist, each with different profitability dynamics.
Key Demand and Supply Drivers Shaping the Market
Three interlocking forces are steering market direction more than any single factor: material science advances that widen the performance envelope of FR4 systems, regulatory and sustainability mandates that reshape formulation requirements, and demand-side shifts across automotive, consumer, telecom, and industrial electronics that change volume and specification mix. A fourth force, supply chain and cost structure dynamics, determines which producers can convert these shifts into margin expansion rather than cost absorption.
Innovation in epoxy formulations, glass fiber treatment, and copper interface design is expanding the practical use range of FR4-family materials. High-Tg variants, for example, support lead-free assembly profiles and higher operating temperatures, enabling adoption in applications where thermal excursions would previously drive designers toward more expensive substrate alternatives. Halogen-free grades address environmental and safety expectations without fully sacrificing flame retardancy or mechanical integrity. Multifunctional and enhanced formulations aim to deliver better signal integrity, lower warpage, and improved dimensional stability, particularly in multilayer constructions where interlayer consistency and registration matter. These advances do not merely create new product lines; they shift downstream design decisions. When a laminate grade can withstand higher process temperatures, withstand moisture exposure more effectively, or reduce build variability, OEMs can simplify assembly, reduce defect rates, and in some cases defer migration to premium substrate classes. This expands total addressable demand for advanced FR4 rather than simply cannibalizing standard grades.
Regulatory frameworks are a second major driver, especially in markets where electronics are broadly exported. RoHS remains mandatory for FR-4 materials in electronics applications, restricting hazardous substances such as lead, mercury, and certain flame retardants, while EU RoHS and REACH frameworks continue to accelerate reformulation toward halogen-free and lead-free variants for global compliance. These requirements are not static hurdles; they influence qualification cycles, documentation practices, and the relative attractiveness of different supplier bases. Companies that maintain current declarations, updated supplemental datasheets, and traceable material statements lower friction for design-in and volume ramp, while slower documentation processes can become a hidden competitive disadvantage even when technical performance is comparable.
On the demand side, electrification and connectivity trends are generating sustained pull for reliable, cost-effective laminate materials. Automotive electronics growth reflects broader vehicle electronic content expansion, demanding materials that combine reliability with cost efficiency across both heritage and emerging vehicle architectures. Consumer electronics continues to drive high-volume absorption, though design cycles, miniaturization, and upgrade pacing create demand volatility at the product level. Telecommunications infrastructure, including data center buildout, networking equipment, and wireless systems, supports steady need for boards that must meet consistent performance and serviceability expectations. Industrial and medical electronics contribute a more stable, specification-sensitive demand layer where qualification thresholds are higher and product longevity matters more than rapid replacement cycles. Collectively, these demand layers create a diversified revenue base, but they also pressure suppliers to maintain a broad grade portfolio and flexible production scheduling.
The cost and supply structure remains the most volatile driver. Epoxy resin pricing varies widely by region, with Northeast Asia and Europe showing markedly different averages due to feedstock dynamics and logistics. Copper price fluctuations have repeatedly contributed to CCL and FR-4 price increases, and electronic glass fiber cloth pricing has risen year-on-year with further increases anticipated. These inputs do not move in unison, which complicates hedging and pricing strategy. Producers with vertical integration, diversified sourcing, or better positioning in regional feedstock markets can pass through costs more smoothly, while smaller or more exposed suppliers may face margin erosion during periods of rapid input inflation. The result is a market where commercial resilience increasingly depends on procurement strategy, formulation efficiency, and the ability to communicate value beyond unit price.
Competitive Landscape and Leading Strategies
The competitive field spans multinational laminate specialists, vertically integrated Asian producers, regional manufacturers, and global distributors serving machined and industrial applications. This mix produces a market where technical reputation, regional availability, and compliance readiness are often as decisive as unit cost. Leading firms compete through a combination of grade breadth, formulation control, certification readiness, and application support, rather than through price leadership alone.
Isola Group has positioned itself around high-performance FR-4 epoxy laminates and prepregs for multilayer PCBs, with emphasis on lead-free assembly, high Tg, and reliability. Its recent reinforcement of supplemental datasheets and RoHS declarations for high-Tg systems illustrates a strategy of reducing qualification friction for design engineers and procurement teams. By keeping documentation aligned with current regulations and application expectations, Isola strengthens its role in customers where materials must be traceable and consistently qualified.
Ventec International Group competes with a broad range of standard FR-4 epoxy-glass laminates and prepregs across core thicknesses and copper gauges, including halogen-free variants for low- to high-power applications. Its strategy highlights coverage and versatility, enabling it to serve diverse PCB power and thermal requirements while offering environmentally aligned options that reduce re-qualification burden when customers shift toward halogen-free specifications.
Kingboard Laminates Holdings Ltd operates as a major vertically integrated producer of glass-based copper clad FR-4 laminates, offering conventional, lead-free, and halogen-free grades. Vertical integration supports cost control and supply continuity, and its recent pricing actions on copper clad laminates reflect the broader industry reality of rising copper and fiberglass feedstock costs. In this environment, integrated players can sometimes manage pass-through more predictably, though they must still defend volume retention during price increases.
Nan Ya Plastics Corporation emphasizes FR-4 copper clad laminates across multiple Tg levels, including high-Tg and multifunctional grades, with a stated focus on environmental compliance for consumer electronics and automotive applications. Its positioning illustrates how large-scale producers align grade variety with downstream industry priorities, using scale and compliance consistency to serve high-volume design-ins where documentation and repeatability matter.
In the U.S. and broader distribution channels, Current Inc. and Professional Plastics serve electrical-grade and industrial/electronics applications with FR-4/G-10 glass epoxy sheets, rods, tubes, and machined-ready stock. These players compete on availability, cut-to-size service, and breadth of thicknesses, supporting users who need insulation, structural, and reinforcement solutions outside the core PCB laminate flow. Meanwhile, large-scale Chinese producers such as Hebei JingHong Electronic Technology and Jiujiang Leadcomp focus on FR-4 epoxy fiberglass sheets and industrial sheets, with emphasis on precision cutting, large-capacity supply, and regional service including Middle East demand.
The overall competitive trend is one of parallel differentiation. Large integrated or specialty-focused producers concentrate on certifications, higher-performance grades, and application engineering, while distributors and regional sheet manufacturers compete around availability, lead times, and machining flexibility. Market evolution is likely to continue along this path, with selective consolidation among producers seeking scale or feedstock advantages, and new entrants or expanded regional players competing where service responsiveness and localized inventory create value. The most resilient companies will be those that can combine compliance readiness, formulation control, and dependable delivery without relying on a single cost posture.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, three trends will likely define commercial outcomes more than incremental volume growth alone. First, specification migration toward high-Tg and halogen-free FR4 variants will continue, driven by lead-free assembly requirements, thermal expectations, and regulatory pressure. This trend does not eliminate standard grades, but it raises the premium on suppliers that can offer a smooth spectrum from standard to enhanced formulations without disrupting qualification cycles. Commercial opportunity lies in offering application-aligned packaging of grades, supporting faster design-in and reducing the cost of switching.
Second, raw material volatility will become a structural planning variable rather than a periodic disruption. Resin, copper, and glass fiber pricing divergence across regions means that procurement strategy, inventory positioning, and regional sourcing flexibility will increasingly determine profitability. Companies able to coordinate feedstock exposure, hedge selectively where appropriate, and communicate transparent pricing logic will preserve customer trust better than those that react late or inconsistently. The associated opportunity is in supply reliability and predictability, especially for customers running continuous production or tight delivery schedules.
PW Consulting
Third, the relationship between laminate suppliers and downstream manufacturers will shift toward more integrated qualification and service models. Documentation currency, RoHS compliance posture, and material traceability are moving from administrative tasks to procurement criteria. Suppliers that treat datasheets, compliance statements, and application support as core assets will gain an advantage in design-in decisions and volume retention. The risk is that competitors offering similar electrical and mechanical performance can erode share if they reduce lead times, improve localized stock, or simplify ordering. Uncertainty remains around the pace of regulatory evolution, the trajectory of copper and resin pricing, and the timing of demand swings in consumer electronics and automotive content cycles. These variables reward flexibility and penalize rigid cost structures.
Strategic Recommendations for Decision-Makers
For laminate producers and materials formulators, the priority is to align grade portfolios with the practical performance needs of high-growth applications while maintaining documentation and compliance readiness as commercial assets. Investment in higher-Tg, halogen-free, and application-tailored variants should be paired with clear qualification support, so that technical gains translate into design-in speed and repeat orders. Strengthening feedstock visibility and regional sourcing flexibility will also help protect margins when input costs move unevenly.
For investors, the most durable value opportunities are likely in suppliers with a credible mix of scale, compliance discipline, and differentiated grades, rather than in undifferentiated commodity exposure alone. Evaluation should consider vertical integration benefits, documentation and certification readiness, and exposure to raw material volatility, since these factors shape both growth capture and margin stability. Companies that can demonstrate consistent product availability and predictable commercial response to input inflation are better positioned to retain share during pricing cycles.
For procurement and engineering leaders, the immediate focus should be on supplier qualification breadth and documentation reliability as much as unit price. Establishing multi-grade sourcing options, confirming current RoHS and material declarations, and understanding each supplier's ability to support halogen-free or higher-Tg transitions can reduce future qualification risk. Where application requirements are moving toward higher thermal stability or environmental compliance, early engagement with suppliers can shorten design cycles and limit disruptions during volume ramp. A more detailed segmentation view of regional demand balance, type-level migration patterns, and application-specific volume dynamics can sharpen sourcing and planning decisions, and a full market study remains the most efficient way to access that level of detail.
For detailed analysis of this topic, please visit the official page: Worldwide FR4 Plates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com