

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Cruet Market Outlook 2026: Beyond the 4.92% CAGR to $1.2B

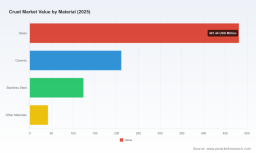
Worldwide Cruet Market: Strategic Trends and Commercial Opportunities (2025–2032)
Market Landscape and Core Challenges
The worldwide cruet market has evolved into a mature yet resilient segment within the broader home and foodservice tabletop ecosystem. Valued at approximately USD 858.0 million in 2025, the market has demonstrated steady expansion over the past five years, growing from USD 682.4 million in 2020. This trajectory reflects a compound annual growth rate of 4.92% and projects a sustained climb toward USD 1.2 billion by 2032. The consistent upward pathway underscores a category that is no longer purely discretionary but increasingly integrated into dining rituals, hospitality service standards, and premium home entertaining.
Several structural realities define the current operating environment. First, the market operates with a relatively fragmented concentration profile, meaning no single entity or tight oligopoly controls pricing or channel dynamics. This fragmentation creates both agility for niche players and margin pressure for mid-tier manufacturers that lack clear differentiation. Second, the product category sits at the intersection of aesthetics, functionality, and supply chain vulnerability. Cruets are simultaneously serving vessels, storage solutions, and design objects, which means manufacturers must balance material performance, pour precision, finishing quality, and visual appeal across diverse end-use settings. Third, the category is navigating a transition from traditional offline wholesale and retail dominance toward multi-channel selling models, which reshapes how new products are launched, how inventory is managed, and how consumer feedback reaches product developers.
These dynamics produce a set of practical challenges for executives. Margin management has become more complex as input cost volatility intersects with competitive pricing expectations. Product development cycles must now account for material availability, regional regulatory exposure, and the speed at which design trends circulate through digital commerce. At the same time, the category must preserve its core value proposition: reliable dispensing, appropriate material durability, and visual alignment with dining environments. In short, the market is expanding, but the expansion is uneven, and success increasingly depends on how well companies convert structural pressures into design, sourcing, and channel advantages.
Key Drivers Shaping Market Trajectory
Material Innovation and Performance Expectations
The performance bar for cruets has risen beyond basic containment. Consumers and foodservice buyers now expect controlled dispensing, clean pour lines, drip reduction, and materials that withstand frequent use without compromising appearance. Glass continues to anchor the category because it offers clarity, neutrality with food products, and strong visual appeal in both domestic and commercial table settings. Yet the material itself is evolving through formulation improvements, better seal and stopper integration, and more refined pourer engineering. Recent recognition of innovative tabletop designs at major industry award programs highlights how even a familiar product class can be re-examined for ergonomics, serving precision, and presentation value.
At the same time, material economics are reshaping cost structures. Input price movements for silica sand and soda ash have placed upward pressure on glass production costs, prompting manufacturers to re-evaluate batch efficiency, scrap recovery, and alternative material blends. The use of recycled glass in production has become a practical lever for reducing raw material demand and energy consumption, with modern manufacturing practices increasingly incorporating substantial cullet fractions into the batch. This is not only an operational efficiency consideration; it also aligns with growing expectations around responsible sourcing and product lifecycle thinking. For cruet producers, material strategy is now inseparable from cost control, product consistency, and brand positioning.
Regulatory and Trade Environment Pressures
Regulatory dynamics are introducing a new layer of cost and compliance complexity, particularly for manufacturers and importers exposed to cross-border glass trade. Policy instruments aimed at carbon intensity in imported goods are beginning to affect the economics of glassware supply chains. For categories like cruets, where glass is often sourced, processed, and finished across multiple geographies, these measures can alter landed costs, sourcing selections, and lead-time planning. The effect is not simply a tax issue; it is a structural incentive to reconsider where and how glass components are manufactured, whether regional production can be strengthened, and how carbon exposure can be reduced through material mix and process efficiency.
At the same time, regulatory pressure can accelerate differentiation. Companies that proactively adapt production methods, improve energy efficiency, and document compliance readiness may convert a cost headwind into a competitive advantage in premium segments where sourcing transparency and sustainability performance matter to buyers. The broader implication is that regulatory change is becoming a design and sourcing variable rather than a back-office compliance task.
PW Consulting
Demand-Side Shifts in Home and Foodservice Settings
Demand is being shaped by evolving dining behavior on both sides of the market. In household contexts, there is continued interest in elevated home dining experiences, where serving oils, vinegars, and dressings in dedicated vessels contributes to perceived quality and convenience. In foodservice, cruets remain relevant as practical service tools, but their role is expanding into broader tabletop coordination, including synchronized serving sets, rack systems, and coordinated presentation elements. The category is benefiting from a mindset in which the serving vessel is not an afterthought but part of the overall dining impression.
Distribution is also changing the way demand is expressed. Online commerce has become a meaningful channel for the category, giving smaller brands and specialty designs easier access to end users while enabling faster response to visual trends and seasonal presentation preferences. This does not replace traditional retail and foodservice wholesale; rather, it creates a dual pathway in which product visibility, packaging, and assortments must be optimized for both in-person evaluation and digital discovery. Product lines that can perform across both environments tend to capture broader demand without artificially splitting brand identity.
Worldwide Fermenting Crocks Market
Supply Chain Reconfiguration and Cost Structure Adjustment
The cruet market is experiencing a broader reconfiguration of how products are manufactured, stored, and delivered. Cost pressures in raw materials are prompting closer scrutiny of supplier relationships, order batching, and inventory positioning. In parallel, manufacturers are paying greater attention to component standardization, especially for pourers, stoppers, caps, and rack hardware, where small specification differences can affect assembly efficiency and finished-product consistency. Companies that reduce unnecessary variation in components while preserving design distinction are often better positioned to manage labor, tooling, and quality control costs.
Another important shift is the increasing weight of product assortments as a commercial tool. Updated catalogs and expanded item families allow suppliers to address multiple price points, service needs, and aesthetic preferences without fragmenting core manufacturing capabilities. This approach helps balance volume consistency with merchandise breadth, especially for distributors and foodservice suppliers managing large customer bases. The practical outcome is a market where assortment architecture is becoming as important as unit economics.
Competitive Landscape and Leading Strategies
The competitive field in this category is diversified, with companies pursuing different strategic positions rather than converging on a single winning formula. Several established manufacturers rely on design credibility, material quality, and coordinated product families to anchor premium placements. Others operate with a stronger emphasis on utility, volume availability, and foodservice practicality. The result is a market in which positioning, rather than scale alone, often determines commercial performance.
A distinctive feature of the leading players is how they link product design to use context. Some emphasize refined glass forms, cork stoppers, and coordinated sets that suit table service and home entertaining. Others concentrate on practical foodservice configurations, including pourers, racks, and standardized sets that simplify service workflows and inventory management. A third group focuses on controlled dispensing performance, using precision spouts and seal systems to improve usability and reduce waste during serving. These differing value propositions indicate that the category is not contested purely on price; it is contested on how effectively each product answers a specific dining or service need.
Strategic differentiation also appears in the way companies expand their offerings. Some have broadened their tabletop portfolios into larger cruet and serving sets to capture cross-selling opportunities and strengthen assortment credibility. Others have emphasized updated catalogs and refreshed item lines to keep pace with buyer expectations and changing foodservice specifications. Trade visibility remains important as well, with select brands presenting new collections at major marketplace events to reach both wholesale buyers and design-conscious retail partners. This blend of product refreshes, portfolio expansion, and channel presence suggests a market where brand relevance is maintained through continuity of innovation rather than one-time launches.
Market structure appears to be moving toward selective consolidation of capability rather than uniform concentration. Larger, multi-product suppliers may gain advantages in sourcing leverage, assortment breadth, and distribution reach, while specialized manufacturers can retain resilience by owning a clear design or performance niche. New entrants typically need a focused point of entry, such as a distinctive material execution, a tighter foodservice specification, or a design language that stands out in visual commerce environments. The most durable strategies tend to combine a defensible product identity with enough operational flexibility to respond to input cost changes and channel shifts.
Forward Trends and Commercial Opportunities
Over the next three to five years, the cruet market is likely to be shaped by three interrelated developments. The first is a continued elevation of functional design. Pour control, drip management, stopper reliability, and material durability will remain central purchasing criteria, especially as buyers compare products across offline and online environments where first impressions and repeat use both matter. Products that integrate usability with attractive presentation will have an advantage in premium household and hospitality applications.
The second trend is a more disciplined approach to material sourcing and production efficiency. As raw material costs and regulatory exposure continue to influence margins, companies that strengthen batch efficiency, incorporate recycled content thoughtfully, and align sourcing with regional compliance realities will be better positioned to protect profitability. This creates an opportunity for suppliers that can offer consistent quality while demonstrating pragmatic cost management and responsible material practices.
Golden Crucible Market
The third trend is channel-driven product strategy. Online discovery, visual merchandising, and faster assortment turnover will increasingly influence which designs gain traction and how quickly new variations are introduced. At the same time, traditional foodservice and retail channels will still demand dependable volume, standardized specifications, and durable service performance. Companies that can align one coherent product identity with multiple channel requirements are likely to capture broader demand without diluting brand clarity.
These trends open practical commercial opportunities. There is room for differentiated cruet sets that combine dispensing precision with coordinated presentation features. There is also opportunity for manufacturers and distributors to refine assortment depth, matching price points and specifications to distinct customer segments rather than relying on a single generic offering. For premium positioning, design credibility and material consistency can support higher value capture, while for volume-oriented segments, operational reliability and efficient sourcing will remain decisive. The main uncertainty lies in how quickly input cost pressures and trade-related cost adjustments will affect pricing behavior, and whether demand resilience holds if discretionary spending becomes more cautious in certain regions.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to treat product design and sourcing strategy as one integrated system. Differentiate through pour performance, durability, and coordinated set architecture, while simultaneously improving material efficiency and supplier flexibility. Standardize where it reduces complexity, but preserve enough design distinctiveness to avoid commoditization.
For investors, the relevant question is not whether the category will grow, but which business models are best equipped to convert growth into margin stability. Models with clear positioning, controlled cost structures, and the ability to serve both offline and online demand are better placed to withstand input volatility and channel competition. Particular attention should be paid to companies that can demonstrate consistent assortment renewal without over-expanding complexity.
For procurement and buying teams, the focus should be on specifications that balance appearance, dispensing reliability, and total cost of ownership. Evaluate supplier readiness around material sourcing, compliance exposure, and replenishment consistency, especially for glass components subject to cost and trade dynamics. A disciplined purchasing approach will help maintain service quality while reducing exposure to short-term supply disruption.
Detailed segmentation data, regional volume patterns, company-level comparisons, and scenario-based forecasts can materially sharpen these decisions. For decision-makers seeking a deeper view of market structure, competitive positioning, and forward risk, the full research report provides a more granular foundation for planning.
For detailed analysis of this topic, please visit the official page: Worldwide Cruet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com