

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Tubular Tongs Market: Why the 5.15% CAGR Trajectory Changes Everything

Strategic Trends and Commercial Opportunities in the Worldwide Tubular Tongs Market
Market Landscape and Core Challenges
The global tubular tongs market has demonstrated steady expansion over the past five years, reflecting the broader resilience of drilling and well servicing activities. In 2025, the market reached a valuation of approximately USD 1.65 billion, building on a consistent growth trajectory that began in 2020. Looking ahead to 2032, the market is projected to surpass the USD 2.35 billion threshold, driven by a compound annual growth rate of 5.15 percent. This growth pattern underscores a sector that is not merely expanding in absolute terms but is also evolving in response to changing operational requirements, safety mandates, and technological expectations across global oilfield operations.
Despite this positive trajectory, the industry stands at a critical inflection point. The first major challenge lies in balancing operational safety and efficiency with the physical and logistical constraints of modern drilling environments. Tubular handling remains one of the most high-risk activities on the rig floor, and the demand for precision, repeatability, and reduced manual intervention has intensified. Operators are increasingly unwilling to tolerate equipment that introduces variability in make-up and break-out procedures, particularly when premium connections and high-strength tubulars are involved. This shift places pressure on manufacturers to deliver tools that not only meet torque requirements but also integrate seamlessly with automated and mechanized rig systems.
A second challenge stems from supply chain volatility and input cost pressures. High-strength alloy steel forms the backbone of tubular tongs bodies and critical components, enabling equipment to withstand extreme torque loads and harsh downhole conditions. Throughout 2025, steel prices for oil and gas applications remained above historical averages, with moderate increases anticipated into 2026 as energy infrastructure demand continues to absorb available supply. For equipment manufacturers and service providers, this translates into higher production costs, longer lead times, and the need to reassess pricing strategies without eroding competitiveness. Companies that fail to secure stable sourcing channels or optimize material usage risk margin compression in an environment where operational budgets are already under scrutiny.
The third challenge revolves around market concentration and the evolving expectations of procurement teams. The market is moderately consolidated, with the top three players accounting for nearly 38.4 percent of total revenue and the top five commanding approximately 52.15 percent. Such concentration suggests that established manufacturers enjoy meaningful advantages in brand recognition, technical support, and product certification. Yet it also signals limited room for undifferentiated newcomers. Buyers are increasingly evaluating suppliers not just on hardware performance but on lifecycle support, compliance documentation, and compatibility with digital rig ecosystems. For stakeholders operating in this space, the ability to demonstrate measurable reliability and regulatory adherence has become as important as the engineering specifications themselves.
PW Consulting
Key Drivers Shaping Market Dynamics
Technological Innovation and the Push Toward Mechanization
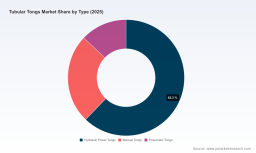
Technological advancement is the most visible force reshaping the tubular tongs market. Hydraulic power tongs have become the dominant configuration by revenue, reflecting their ability to deliver consistent torque, reduce operator fatigue, and support repeatable tubular running procedures. Leading manufacturers have expanded their portfolios to cover a wide range of sizes and torque ratings, from smaller-diameter tubing applications to large-bore casing and drillpipe operations. The emphasis has shifted from simply generating high torque to engineering systems that feature advanced torque monitoring, interchangeable gear designs, and compatibility with automated rig floor setups. This trend is closely tied to the broader industry movement toward mechanized drilling and integrated rig technologies, where equipment must communicate effectively with positioning systems and operating controls.
The demand for higher torque capacity also reflects the growing use of premium connections and challenging well architectures. As operators push into deeper and more complex reservoirs, the margins for error in tubular running shrink. Equipment that offers precise torque application, real-time feedback, and robust designs for corrosive or high-pressure environments is increasingly viewed as essential rather than optional. Companies that invest in product lines capable of supporting these requirements, including high-torque variants and specialized configurations for offshore packages, are well positioned to capture demand from operators seeking to reduce non-productive time and improve well integrity.
Regulatory Standards and Compliance as a Competitive Moat
Regulatory and standards-based expectations continue to define the operational baseline for tubular handling equipment. Tubular tongs and related tools are manufactured to align with API 7K specifications for the design, manufacturing, and testing of drilling and well servicing equipment, and many suppliers also adhere to API 8A standards alongside ISO 9001 quality procedures. These frameworks are not merely formalities; they serve as critical benchmarks for safety, performance, and buyer confidence. In a market where equipment failures can lead to costly well control issues or personnel hazards, certification and documented quality processes have become decisive factors in procurement decisions.
Compliance also influences how manufacturers structure their product development and support networks. Companies that can demonstrate consistent adherence to recognized standards across multiple product lines gain an advantage in competitive bidding, particularly among operators with strict vendor qualification processes. This dynamic creates a self-reinforcing pattern: established players with extensive certification portfolios and documented field performance make it harder for new entrants to compete without similar credentials. At the same time, the standards landscape encourages ongoing product refinement, as manufacturers update designs and testing protocols to reflect evolving best practices in tubular running safety and efficiency.
Demand-Side Shifts in Drilling and Workover Activities
On the demand side, the market is being shaped by the changing mix of drilling, completion, and workover activities. Drill pipe and casing handling remains the largest application area, driven by the ongoing need to run and retrieve tubulars efficiently across a broad range of well types. Tubing services and workover operations also represent significant demand sources, particularly in mature basins where production optimization and well intervention are prioritized over greenfield drilling. This diversification matters because it creates multiple demand pockets that can respond differently to commodity price cycles and regional activity levels.
Tubular Cable Lugs Market
Operator behavior is also shifting toward equipment that supports faster setup, reduced rig time, and lower operational risk. The preference for hydraulic systems over purely manual configurations reflects not only torque requirements but also the desire for more predictable handling processes. Pneumatic tongs continue to serve specific niches where compressed air availability or particular site constraints make them a practical choice, but the broader trend favors solutions that combine power, control, and integration potential. For suppliers, this means that product breadth and adaptability across application scenarios are becoming increasingly valuable, especially when paired with rental, service, and aftermarket support options that help customers manage capital expenditures.
Cost Structures, Material Inputs, and Supply Chain Strategy
Cost dynamics remain a central driver of strategic decision-making. The reliance on high-strength alloy steel means that material pricing, availability, and lead times directly affect manufacturing economics. With steel costs for oil and gas applications staying elevated through 2025 and expected to rise moderately into 2026, companies are being forced to reconsider how they manage procurement, inventory, and product design. Options include securing long-term supply agreements, optimizing component geometries to reduce material intensity, and differentiating through service and digital capabilities rather than competing solely on hardware price.
The supply chain environment also affects how equipment reaches end users. In recent months, power tong models from multiple manufacturers have appeared across oilfield equipment marketplaces as available for sale or rental, indicating a market that values flexibility in acquisition. Rental and used-equipment channels can provide cost-effective access for shorter campaigns or specialized projects, but they also place pressure on original equipment manufacturers to maintain strong brand value and performance differentiation. Suppliers that can offer clear traceability, maintenance support, and certified reconditioning processes are better positioned to retain influence over how their products are deployed throughout the equipment lifecycle.
Competitive Landscape and Leading Strategies
The tubular tongs market features a mix of specialized manufacturers and larger equipment providers, each pursuing distinct strategic positions. Eckel Manufacturing Co., Inc. has built a long-standing reputation as a focused producer of hydraulic power tongs, offering a broad range of models for tubing, casing, drillpipe, and riser applications with torque capabilities reaching up to 200,000 ft-lbs. The company's emphasis on a wide model portfolio and specialized high-torque variants for premium connections illustrates a strategy centered on product depth and application-specific engineering. For customers, this breadth translates into the ability to source multiple configurations from a single supplier, which can simplify procurement and support arrangements.
McCoy Global Inc. occupies a strong position in hydraulic power tongs for make-up and break-out operations on rigs and offshore packages. Its product lineup includes high-torque configurations such as the 10-inch 40K model for higher torque connections, and its equipment is associated with advanced torque monitoring as part of a broader smart tooling suite. This approach highlights a strategic focus on precision control and digital readiness, appealing to operators that prioritize data-rich running procedures and consistent connection quality. By embedding monitoring and control features into core hardware, such suppliers aim to move beyond commodity equipment and toward value-added operational support.
Weatherford International provides a comprehensive range of hydraulic power tongs spanning casing, tubing, drillpipe, premium connections, and risers, with models designed for varied torque ratings and integrated compatibility with positioning systems. As a global player with broad operational reach, Weatherford leverages scale, service networks, and cross-product integration to serve customers across multiple phases of well construction and intervention. Its strategy underscores the advantage of offering a full-spectrum tubular running portfolio, where equipment can be aligned with broader rig technology and well services offerings. This integrated positioning can be particularly attractive to operators seeking to standardize equipment interfaces and reduce variability across field operations.
Other notable participants reinforce the market's diversity. Starr Power Tongs, LLC manufactures high-quality hydraulic tongs for casing and tubing, including models capable of handling CRA tubulars, and distributes through authorized partners to extend regional support. Magnum Manufacturing, operating through Premiere, Inc., specializes in hydraulic power tongs and casing running tools with high torque-to-weight ratios and interchangeable gear designs for conventional tubulars across a wide size range. Midland Oil Tools offers hydraulic tongs for tubing, casing, sucker rod, drillpipe, and workover operations, with products manufactured to API 7K and 8A standards and including TEDA-style models for drilling and well service applications. Forum Energy Technologies produces manual and power tongs for drill pipe, casing, and collars up to 42 inches, with torque ratings up to 160,000 ft-lbs, maintaining a strong focus on rig floor pipe handling equipment. National Oilwell Varco supplies power tongs and related tubular handling equipment as part of its broader rig technology portfolio, reinforcing the trend toward integrated drilling solutions.
Recent market activity illustrates how these companies are staying visible and relevant. In late 2025, Starr Power Tongs exhibited hydraulic power tongs at ADIPEC, emphasizing durable models for oil and gas tubular operations, while listings from equipment marketplaces showed models from Eckel, Weatherford, and other suppliers available for sale or rental. Separately, manufacturers such as WELONG have continued to appear in product overviews with compact tubing power tong configurations designed for oil industry applications. These developments suggest a market where brand visibility, product availability, and flexible access channels all play roles in competitive positioning.
The competitive landscape is evolving along several axes. Consolidation remains a possibility as larger players seek to broaden their tubular running portfolios and as customers prefer suppliers with greater financial and service resilience. At the same time, differentiation is intensifying around torque capacity, integration with automated rig systems, digital monitoring, and compliance documentation. New entrants face a challenging path unless they bring a clear technical advantage, a specialized application niche, or a compelling cost-and-service model. For incumbents, the strategic priority is to combine product performance with ecosystem value, including aftermarket support, training, certification assistance, and compatibility with emerging rig automation trends.
Future Trends and Commercial Opportunities
Over the next three to five years, one of the most important trends will be the continued integration of tubular tongs into automated and data-enabled rig environments. Equipment that supports mechanized handling, precise torque control, and real-time performance feedback will become increasingly central to operator procurement criteria. This creates opportunities for manufacturers to develop solutions that do more than deliver torque; they can provide repeatable running procedures, reduce human error, and generate operational data that supports well integrity and efficiency improvements. Companies that align product development with the trajectory of automated rig technologies are likely to gain favor with operators seeking to standardize workflows and improve safety outcomes.
A second trend will be the sustained demand for high-torque and premium-connection-compatible equipment. As well designs become more complex and operators place greater emphasis on connection reliability, tools capable of handling challenging tubulars with consistent torque application will remain in demand. This opens commercial opportunities for suppliers that can offer a broad torque range, robust material specifications, and configurations tailored to both onshore and offshore settings. It also favors companies that can demonstrate field-proven performance and provide documentation that simplifies vendor qualification processes.
A third trend involves the expanding role of flexible procurement and lifecycle support. With steel costs remaining elevated and operational budgets under pressure, customers are likely to continue exploring a mix of purchase, rental, and service-based arrangements. Suppliers that can offer transparent availability, certified maintenance pathways, and reliable reconditioning or support services will be better positioned to retain customer relationships across the equipment lifecycle. This shift presents an opportunity to build revenue streams beyond initial equipment sales, particularly through service contracts, spare parts supply, and technical support tied to compliance and safety requirements.
These trends also carry risk. Material cost volatility could compress margins if not managed through strategic sourcing or value-based pricing. Regulatory expectations may tighten or evolve, requiring ongoing updates to design, testing, and documentation practices. In addition, if automation adoption accelerates faster than anticipated in certain regions or operator segments, suppliers that remain focused only on traditional hardware may lose relevance. The businesses that navigate these uncertainties most effectively will be those that treat product performance, compliance, and customer support as interconnected competitive dimensions rather than separate functions.
Worldwide Sheet Metal Tube Lifter Market
Strategic Actions for Decision-Makers
For manufacturers, the priority should be to deepen differentiation around torque precision, compatibility with automated rig systems, and documented compliance. Expanding high-torque and premium-connection options while reinforcing quality systems and certification readiness can strengthen competitive positioning. Equally important is building a clear value proposition around lifecycle support, including maintenance, spare parts, and service networks that help customers manage total cost of ownership in an environment of elevated input prices.
For investors, the market offers exposure to a sector with steady growth linked to drilling, completion, and workover activity, but selectivity matters. Companies with diversified product lines, strong compliance credentials, and flexible commercial models are better equipped to withstand material cost pressures and shifting procurement preferences. Attention should also be paid to suppliers that are actively aligning with automation and digital monitoring trends, as these capabilities are likely to influence long-term demand patterns and customer loyalty.
For procurement teams and operators, the focus should be on total operational value rather than upfront price alone. Equipment that supports consistent torque application, integrates with positioning and control systems, and comes with clear certification and maintenance pathways can reduce rig time, improve safety, and simplify vendor management. Evaluating suppliers on the basis of field reliability, service responsiveness, and compatibility with planned rig technology upgrades can yield better outcomes over the project lifecycle. For organizations seeking more granular segmentation data, regional demand patterns, and tailored strategic recommendations, detailed market research can provide the deeper context needed to refine procurement, investment, and product planning decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Tubular Tongs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com