

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Greenhouse Harvest Trolley Market: Why 6.85% CAGR and Electrification Reshape Growth

Navigating the Global Greenhouse Harvest Trolley Market: Strategic Trajectories and Commercial Opportunities (2026–2032)
The worldwide market for greenhouse harvest trolleys has evolved from a niche horticultural accessory into a critical component of controlled-environment agriculture infrastructure. Valued at approximately $255.42 million in 2025, the market has expanded at a compound annual growth rate of 6.85 percent from 2020 through the base year, reflecting a steady shift toward mechanized, ergonomic, and scalable harvesting solutions. Projections through 2032 indicate sustained momentum, with revenue expected to cross the $400 million threshold as greenhouse operations intensify, labor dynamics tighten, and automation expectations rise across commercial horticulture. This trajectory is not merely a function of expanding greenhouse footprints; it represents a structural recalibration of how produce, ornamentals, and specialty crops are moved, sorted, and staged within high-wire and multi-tier growing systems.
Shower Trolley Market
However, the market stands at a discernible inflection point. The first challenge lies in aligning equipment capabilities with rapidly changing greenhouse architectures. Modern facilities increasingly feature elevated growing systems, wider crop spacing, and integrated climate zones that demand trolleys with adjustable working heights, higher load capacities, and seamless compatibility with pipe-rail, ground-based, and hybrid layouts. Equipment that cannot adapt to these spatial and operational variations risks premature obsolescence or limited deployment windows. The second challenge centers on operational cost and labor productivity. Harvesting remains one of the most labor-intensive phases in greenhouse production, and operators are scrutinizing every workflow bottleneck. Trolleys must now justify their capital expense by demonstrably reducing worker fatigue, minimizing crop handling time, and preserving product quality during transport. The third challenge involves compliance and standardization. As food safety expectations and workplace safety mandates tighten, equipment design must integrate sanitation-friendly surfaces, secure load anchoring, and predictable mechanical behavior in confined, high-humidity environments. These pressures are reshaping procurement criteria and forcing manufacturers to move beyond basic transport functions toward integrated workflow solutions.
Greenhouse Horticulture Market
Technology Innovation and the Shift Toward Adaptive Mobility
The most consequential driver of market change is the acceleration of trolley technology from static push platforms to adaptive, height-adjustable, and increasingly electrified systems. Growers managing tall crop structures—tomatoes, cucumbers, peppers, and climbing ornamentals—require equipment that can move vertically with the crop canopy while maintaining stability and load security. Adjustable-height scissor mechanisms, self-propelled electric drives, and modular attachment points are no longer premium features; they are becoming baseline expectations for commercial-scale operations. The integration of electric propulsion addresses two simultaneous pressures: reducing physical strain on harvesting teams and enabling smoother movement across long greenhouse aisles without the drag and friction losses associated with manual platforms. In parallel, hydraulic lift systems are being refined to provide controlled, repeatable height transitions that synchronize with crop growth cycles rather than forcing workers to adapt to fixed equipment geometries. This convergence of electric drive, hydraulic adjustability, and structural durability is expanding the practical operating envelope of harvest trolleys and making them relevant across a broader range of crop types and greenhouse configurations.
Regulatory and Safety Expectations as Design Constraints
Policy and regulatory environments are increasingly shaping procurement decisions and product development roadmaps. Equipment used in produce harvesting is expected to support sanitation protocols and minimize pathways for biological contamination, which places a premium on smooth surfaces, corrosion-resistant finishes, and designs that accommodate cleaning routines without compromising structural integrity. At the same time, worker safety considerations are influencing trolley engineering in tangible ways. Greenhouses present confined spaces, uneven load distributions, and height-related handling risks, which means mobility platforms must incorporate stable wheel bases, predictable braking behavior, and guarding suitable for routine agricultural machinery use. These requirements do not merely add compliance costs; they influence competitive differentiation. Manufacturers that design trolleys with sanitation, ergonomics, and safety integration from the outset are positioning themselves to meet procurement standards more easily, while those treating compliance as an afterthought face longer adoption cycles and greater retrofit risk.
Demand-Side Shifts: Operational Efficiency and Crop Diversification
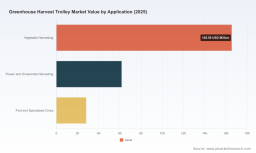
On the demand side, the market is being propelled by a combination of labor economics and crop strategy. Greenhouse operators are under continuous pressure to improve throughput per labor hour, and harvest trolleys have become a practical lever for optimizing worker movement, reducing repetitive bending and lifting, and enabling more consistent transport of harvested product from canopy level to collection points. Beyond labor productivity, crop diversification is expanding the use case set. Vegetable harvesting remains the largest application area, but flower and ornamental production, along with specialized fruit and specialty crop operations, are contributing meaningful demand for trolleys that can handle lighter loads, delicate product handling, and frequent height adjustments. As producers add high-value crops to their portfolios, they require equipment that can transition between crop types without major reconfiguration, which favors modular designs and adjustable load platforms. The result is a broader, more application-diverse buyer base that is less willing to accept single-purpose equipment and more inclined toward platforms with multi-crop flexibility.
Supply Chain Continuity and Material Durability Considerations
Supply chain and material considerations are also influencing market dynamics. Harvest trolleys operate in humid, chemically active greenhouse environments where corrosion and wear can shorten service life and inflate total cost of ownership. Accordingly, galvanized steel frames and powder-coated metal construction have become common material strategies, supporting durability and resistance to environmental degradation. This focus on material longevity intersects with procurement economics: operators increasingly evaluate trolleys not only by upfront price but by maintenance frequency, part availability, and expected service intervals. At the same time, manufacturers must navigate component sourcing for electric drives, hydraulic assemblies, and battery systems, where reliability and lead-time consistency can be as important as unit cost. These supply-side realities are rewarding producers with stable material specifications, standardized subsystems, and the ability to deliver repeatable builds across multiple production cycles.
Competitive Landscape: Differentiation Through Application Fit and System Integration
The competitive environment is shaped by a diverse set of manufacturers spanning established European horticultural equipment makers and emerging regional producers. A recurring theme across leading companies is the emphasis on application-specific engineering rather than generic transport platforms. Some manufacturers have built their positioning around pipe-rail ecosystems, offering self-propelled adjustable-height models designed for high-wire cropping and transport within standardized rail infrastructures. Others have expanded into tire-based or hybrid mobility solutions that serve greenhouses without pipe rails, recognizing that facility design varies widely and that a single mobility architecture cannot serve every operation. A further segment of the market focuses on hydraulic scissor platforms and multi-level trolleys that target crop work at height, where load capacity, lift control, and operator positioning become critical purchase criteria. This segmentation is not static; it reflects a broader competitive logic in which differentiation comes from how well a trolley matches crop type, greenhouse layout, and harvesting workflow.
Strategic positioning also differs in the degree of integration offered. Several European players combine harvesting trolleys with broader internal transport and crop-care systems, enabling buyers to align mobility equipment with existing greenhouse logistics. This system-level approach can reduce compatibility gaps and simplify procurement for operators upgrading multiple workflow components at once. Meanwhile, manufacturers in other regions have emphasized robust construction, standardized load handling, and cost-competitive designs suitable for intensive vegetable production and general horticultural logistics. The market is thus characterized by a blend of specialization and regional advantage: some firms compete on precision, adjustability, and integration, while others compete on durability, straightforward mechanics, and affordability. This duality creates room for multiple viable business models, but it also raises the bar for clarity in product messaging and fit-for-use demonstration.
Market evolution is also showing signs of both consolidation and entry. Established manufacturers are extending product lines to cover adjacent applications, such as bench movement, pallet transport, and automated movement within commercial facilities, which broadens their relevance beyond pure harvesting tasks. At the same time, new product introductions and customized delivery projects indicate that buyers are increasingly seeking tailored configurations rather than off-the-shelf uniformity. Recent activity in the sector reflects this direction: customized electric-hydraulic scissor lift harvest trolleys have been deployed with integrated safety features and electric drive components to improve harvesting efficiency and worker safety, while modular pipe-rail trolley systems enabling automated movement of benches and pallets have been introduced for commercial greenhouse facilities. These developments suggest that the competitive frontier is moving toward configurability, automation readiness, and safety-integrated design. Companies that can combine standard reliability with adaptable specifications are likely to capture a larger share of procurement budgets, especially as buyers seek equipment that can evolve with facility upgrades.
Market Structure and the Role of Concentration
Although the market remains relatively fragmented compared with larger agricultural machinery segments, concentration patterns are beginning to influence competitive behavior. A limited group of suppliers accounts for a meaningful share of revenue, which indicates that scale, repeat procurement relationships, and established installer or distributor networks still matter. At the same time, the presence of numerous regional manufacturers suggests that local service responsiveness, crop-specific familiarity, and price-to-performance ratios remain decisive in many markets. This structure creates a dual dynamic: leading suppliers can leverage brand recognition and multi-project deployments to win larger contracts, while smaller or region-focused producers can compete by aligning closely with local crop systems and facility types. The likely trajectory is not a simple race to consolidation, but a gradual stratification in which manufacturers position themselves either as broad-platform providers with integration depth or as focused specialists with strong application fit in particular crops or regions.
PW Consulting
Near-Term Trajectory: Electrification, Modularity, and Workflow Alignment
Looking ahead to the next three to five years, one of the clearest trends is the widening adoption of electric and height-adjustable trolleys as standard options rather than specialty upgrades. As greenhouse operators continue to prioritize labor efficiency and worker ergonomics, platforms that reduce manual pushing, enable canopy-level access, and support controlled lifting will likely become more common across vegetable, ornamental, and specialty crop operations. A second trend is the movement toward modular and adaptable designs that can serve multiple greenhouse layouts and crop types. Buyers are expected to favor equipment that can be reconfigured for different rail systems, load capacities, and harvesting workflows, which will reward manufacturers that offer flexible attachment points, adjustable platforms, and clear upgrade paths. A third trend involves deeper alignment between trolley selection and overall facility planning. Procurement decisions are increasingly evaluated in the context of sanitation protocols, safety requirements, and internal logistics, which means trolleys will be assessed as part of a broader workflow system rather than as isolated tools. This shift opens commercial opportunities for suppliers that can demonstrate how mobility equipment reduces handling time, supports compliance, and fits into long-term facility upgrades.
These trends also carry uncertainty. Adoption rates will depend on capital availability, the pace of greenhouse expansion in key regions, and the reliability of electric and hydraulic components under continuous commercial use. If component durability or maintenance support falls short, operators may slow deployment or revert to simpler mechanical platforms in certain applications. In addition, the performance gap between generic and application-optimized trolleys may narrow as standards rise, which could intensify competition on price, service, and customization capability. Market participants should therefore treat flexibility, service infrastructure, and configuration support as strategic assets rather than secondary considerations.
Strategic Implications for Manufacturers, Investors, and Procurement Teams
For equipment manufacturers, the priority is to sharpen application fit while preserving scalability. Product lines should clearly differentiate between pipe-rail, ground-based, and hybrid use cases, and should articulate how adjustability, drive type, and load capacity map to specific crop systems and greenhouse layouts. Manufacturers that can offer repeatable durability in humid environments, straightforward maintenance access, and configurable options without excessive customization cost will be better positioned to win repeat business and expand into broader internal transport workflows.
For investors, the market presents opportunity in companies that combine practical electrification, modular architecture, and strong regional service coverage. Investment attention should focus on whether a company can sustain component supply, demonstrate real-world reliability across crop types, and support buyers with configuration guidance rather than relying solely on product breadth. The most resilient value propositions are likely to be those that connect equipment performance to measurable operational improvements in labor use, handling efficiency, and sanitation readiness.
For procurement teams and greenhouse operators, the emphasis should be on matching trolley specifications to actual harvesting workflows rather than purchasing by generic category. Evaluation criteria should include height-adjustment range, drive and braking behavior in confined spaces, load stability for the intended crop mix, and compatibility with sanitation routines and facility layouts. Projects that clearly define crop type, aisle structure, and handling volume before procurement are more likely to select equipment that remains useful as crop plans and facility designs evolve. In that context, detailed segment data, competitive benchmarking, and configuration-level guidance can materially improve purchase decisions and reduce the risk of underutilized capital.
For detailed analysis of this topic, please visit the official page: Worldwide Greenhouse Harvest Trolley Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com