

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Polyisobutene Adhesives: Why 5.85% CAGR in Medical & Asia Pacific Matters

Strategic Trends and Commercial Opportunities in the Worldwide Polyisobutene-Based Pressure-Sensitive Adhesives Market
Market Overview and Core Challenges
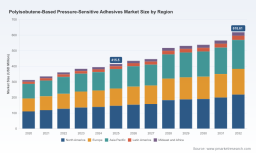
The global pressure-sensitive adhesives (PSA) market built on polyisobutene (PIB) technology has demonstrated consistent growth over the past five years, expanding from a valuation of approximately USD 312.35 million in 2020 to an estimated USD 415.5 million in 2025. Moving forward, the market is projected to reach USD 618.61 million by 2032, reflecting a compound annual growth rate of 5.85% across the forecast period from 2026 to 2032. This trajectory underscores a steady, though not explosive, expansion driven by the material's unique combination of tack, adhesion stability, and low gas permeability. The growth path reflects a market that is maturing rather than experiencing disruptive breakthroughs, with expansions concentrated in specific industrial, medical, and construction applications.
Despite the positive outlook, the industry currently faces several structural challenges that are redefining competitive dynamics. First, raw material cost volatility remains a persistent pressure point. PIB prices are intrinsically linked to isobutylene feedstock costs, which themselves fluctuate with refinery margins, crude oil prices, and C4 stream availability. Recent periods have seen PIB pricing experience notable swings, influencing margin stability for formulators and downstream manufacturers. For companies operating on thin adhesive margins, this volatility complicates long-term pricing strategies and inventory planning, forcing a more agile approach to supply chain management.
Second, regulatory and sustainability demands are reshaping formulation expectations. Environmental regulations, particularly in Europe, have introduced cost implications tied to carbon pricing mechanisms that affect naphtha cracking and PIB production. As industrial and consumer end-users increasingly prioritize low-carbon footprints and recyclable or bio-based alternatives, PIB-based adhesives face scrutiny regarding their lifecycle impact. Manufacturers must balance the proven performance of PIB with the need to meet evolving compliance standards without compromising adhesion properties or introducing prohibitive costs. This tension is especially acute for medical and automotive applications where safety and durability override cost considerations, yet even these sectors are beginning to factor in environmental compliance as a procurement criterion.
Third, the market is characterized by moderate concentration, which creates both stability and barriers. A handful of major players command significant share, and the technical barriers to formulating high-performance PIB-based PSAs remain substantial. This concentration supports reliable supply but also limits rapid disruption from smaller entrants. For new players or those looking to expand into high-value niches, the challenge lies in establishing credibility, securing consistent feedstock supply, and developing formulation expertise that meets stringent application requirements. Overcoming these hurdles requires not just capital but specialized technical knowledge and long-term customer relationships.
These challenges collectively signal a market at a crossroads. The steady growth environment provides a stable foundation, but participants who fail to address cost predictability, regulatory alignment, and technical differentiation may find their margins eroded or their relevance diminished as downstream industries evolve. The opportunities for growth lie in navigating these pressures strategically, leveraging PIB's inherent advantages while adapting to the shifting landscape of feedstock economics and sustainability expectations.
Key Drivers Shaping Market Dynamics
Technological Innovation and Formulation Breakthroughs
Advancements in polymer chemistry and formulation science continue to drive value creation in the PIB-based PSA sector. Manufacturers have increasingly focused on optimizing molecular weight distributions and blending techniques to fine-tune tack, peel strength, and shear resistance for specific application requirements. The development of compounded and blended PIB grades has enabled formulators to achieve performance characteristics that pure high or low molecular weight grades cannot deliver alone. These blended systems allow for tailored adhesion profiles, making them suitable for demanding applications in tape construction, medical device assembly, and specialized industrial bonding where consistent performance across varying substrates is critical.
Equally important is the integration of PIB with complementary polymers and additives to enhance water resistance, aging stability, and processing efficiency. Such innovation reduces the technical limitations that once restricted PIB-based adhesives to narrower application sets. As a result, formulators can now offer solutions that compete more effectively against alternative adhesive chemistries, particularly in environments where moisture exposure or temperature fluctuations would degrade conventional formulations. The ability to customize rheological properties without sacrificing the core benefits of PIB has expanded the addressable market, particularly in segments where reliability and longevity are paramount.
Synthetic Rubber-based Pressure Sensitive Market
Policy and Regulatory Environment
Regulatory frameworks are exerting a dual influence on the market, both constraining and creating opportunities. Environmental regulations targeting volatile organic compounds and encouraging lower-carbon manufacturing processes have pushed adhesive producers to reformulate products and adopt cleaner production practices. In regions with ambitious climate targets, the cost of carbon allowances directly influences the economics of feedstock production, affecting PIB pricing and, by extension, the cost structure of finished adhesives. Companies that proactively invest in energy-efficient processes, alternative feedstock pathways, or carbon mitigation strategies position themselves to manage regulatory costs more effectively than competitors who react only when compliance becomes mandatory.
At the same time, regulatory emphasis on product safety and biocompatibility has reinforced demand for high-performance adhesives in medical and healthcare applications. PIB's favorable profile regarding low toxicity and stable adhesion makes it attractive for wound care, transdermal patches, and medical device fixation. As healthcare systems globally expand access to advanced medical technologies, the requirement for reliable, compliant adhesive solutions grows in tandem. Regulatory clarity that differentiates safe, proven materials from less tested alternatives can provide a competitive advantage to established PIB formulators who can document compliance and performance across a range of medical use cases.
Pressure Sensitive Adhesive Tapes Market
Demand-Side Shifts in Key End-Use Segments
Shifts in end-user behavior and industry requirements are reshaping demand patterns across the PIB-PSA market. In the automotive and industrial sectors, the trend toward lightweighting, electric vehicle assembly, and modular construction has increased the need for adhesives that can bond dissimilar materials, withstand thermal cycling, and maintain performance over extended service life. PIB-based formulations have found relevance in these contexts due to their ability to provide consistent tack and resistance to creep, attributes that are highly valued in structural and semi-structural bonding applications. The ongoing transition in automotive manufacturing creates incremental but persistent demand for specialized adhesive solutions that meet rigorous performance and durability standards.
Simultaneously, growth in healthcare consumption and aging demographics in several major economies are driving demand for medical adhesives that are gentle on skin, resistant to moisture, and capable of secure fixation over time. Consumer preferences for convenient, non-invasive medical solutions have accelerated adoption of pressure-sensitive formats in home care and personal health devices. In addition, the packaging sector continues to demand adhesives that balance quick dispensing, clean removal, and strong bond strength, particularly as e-commerce and specialty labeling expand. These demand-side evolutions create pockets of growth that are less sensitive to broader economic cycles and more driven by sustained structural changes in healthcare delivery and industrial production.
Supply Chain and Cost Structure Considerations
The supply chain for PIB-based adhesives is influenced by the availability and pricing of isobutylene, which remains the primary feedstock for polyisobutene production. Market dynamics for C4 streams, refinery operating rates, and broader petrochemical market conditions can cause feedstock prices to fluctuate, which then propagates through to PIB pricing and final adhesive costs. Recent market observations have highlighted periods where PIB pricing experienced declines due to softening isobutylene costs and weaker crude oil benchmarks, only to later stabilize or adjust as regional supply conditions shifted. Such volatility underscores the importance of supply chain resilience and strategic sourcing for manufacturers seeking to maintain cost predictability.
Geographical factors also play a role in cost structures. Production hubs with integrated feedstock access and favorable energy costs often hold a structural advantage, while regions relying on imported feedstock or facing higher energy and carbon costs must manage additional expense layers. These disparities influence where adhesive formulators locate production capacity and how they structure their supplier relationships. Companies that secure long-term feedstock agreements, invest in regional supply chain flexibility, or develop hybrid sourcing strategies can mitigate exposure to regional price dislocations. For downstream formulators and end-users, understanding these cost drivers is essential for procurement planning and for evaluating the long-term viability of PIB-based solutions versus alternative adhesive chemistries.
Competitive Landscape and Leading Strategies
The competitive environment for PIB-based pressure-sensitive adhesives is shaped by a mix of feedstock producers, polymer specialists, and adhesive formulators who together cover the value chain from raw material to finished application. Several major companies hold recognizable positions, each leveraging distinct capabilities to capture value in different segments. BASF, for example, offers a range of Oppanol PIB grades that serve as the base polymer for formulations requiring controlled gas permeability and stable tack, positioning the company as a key supplier for formulators building high-performance adhesive systems. ExxonMobil Chemical provides Vistanex grades that are widely recognized for consistency and application versatility in industrial tapes and labels, supporting formulators who need reliable polymer inputs with predictable behavior during processing.
Alongside these feedstock and polymer-focused players, adhesive formulators such as Henkel and H.B. Fuller have carved out strong positions by developing finished PSA solutions that incorporate PIB to meet specific bonding requirements in packaging, automotive, and industrial contexts. These companies differentiate themselves through formulation expertise, application-specific testing, and the ability to deliver turnkey adhesive products that reduce the technical burden on end-users. Their competitive advantage lies not in selling bulk polymer but in translating polymer performance into reliable, application-ready adhesive systems with documented performance characteristics.
3M continues to be a notable presence, bringing extensive adhesive technology know-how and a portfolio of patented PIB-based compositions tailored for demanding medical and industrial uses. The company's strength is its ability to combine material science with application engineering, creating adhesives that meet stringent performance and safety criteria. KEMAT contributes further differentiation through its polybutene and polyisobutene ranges designed specifically to enhance tack, peel strength, and water resistance, offering formulators specialized options for industrial adhesive formulations where moisture resistance and bonding durability are critical.
In Asia, companies such as Zhejiang Cenway Materials and Sinopec's Beijing Yanshan Company play important roles by producing PIB that supports regional adhesive manufacturing. Their positioning reflects the broader trend of regional supply development, where localized production can reduce logistics costs, improve supply reliability, and respond more quickly to regional demand fluctuations. These players benefit from integrated feedstock streams and growing domestic demand, allowing them to compete on cost and availability while gradually building technical credibility with formulators.
Strategically, leading companies are pursuing differentiation along several axes. Some emphasize raw material consistency and grade specialization to secure long-term relationships with formulators who require predictable polymer performance. Others focus on downstream value addition by offering compounded or blended solutions that solve specific adhesion challenges, effectively moving closer to the end-user application. There is also a trend toward building application-specific expertise, particularly in medical, automotive, and high-performance industrial segments where certification, testing, and technical support are crucial to winning and retaining customers. Companies that invest in these capabilities create higher switching costs for customers and build defensibility beyond price competition.
PW Consulting
The market structure is gradually evolving. While concentration remains moderate, consolidation pressures exist as larger players seek to strengthen feedstock security and expand formulation portfolios. At the same time, regional suppliers continue to gain ground in local markets, taking advantage of proximity to end-users and the ability to offer customized service levels. New entrants face the hurdle of proving technical reliability and building trust in applications where failure is costly, but opportunities exist for those that can address niche performance requirements or offer cost-competitive alternatives backed by solid quality assurance. Overall, the competitive landscape rewards players that can combine feedstock advantage, formulation sophistication, and application-specific support into a coherent value proposition.
Future Trends and Commercial Opportunities
Looking ahead to the 2026 to 2032 period, the PIB-based PSA market is likely to be shaped by several interconnected trends that will create both opportunities and risks. One prominent trend is the continued optimization of blended and compounded PIB formulations to meet increasingly specific application demands. As end-users in automotive, medical, and industrial sectors push for adhesives that combine adhesion strength, environmental resistance, and ease of processing, formulators that can deliver customized grade portfolios will be well positioned. This trend favors suppliers that invest in R&D to expand their grade offerings and in technical service capabilities to support customer development cycles. Commercial opportunity lies in targeting high-value niches where performance differentiation justifies premium pricing and long-term contracts.
A second trend concerns the growing importance of sustainability and regulatory alignment in procurement decisions. While PIB-based adhesives benefit from established performance credentials, buyers are increasingly factoring in carbon intensity, lifecycle impact, and compliance with evolving environmental standards. Companies that proactively address these considerations through process improvements, feedstock efficiency, and transparent reporting can differentiate themselves and capture procurement preference in regulated or sustainability-conscious markets. The commercial angle here is not merely defensive; it is an opportunity to build brand trust and secure preferred supplier status with customers who are under pressure to meet their own environmental targets. Risk arises for players that treat regulatory compliance as a cost to be absorbed rather than a strategic capability to be developed.
Third, regional supply dynamics will likely influence competitive positioning. As demand growth continues in Asia Pacific and other regions, localized production and feedstock integration will become more valuable. Companies that can offer reliable regional supply, shorter lead times, and responsive technical support may capture market share from more distant competitors, particularly in price-sensitive segments and applications requiring rapid turnaround. The opportunity for regional players is to deepen relationships with local formulators and end-users, building loyalty through service and consistency. However, the risk is that global overcapacity or feedstock dislocations could compress margins and intensify price competition, making scale and efficiency critical defenses for larger operators.
These trends collectively point to a market where value creation is shifting from volume expansion alone to a combination of technical differentiation, supply chain reliability, and sustainability positioning. Participants that understand these vectors and align their strategies accordingly can unlock growth even in a market characterized by moderate overall expansion rates. The potential rewards are highest for those that move beyond commodity positioning and establish themselves as trusted partners in solving specific adhesive performance challenges.
Strategic Recommendations for Decision Makers
For manufacturers and formulators, the priority should be to invest in formulation flexibility and application-specific technical support. Developing a portfolio of PIB grades and compounded options that address distinct adhesion requirements allows companies to capture higher-margin opportunities and reduce exposure to commoditized competition. Building strong technical service capabilities helps secure long-term customer relationships and creates barriers for competitors who can match price but not performance or support. At the same time, manufacturers should evaluate feedstock sourcing and supply agreements to manage cost volatility, considering regional diversification and long-term contracts where feasible.
For investors, the attractive entry points lie in companies and segments where clear differentiation translates into pricing power and demand resilience. Medical and healthcare applications, specialized automotive bonding, and high-performance industrial tapes represent areas where performance requirements limit substitution and support stable margins. Due diligence should focus on feedstock security, formulation IP, regulatory preparedness, and the ability to serve demanding customer segments with proven quality. Investments that back companies with a credible roadmap for sustainability and regional supply strength are likely to be better positioned as regulatory and cost pressures intensify.
For procurement and sourcing professionals, the key is to balance cost considerations with supply reliability and technical fit. Engaging with suppliers that offer consistent grade quality, clear documentation, and responsive technical support reduces the risk of production disruptions and application failures. Long-term partnerships with formulators who can co-develop solutions for specific applications may yield better total cost outcomes than chasing short-term price advantages with less aligned suppliers. Procurement teams should also monitor feedstock market dynamics and carbon-related cost impacts to anticipate pricing shifts and adjust sourcing strategies proactively.
For all stakeholders, the value of granular market intelligence cannot be overstated. Understanding regional demand shifts, feedstock price trajectories, regulatory timelines, and competitor capability development enables more informed decisions about capacity investment, product portfolio direction, and supplier selection. Detailed segmentation data and scenario analysis provide the foundation for anticipating changes rather than reacting to them. Accessing comprehensive research and specialized advisory support offers a clearer view of where competitive advantage can be built and how to navigate the evolving landscape of PIB-based pressure-sensitive adhesives with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Polyisobutene-Based Pressure-Sensitive Adhesives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com