

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Hydrophone Market: Why Defense Spending and Fiber Optics Drive 6% Growth to 2032

Strategic Trends and Commercial Opportunities in the Worldwide Hydrophone Market
Market Landscape and Core Challenges
The global hydrophone market has demonstrated resilient growth over the past five years, evolving from a specialized underwater acoustic tool into a critical component across defense, industrial, and environmental sectors. Valued at approximately USD 185.4 million in 2020, the market expanded steadily to USD 248.5 million by 2025, reflecting a compound annual growth rate of 6.0 percent. Forward projections indicate this momentum will continue through 2032, with revenue expected to surpass USD 373.6 million. This trajectory underscores a structural shift: hydrophones are no longer confined to niche oceanographic surveys but are becoming integral to maritime domain awareness, subsea infrastructure monitoring, and next-generation defense architectures.
Behind these headline figures lies a market operating under distinct technological and regulatory tensions. Three challenges stand out as defining inflection points for the industry. First, the sector faces material science constraints. Piezoelectric ceramics, particularly PZT-based formulations, still dominate commercial production due to their proven sensitivity and reliability across varying depths and frequencies. However, environmental regulations in the EU and other jurisdictions are gradually pushing for restrictions on hazardous substances like lead in electronic components. While exemptions currently protect many defense and industrial hydrophone applications, manufacturers must prepare for potential compliance shifts that could redefine material sourcing and unit economics.
Second, the market is navigating an integration-versus-modularization paradox. On one hand, end users increasingly demand turnkey acoustic monitoring solutions that combine sensing, signal processing, and data transmission in a single deployment package. On the other hand, defense and research clients continue to require highly configurable, calibrated reference-grade instruments that can be integrated into custom towed arrays, autonomous platforms, or precision laboratory setups. Suppliers that fail to balance these competing expectations risk losing relevance in either the high-margin specialized segment or the growing volume-driven monitoring market.
Third, deployment environments are becoming more contested and complex. The proliferation of uncrewed surface vessels, autonomous underwater vehicles, and low-noise submarine operations has raised the bar for detection fidelity, real-time processing, and environmental resilience. Hydrophones must now perform reliably in shallow, noisy coastal zones as well as deep-ocean surveillance corridors, often while interfacing with AI-driven acoustic classification systems. This operational complexity is compressing product development cycles and forcing manufacturers to invest in both hardware optimization and software-adjacent capabilities.
The market also exhibits moderate concentration, with the top three players capturing a meaningful share of revenue and the top five firms controlling just over half of total market value. Such concentration suggests that established players benefit from calibration certifications, long-term defense and industrial procurement relationships, and accumulated field performance data. Yet it also hints at vulnerability: a market of this size can still accommodate targeted niche entrants, particularly those that bring material innovation, integrated digital capabilities, or cost-efficient manufacturing to specific application verticals. For decision makers, the immediate implication is clear. Growth is real, but capturing it requires navigating material compliance, balancing standardization with customization, and aligning product roadmaps with increasingly sophisticated deployment scenarios.
Key Demand Drivers
Technological Innovation and Material Evolution
The most transformative driver in the hydrophone market is the convergence of advanced piezoelectric materials, digital signal processing, and platform integration. Traditional PZT ceramics continue to anchor commercial production because they offer a reliable balance of sensitivity, bandwidth, and depth tolerance. Yet the sector is actively exploring next-generation alternatives. Single-crystal piezoelectric formulations, such as PMN-PT derivatives, are gaining attention for their superior electromechanical coupling and lower noise floors, particularly in high-intensity and precision measurement contexts. Lead-free piezoelectric options are also under development, driven by long-term regulatory anticipation and sustainability goals, though commercial readiness varies across application segments.
This material evolution is being matched by smarter acoustic architectures. Modern hydrophones are increasingly designed with integrated low-noise preamplifiers, embedded processing capabilities, and standardized digital interfaces that simplify deployment on autonomous platforms, towed arrays, and coastal monitoring buoys. The shift from raw sensing elements to intelligent acoustic nodes is reducing the integration burden for end users and enabling real-time monitoring workflows that were previously only feasible in controlled laboratory or shipboard environments. For manufacturers, this trend creates an opportunity to move up the value chain: products that combine optimized transducer performance with plug-and-play connectivity, calibration traceability, and firmware-upgradable processing are becoming more competitive than standalone sensor components.
Policy, Security, and Regulatory Environments
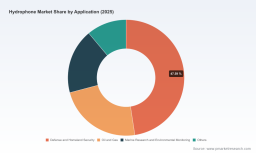
Policy and security imperatives are reshaping demand patterns across both defense and commercial applications. Heightened maritime security concerns, including the need to monitor uncrewed surface vessels, safeguard subsea infrastructure, and maintain domain awareness in contested waters, have elevated the strategic importance of reliable underwater acoustic sensing. Defense and homeland security applications remain the largest demand pool in the market, reflecting sustained investment in surveillance, antisubmarine warfare support, and port security monitoring. These programs favor hydrophones that deliver consistent calibration, high signal-to-noise performance, and compatibility with existing acoustic arrays and classification pipelines.
Mems Hydrophones Market
At the same time, environmental monitoring mandates are expanding the commercial footprint of hydrophones. Marine research institutions, environmental agencies, and industrial operators increasingly deploy passive acoustic monitoring to track marine mammal activity, assess anthropogenic noise impacts, and support environmental compliance around offshore operations. Regulatory trends are also influencing material choices indirectly; even where exemptions currently protect defense and industrial hydrophone applications from lead-restriction mandates, forward-looking procurement teams are factoring potential compliance transitions into supplier selection. Companies that can demonstrate transparent material roadmaps, calibration integrity, and environmental compliance readiness are better positioned to retain long-term contracts, particularly in multinational programs.
Demand-Side Shifts in Deployment and Operations
On the demand side, the most significant change is the move toward continuous, distributed acoustic monitoring rather than episodic survey campaigns. Offshore oil and gas operators, for example, rely on hydrophones for subsea infrastructure monitoring, leak detection support, and seismic-related acoustic tasks. As operational budgets tighten and asset integrity expectations rise, there is growing preference for monitoring solutions that can remain deployed for extended periods with low power consumption and minimal maintenance overhead. This favors designs that combine robust mechanical packaging, efficient electronics, and reliable data transmission or storage architectures.
Marine research and environmental monitoring applications are exhibiting a similar shift. Academic and governmental programs are scaling up long-term acoustic observatories, which increases demand for credible, calibrated instruments that can operate autonomously in harsh marine conditions. In parallel, defense and security end users are testing novel deployment methods, including float-equipped UAVs for rapid hydrophone placement and detection tasks. These emerging deployment models broaden the user base beyond traditional navy and research procurement channels and introduce new requirements around portability, rapid setup, and quick recovery. The commercial implication is that suppliers must think beyond unit specifications and consider total cost of ownership, deployment flexibility, and integration with the platforms operators actually use.
PW Consulting
Supply Chain and Cost Structure Dynamics
Supply chain and cost considerations are becoming more prominent as manufacturers balance performance ambitions with commercial viability. Piezoelectric materials remain a strategic input, and the broader piezoelectric market, valued in the vicinity of USD 1.66–1.9 billion during 2024–2025, reflects the scale of the upstream ecosystem that supports underwater acoustics demand. Pricing for typical piezoelectric hydrophones generally ranges from roughly USD 500 to USD 2,000 per unit, depending on frequency range, sensitivity, depth rating, and intended application. This spread means that unit economics can vary substantially across product lines, and margin profiles often depend on the degree of integration, calibration support, and application-specific engineering that accompanies the sensor.
Recent industry moves illustrate how companies are responding to these cost and supply chain pressures. Vertical integration has emerged as a practical strategy for improving quality control, reducing dependency on external transducer suppliers, and stabilizing unit economics. One notable example is the development of an in-house transducer for a smart digital hydrophone line, which was intended to strengthen cost, quality, and supply chain control while also enabling a quieter acoustic buoy offering. This kind of move signals a broader trend: companies that can bring critical components in-house or tightly coordinate with specialized material and ceramic suppliers gain more predictability in both performance and pricing. At the same time, calibration-heavy and reference-grade products continue to rely on rigorous testing and international standards, which introduces cost but also creates barriers to imitation. In a market where pricing can vary widely by specification, the winners are likely to be those that align their supply chain design with clearly differentiated value propositions rather than competing solely on unit price.
Competitive Landscape and Leading Strategies
The competitive field in the hydrophone market is shaped by a mix of established multinational players, specialized acoustic hardware manufacturers, and focused technology developers. A clear split is emerging between firms that compete as broad-spectrum acoustic solution providers and those that compete as precision specialists. Understanding this split is essential for interpreting market positioning and predicting where differentiation will matter most.
Large, diversified marine and acoustic companies compete on portfolio breadth, calibration credibility, and the ability to serve defense, oceanography, and industrial customers from a single supply base. These players typically offer comprehensive ranges of hydrophones and transducers, including precision reference instruments calibrated to international standards. Their advantage lies in long procurement relationships, repeatable quality assurance, and the capacity to support complex programs that require multiple acoustic components and integration support. For customers running multi-year surveillance, research, or industrial monitoring programs, this breadth reduces sourcing complexity and provides a single point of accountability for performance and calibration traceability.
Specialist manufacturers, by contrast, often compete on architecture, intelligents, and application-specific optimization. Some focus on smart digital hydrophones with embedded processing for real-time monitoring, combining acoustic sensing with on-device analytics to simplify downstream data workflows. Others concentrate on wide-band omnidirectional designs with low-noise preamplifiers and towed array hardware for maritime domain awareness and surveillance. A further group builds high-fidelity piezoelectric instruments aimed at precise underwater sound measurement, calibration, and controlled research environments. These specialists often win on performance transparency, niche bandwidth or sensitivity advantages, and the ability to tailor products to specific monitoring or characterization tasks.
A third competitive vector is emerging around material and transducer innovation. One notable recent development in this space is the unveiling of a submarine hydrophone sensor built on advanced piezoelectric single crystal technology, positioning it as a step forward in underwater acoustic sensing performance. Separately, long-established acoustic brands have used product showcases and anniversary milestones to signal continued investment in hydrophone and transducer advancements, reinforcing their commitment to next-generation hardware. These moves matter because they show that competition is no longer limited to mechanical robustness or baseline sensitivity; it increasingly turns on material-level gains, digital integration, and the ability to translate laboratory-grade improvements into deployable systems.
Worldwide Low Frequency Geophone Market
The landscape is also being shaped by new deployment concepts and vertical integration strategies. A recent test of a float-equipped UAV for hydrophone deployment highlights how sensing is being extended into faster, more flexible platforms for detecting uncrewed surface vessels and submarines. This kind of operational experimentation expands the relevance of hydrophones beyond fixed arrays and shipboard systems, and it encourages suppliers to think about rapid deployment, recoverable designs, and compatibility with autonomous or semi-autonomous carriers. On the manufacturing side, companies that have brought transducer production closer to their smart hydrophone lines are using that control to improve cost structure, quality consistency, and supply chain resilience. This combination of in-house capability and platform-aware design is becoming a meaningful differentiator in a market where integration complexity can otherwise erode end-user value.
Looking ahead, the competitive structure appears likely to evolve along two paths simultaneously. Consolidation may continue among larger acoustic and marine technology groups seeking to broaden their underwater sensing portfolios and capture cross-program demand. At the same time, fragmentation will persist at the edges, where niche entrants and research-driven developers can compete on specific materials, digital monitoring capabilities, or regional deployment expertise. The most resilient players will be those that can articulate a clear strategic lane: either broad-platform reliability with strong calibration and program support, or focused innovation in smart monitoring, advanced materials, or specialized deployment configurations. For buyers and investors, the key question is not simply who is largest, but which companies have the most credible roadmap for aligning hardware performance, integration ease, and supply chain control with the applications that will drive growth over the next several years.
Future Trends and Commercial Opportunities
The next three to five years are likely to be defined by three interconnected trends, each carrying distinct commercial implications. The first is the steady maturation of intelligent, integrated acoustic monitoring. Hydrophones will increasingly be deployed as part of connected sensing architectures rather than as isolated measurement devices. This trend favors products that combine robust transducer performance with low-power electronics, embedded processing, and standardized data interfaces. Commercially, it opens opportunities for suppliers that can offer repeatable monitoring packages for environmental observatories, subsea infrastructure, and coastal security networks, where deployment simplicity and data usability are as important as raw acoustic sensitivity.
The second trend is the gradual influence of material science and regulatory pressure on product roadmaps. While current exemptions preserve the role of established piezoelectric formulations in many defense and industrial applications, the direction of travel points toward greater attention to lead-free alternatives, single-crystal performance gains, and improved noise characteristics. Companies that invest early in material validation, calibration compatibility, and transparent compliance planning will be better placed to capture programs with long procurement horizons. For investors and manufacturers, this creates a window to distinguish between products that are merely adequate today and those that are designed to remain viable as material and regulatory expectations evolve.
The third trend is the expansion of deployment flexibility across autonomous and rapidly deployable platforms. Testing concepts such as float-equipped UAVs for hydrophone placement indicate that users are looking for faster, more adaptable ways to position acoustic sensors for detection and monitoring tasks. This broadens the operational envelope for hydrophones and encourages designs that are recoverable, portable, and compatible with non-traditional carriers. The commercial opportunity lies in building sensor systems that can move seamlessly between fixed observatory use, shipboard arrays, and short-duration autonomous deployments without sacrificing calibration integrity or environmental durability.
These trends are not without risk. Material transitions can raise costs and complicate qualification; integrated digital features can increase complexity and field-support demands; and rapid deployment concepts can surface durability and calibration drift challenges that were less critical in controlled, ship-based operations. Moreover, market growth at a 6.0 percent compound rate over the forecast period is encouraging, but it does not guarantee uniform expansion across all applications and regions. Demand may accelerate in security-driven and monitoring-heavy segments while remaining more measured in others. Decision makers should therefore treat the forecast as a directional signal rather than a uniform tailwind, and prioritize strategies that are robust across multiple plausible deployment futures.
Actionable Guidance for Decision Makers
Manufacturers and product leaders should use the current market window to align roadmaps with the twin pressures of integration and material evolution. That means evaluating whether to expand smart, digitally enabled hydrophone offerings for continuous monitoring, while simultaneously preparing alternative material pathways and strengthening calibration and quality assurance for reference-grade lines. Companies that can clearly separate their value propositions by application and deployment model are more likely to protect margins than those competing on specification alone.
Investors should focus on organizations that demonstrate a credible combination of differentiated technology and operational discipline. Indicators to weigh include in-house transducer or material capabilities, demonstrated real-time monitoring products, calibration and standards competence, and evidence of platform-aware deployment thinking. Given moderate market concentration, there is room for targeted growth plays, but durability will depend on whether a company can convert technical advances into repeatable programs and reliable supply chains.
Procurement and end-user teams should prioritize total deployment value over unit price when selecting hydrophone solutions. Key evaluation points include calibration traceability, environmental durability, power and data architecture, integration burden with existing arrays or platforms, and the supplier's ability to support future material or compliance transitions. Long-duration monitoring and security-driven deployments are especially sensitive to field reliability and data usability, so supplier roadmaps and support capabilities deserve as much attention as initial specifications.
For leaders who need to move from directional understanding to detailed planning, the full segmentation data, regional dynamics, and company-level benchmarking become critical. A complete research report can provide the granular breakdowns and customized scenario analysis needed to support procurement strategy, product portfolio decisions, and investment prioritization with greater precision.
For detailed analysis of this topic, please visit the official page: Worldwide Hydrophone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com