

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Aldehyde Free Disinfectants Market: Why 6.42% CAGR Changes Everything

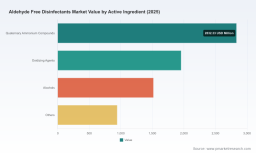
Navigating the Aldehyde-Free Disinfectants Market: Strategic Shifts and Commercial Opportunities Through 2032
1. Market Context and Core Challenges
The global market for aldehyde-free disinfectants has entered a phase of steady, structurally supported expansion. From a base of approximately $5.35 billion in 2020, the sector climbed to an estimated $7.25 billion by 2025, reflecting a compound annual growth rate of 6.42% that is projected to carry the market toward $11.2 billion by 2032. This trajectory is not a temporary pandemic rebound, but rather the result of a durable pivot in hygiene standards, infection-prevention protocols, and formulation chemistry. Aldehyde-based chemistries once dominated high-level disinfection due to their broad-spectrum efficacy, yet their neurological and respiratory hazards, material degradation risks, and patient sensitivity concerns have steadily eroded their commercial viability across healthcare, food processing, and institutional environments.
Worldwide Aerosol Disinfectants Market
Three structural tensions define the current inflection point. First, the regulatory approval pipeline is tightening around safety thresholds while simultaneously accelerating for novel actives. Environmental and health agencies are demanding faster degradation profiles, lower occupational exposure limits, and clearer residue management, which compresses the window for legacy formulations to remain compliant without reformulating. Second, formulation performance remains a balancing act. Removing aldehydes often requires re-engineering efficacy claims, contact times, and material compatibility matrices. Products that excel on stainless steel or non-porous surfaces may underperform on sensitive polymers, delicate medical instrumentation, or porous food-contact surfaces, forcing manufacturers to navigate a fragmented performance landscape. Third, procurement behavior has shifted from crisis-driven bulk purchasing to value-based, lifecycle cost evaluation. Buyers increasingly weigh recurring safety training costs, ventilation requirements, staff turnover linked to irritant exposure, and surface replacement cycles alongside unit price. This moves cost conversations upstream and rewards suppliers who can demonstrate total cost of ownership rather than lowest sticker price.
2. Key Demand Drivers
Technological Innovation and Active Ingredient Evolution
Formulation science is the primary engine of market expansion. The displacement of glutaraldehyde and ortho-phthalaldehyde has accelerated the adoption of quaternary ammonium compounds, oxidizing agents, alcohols, and next-generation酸-based platforms. These alternatives deliver cleaner safety profiles, faster surface compatibility, and easier waste handling. Accelerated hydrogen peroxide systems and citric acid-derived chemistries have gained traction where material preservation and low-toxicity requirements intersect. Importantly, the latest active ingredient approvals demonstrate that innovation is moving beyond marginal tweaks to entirely new mechanism classes. In early 2025, a dual-component system built on glycerol formate secured registration as the first new disinfectant active ingredient approved by the U.S. EPA in nearly five years, with specific utility against resilient pathogens such as Clostridioides difficile in medical institutions. This milestone signals a regulatory pathway that is increasingly receptive to differentiated, aldehyde-free mechanisms when clinical and environmental data justify the claims.
Parallel to active ingredient advances, delivery formats and application technologies are reshaping value creation. Concentrated formulations, pre-mixed ready-to-use wipes, automated dispensing units, and compatibility-tested surface protocols reduce variability in the field and lower the risk of under-dosing or surface damage. Companies that integrate formulation chemistry with application guidance, training modules, and surface-compatibility mapping capture a premium that transcends commodity pricing.
Regulatory and Policy Environment
Policy dynamics are acting as both a gatekeeper and a catalyst. In 2025, the U.S. EPA processed 178 disinfectant registrations, a near four-fold increase compared with the prior year, with continued emphasis on quaternary ammonium compounds and new actives tailored for aldehyde-free formulations. This surge reflects not only heightened institutional focus on infection prevention, but also an administrative priority to expand the pool of validated, lower-hazard options. Simultaneously, agencies maintain and periodically refresh lists of registered products with efficacy claims against pathogens including SARS-CoV-2, ensuring that label claims, dilution protocols, and contact times remain aligned with evolving scientific standards.
For market participants, the regulatory environment creates a dual imperative. Compliance is no longer a static checkbox; it is a moving target that rewards early engagement with registration dossiers, transparent toxicological data, and rapid label updates. Suppliers that can navigate multi-jurisdictional requirements and maintain active registrations across changing criteria secure procurement access that is difficult for slower competitors to replicate.
Demand-Side Shifts in Buyer Behavior
End-user expectations have fundamentally changed. Hospitals and healthcare providers now prioritize disinfectants that protect clinical staff, preserve instrument lifecycles, and minimize patient exposure risks. The clinical advisory context around certain high-level disinfectants has reinforced caution: for instance, ortho-phthalaldehyde has been associated with anaphylaxis-like reactions in patients undergoing repeated cystoscopy, necessitating thorough rinsing and avoidance in specific high-risk populations. Such guidance has accelerated preference for aldehyde-free alternatives in settings where repeated exposure or sensitive patient cohorts are unavoidable. Pharmaceutical and biotechnology companies require validated, residue-controlled chemistries that do not compromise sterile manufacturing environments, while food and beverage operations demand formulations that meet stringent food-contact and material-safety requirements without compromising throughput. Commercial and industrial buyers increasingly align procurement with sustainability targets, favoring lower-toxicity chemistries that simplify wastewater handling and reduce worker protection burdens.
Supply Chain and Cost Structure Dynamics
Raw material availability and formulation architecture are redefining cost structures. Because aldehyde-free disinfectants frequently rely on quaternary ammonium compounds, accelerated hydrogen peroxide, or citric acid-based technologies, producers are shifting toward ingredient portfolios that offer improved material compatibility and lower toxicity profiles relative to traditional aldehydes. This transition influences not only procurement costs but also storage, transportation, and handling requirements. Formulations with safer handling characteristics can reduce facility-level ventilation upgrades, personal protective equipment consumption, and wastewater treatment burdens, creating downstream savings that alter total cost comparisons. At the same time, concentration formats and centralized mixing models help manufacturers manage freight intensity and shelf-life constraints, while localized production footprints mitigate regional supply disruptions and provide faster response times for institutional clients.
3. Competitive Landscape and Leading Strategies
The market remains moderately concentrated, with the top three players accounting for roughly 31.4% of revenue and the top five reaching approximately 42.85%. This structure indicates room for both scaled incumbents and specialized challengers, particularly where formulation differentiation, application expertise, or regional service networks create defensible positioning. A cross-section of leading organizations illustrates how strategy diverges across segments and geographies.
Ecolab has built its positioning around a broad spectrum of concentrated cleaners and aldehyde-free disinfectants targeting environmental hygiene across healthcare, institutional, and food-service settings. Its scale advantage supports integrated hygiene programs that combine product supply with monitoring, training, and compliance documentation. Reckitt Benckiser leverages consumer and institutional brand equity, with surface disinfectant portfolios that include aldehyde-free formulations under familiar labels such as Lysol, directed at infection prevention in healthcare and institutional contexts. STERIS focuses on infection prevention and decontamination solutions, including aldehyde-free disinfectants tailored to healthcare facilities and medical device reprocessing, where validation and reprocessing workflows are central to buyer decisions. 3M contributes EPA-registered aldehyde-free surface disinfectants and cleaners spanning healthcare, industrial, and institutional applications, drawing on a legacy of material-science engineering and broad distribution. The Clorox Company maintains a portfolio of surface disinfectants with hospital-grade and institutional aldehyde-free options, emphasizing brand trust and high-visibility procurement channels. Diversey delivers cleaning and hygiene solutions, including aldehyde-free disinfectants for healthcare and institutional facilities, often integrated with service-oriented hygiene programs. GOJO Industries, known for its PURELL brand, has expanded into hospital-grade surface disinfectants, many of which are aldehyde-free, quat-free, and low-toxicity, appealing to organizations seeking reduced chemical exposure. Paul Hartmann manufactures products such as Bomix Plus and other aldehyde-free instrument and surface disinfectants for medical and healthcare use, aligning closely with European clinical procurement standards. B. Braun supplies aldehyde-free surface disinfectant concentrates, including variants such as Hexaquart pure and Hexaquart XL, targeting hospital and medical environments with an emphasis on compatibility and controlled dosing. Virox Technologies specializes in accelerated hydrogen peroxide-based aldehyde-free disinfectants, with a focus on infection control in healthcare settings.
Recent milestones highlight how innovation and regional execution reinforce competitive advantage. In early 2025, Ecolab registered a dual-component system using glycerol formate, the first new disinfectant active ingredient approved by the EPA in nearly five years, aimed at high-risk pathogens such as Clostridioides difficile in medical institutions. This move underscores a strategy of securing differentiated active positions ahead of competitors and aligning with pathogen-specific procurement requirements. In April 2025, Virox Technologies launched its first products powered by patented Citr-IQ technology, delivering safe, effective, and sustainable aldehyde-free disinfectants in Canada. This launch illustrates a targeted approach to regional market entry, leveraging a distinct active mechanism and sustainability narrative to gain footing in a regulated healthcare environment.
The competitive landscape is evolving on three axes. Consolidation continues among players pursuing integrated hygiene platforms, where product sales are bundled with monitoring, training, and compliance support to reduce churn and expand wallet share. At the same time, segmentation is intensifying: suppliers are narrowing their focus to high-value sub-segments such as medical device reprocessing, food-contact-safe disinfection, or low-toxicity institutional cleaning, where performance claims and handling profiles matter more than broad coverage. New entrants and regional specialists are gaining traction by combining novel actives, application-specific validation, and agile registration strategies, particularly in markets where procurement is shifting toward total cost of ownership and safer handling requirements. The result is a market in which scale provides distribution and program integration benefits, while differentiation in active chemistry, evidence packages, and service delivery increasingly determines win rates in competitive bids.
4. Forward Outlook: Trends and Commercial Implications
Over the next three to five years, the most consequential trend will be the continued broadening of the active ingredient toolbox. As registration pipelines accommodate new chemistries and buyers demand safer handling, the market will move further away from aldehyde reliance toward platforms that balance efficacy, material compatibility, and toxicity reduction. Products that can demonstrate pathogen-specific performance with acceptable contact times and minimal substrate damage will capture preference in healthcare, pharmaceutical, and food-processing procurement. This trend favors manufacturers that invest in registration-ready dossiers, compatibility testing, and real-world efficacy documentation rather than relying on generic claims.
A second trend is the shift from product transactions to outcome-based hygiene partnerships. Procurement teams are increasingly evaluating disinfectant programs through the lens of staff safety, training burden, surface preservation, and regulatory audit readiness. Suppliers that integrate dosing control, application guidance, surface-compatibility mapping, and documentation support will differentiate themselves in bids and renewals. The commercial opportunity lies in bundling formulation strength with operational reliability, creating recurring revenue streams that are less vulnerable to spot-price competition.
A third trend is regional asymmetry in adoption speed and regulatory intensity. North America and Europe will continue to lead in volume and registration velocity, but Asia-Pacific and Middle East and Africa markets will expand as healthcare infrastructure investment, food-safety modernization, and institutional hygiene standards rise. Localized production, region-specific registration strategies, and partnerships with local distributors will determine how quickly global players and regional specialists capture share. Potential risks include regulatory recalibration that could slow certain registrations, raw material price volatility affecting margin structures, and over-subscription of similar active platforms leading to commoditization in undifferentiated categories. Firms that anticipate these pressures by diversifying active portfolios, securing multiple supply routes, and maintaining agile label and registration processes will navigate uncertainty more effectively.
Water Tank Disinfectant Market
5. Actionable Recommendations for Decision-Makers
- For manufacturers and formulators: Prioritize differentiated active platforms and registration-ready evidence packages. Invest in contact-time optimization, surface-compatibility data, and low-toxicity positioning that can be translated into procurement value. Develop concentrated and ready-to-use formats that reduce handling risk and align with institutional training and compliance workflows.
- For investors and portfolio strategists: Evaluate companies on the strength of their registration pipelines, active-ingredient differentiation, and ability to bundle products with service and compliance support. Favor players with validated regional execution in growth markets and diversified supply chains that can withstand raw material volatility. Monitor shifts in procurement criteria toward total cost of ownership rather than unit price.
- For procurement and operations leaders: Move evaluation criteria beyond sticker price to include staff safety, ventilation and PPE burden, surface preservation, and documentation reliability. Request compatibility data, efficacy claims aligned to target pathogens, and evidence of registration currency. Prefer programs that reduce training variability and provide clear residue and rinsing protocols, particularly in sensitive clinical or food-contact environments.
The commercial landscape for aldehyde-free disinfectants is being reshaped by active-ingredient innovation, an accelerating regulatory environment, and procurement behavior that increasingly rewards safety, compatibility, and operational reliability. Organizations that align product strategy with these structural shifts will secure stronger positioning in a growing market. For decision-makers seeking granular segmentation, regional breakdowns, pricing dynamics, and customized scenario planning, the full PW Consulting market report provides the detailed data and tailored recommendations needed to translate these trends into concrete investment and commercial decisions.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Aldehyde Free Disinfectants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com