

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Luggage Storage Locker Market: Why 5.66% CAGR Changes Everything

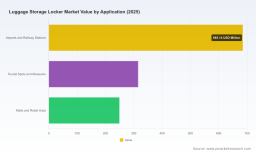
Strategic Trends and Commercial Opportunities in the Worldwide Luggage Storage Locker Market
Market Overview and Core Challenges
The global luggage storage locker market has transitioned from a niche hospitality amenity to a structured infrastructure segment within the broader travel and urban mobility ecosystem. Valued at approximately USD 1.11 billion in 2023 and reaching USD 1.25 billion in 2025, the market has demonstrated steady expansion over the 2020–2025 period, with historical revenues climbing from around USD 890 million at the start of the decade. Projections for the 2026–2032 forecast window point to a compound annual growth rate of 5.66 percent, indicating that the segment will surpass USD 1.8 billion by the end of the period. This trajectory reflects more than incremental demand growth; it signals a structural shift in how travelers, transit operators, and commercial property managers approach secure, on-demand storage.
Despite this momentum, the industry sits at a critical inflection point shaped by three interconnected challenges. First, the transition from traditional mechanical units to smart, connected locker systems is accelerating, but the capital intensity of hardware upgrades, software integration, and ongoing maintenance creates a barrier for many operators who must balance upfront investment against uncertain utilization rates. Second, fragmented regulatory expectations around data handling, payment security, and unattended access are raising compliance costs, particularly for providers deploying across multiple jurisdictions where privacy and transaction-processing standards differ materially. Third, the market remains relatively dispersed, with no single player commanding dominant share, which intensifies competitive pressure on pricing, service reliability, and differentiated features while leaving room for consolidation and strategic alliances.
Supermarket Lockers Market
A further tension lies in the mismatch between supply deployment and demand clustering. Locker installations are expanding beyond airports and major rail hubs into tourist districts, museums, shopping centers, and corporate environments, yet utilization patterns remain highly location-dependent. Operators that overbuild in low-traffic zones face underused assets, while demand-dense areas encounter capacity constraints during peak travel seasons. Resolving this imbalance requires more refined site selection, dynamic capacity management, and deeper integration with downstream services such as package delivery, concierge platforms, and transit apps. The companies that navigate these challenges effectively will be positioned to convert locker networks from static hardware deployments into flexible, revenue-generating storage utilities.
Key Drivers Shaping Market Evolution
Technology innovation is the most visible force reshaping the luggage storage locker landscape. Smart and electronic locker systems now represent the larger portion of market revenue, reflecting a broader shift toward touchscreen interfaces, mobile payment acceptance, remote monitoring, and cloud-based fleet management. These capabilities reduce reliance on staffed counters, enable 24/7 unattended operation, and allow operators to adjust pricing, access windows, and capacity allocation in response to real-time demand. On the ground, this evolution is evident in partnerships that repurpose existing smart locker networks for traveler storage. Quadient’s recent collaborations have activated thousands of Parcel Pending smart lockers across major UK cities, integrating luggage storage into multi-service networks and extending the model into Europe and Japan. Similarly, KDDI’s launch of a luggage storage service at flagship retail locations in Japan demonstrates how telecom and retail ecosystems are leveraging smart locker infrastructure to capture inbound tourism demand.
Policy and regulatory dynamics are simultaneously raising the stakes for operators. Smart locker systems that collect user data, process payments, or maintain access logs must navigate a layered compliance environment. In the United States, providers operating in California face requirements under the California Consumer Privacy Act for data processing and protection. In Europe, deployments must align with GDPR expectations, including encryption and secure cloud storage for access logs and user credentials. Payment-enabled lockers add another layer, requiring PCI-DSS compliance for secure transaction processing and network controls. Rather than acting solely as constraints, these standards are becoming differentiators: operators with mature compliance frameworks can enter regulated transit hubs, municipal partnerships, and premium commercial sites more confidently than competitors still treating security and privacy as afterthoughts.
Demand-side behavior is shifting in ways that favor flexible storage models. Travel patterns have become more fragmented, with shorter layovers, multi-city itineraries, and increased reliance on public transit in dense urban centers. Tourists and business travelers increasingly expect on-demand storage that does not require fixed counter hours or long check-in processes. At the same time, commercial property operators and retailers are exploring storage as a value-added service that can increase dwell time, support queue management, and enhance the perceived convenience of a venue. The labor cost environment reinforces this direction: self-service smart locker deployments reduce staffing dependencies by enabling unattended use and automated rental management, which is particularly attractive in locations where labor availability or cost structures make staffed kiosks impractical.
Supply chain and cost structures are also influencing market behavior. Manufacturers are balancing the durability and simplicity of mechanical and manual lockers with the functionality of electronic systems, often offering vandal-resistant variants and modular designs that can be adapted to different site conditions. For operators, this modularity matters because it affects deployment speed, maintenance exposure, and total cost of ownership. Companies that can standardize hardware components while preserving software flexibility are better positioned to scale across airports, railway stations, tourist spots, museums, and retail hubs without customizing every installation from scratch.
Locker Locks Market
Competitive Landscape and Leading Strategies
The competitive field is defined by a mix of specialized locker manufacturers, broader security and access-control providers, and smart locker platforms that increasingly blur the line between storage hardware and service ecosystems. LockTec GmbH has carved out a position around electronic locker systems designed for secure 24/7 luggage and valuables storage in transit and retail environments, with touchscreen payment, modular design, and a vandalism-resistant mechanical variant. ASSA ABLOY brings a broader access-control heritage into the space through electronic and smart locker solutions, adapting platforms such as Luxer One and SMARTair i-locker for secure storage in transportation and commercial settings. American Locker focuses on intelligent keyless lockers available in multiple sizes, with credit card acceptance, laptop charging, and custom configurations for public and private sector use. Vecos emphasizes IoT-enabled locker systems with cloud-based management for flexible storage, including on-demand luggage and asset storage configurations in workplaces and public venues.
Regional depth also matters. Godrej & Boyce maintains a strong presence in airports, railways, and institutional storage across Asia, offering high-security mechanical and electronic lockers that align with large-scale transit and public-sector procurement. Quadient illustrates a different strategic path: rather than positioning solely as a locker manufacturer, it has expanded its Parcel Pending smart locker networks into luggage storage through partnerships, enabling secure 24/7 access across UK and international locations. DeBourgh Manufacturing, Salsbury Industries, Alpha Locker Systems, Locker & Lock, and Vlocker round out the landscape with offerings that span durable commercial lockers, customizable modular solutions, and smart systems with IoT and cloud platforms aimed at user-friendly storage experiences.
The strategic positioning that separates leaders from followers usually comes down to three choices. The first is integration depth: whether a company sells hardware, provides managed storage services, or both. Providers that can combine reliable hardware with software-driven access control, payment processing, and remote management are better equipped to serve sites where unattended operation and data security are non-negotiable. The second is channel strategy: whether growth comes from direct transit and municipal contracts, partnerships with hospitality and retail platforms, or crowd-sourced distribution models that place lockers in high-footfall locations without heavy real estate commitments. The third is modularity and localization: the ability to adapt locker configurations to different climates, vandalism risks, language interfaces, payment methods, and compliance regimes without redesigning the core product.
Market structure is evolving along multiple axes. Consolidation pressure is building as larger access-control and smart-locker players absorb narrower storage specialists or partner with service networks to expand reach. At the same time, differentiation is increasing because not all deployments are equivalent: an airport system, a museum installation, and a retail-hub locker bank have different usage cycles, security expectations, and monetization models. New entrants are likely to keep appearing where software, partnerships, or site access create an advantage, but the most durable competitors will be those that can operate across regions while maintaining compliance, uptime, and customer support at scale. The result is a landscape that rewards both specialization and strategic collaboration.
Future Trends and Strategic Outlook
Over the next three to five years, the luggage storage locker market is likely to be shaped by three interrelated trends. The first is the continued migration toward smart, connected locker networks that function less as isolated hardware and more as part of integrated urban and transit services. As cloud management, remote diagnostics, and automated access become baseline expectations, value will shift toward providers that can orchestrate multi-site fleets, optimize utilization, and connect storage access to broader traveler or customer journeys. This creates commercial opportunities for operators that can bundle storage with related services, such as parcel handling, concierge support, or transit-friendly access.
The second trend is the growing importance of compliance and security as competitive differentiators. As deployments expand into more jurisdictions and more sensitive locations, operators that can demonstrate robust data protection, encrypted access logs, secure cloud storage, and PCI-DSS-aligned payment processing will face fewer barriers to entry in premium transit, municipal, and commercial contracts. This also implies that smaller players without mature security and privacy frameworks may find themselves constrained to less regulated or lower-margin segments.
The third trend is locating pressure and utilization intelligence. Demand will remain concentrated in airports, railway stations, tourist spots, museums, malls, and retail hubs, but the most successful operators will be those that treat site selection as a data discipline rather than a guesswork exercise. Predictive utilization modeling, seasonal capacity planning, and partnership-driven placement can reduce the risk of underused assets and improve unit economics. A related opportunity lies in labor optimization: as self-service smart lockers reduce staffing needs for unattended operation and automated rental management, operators can redirect human resources toward customer support, maintenance quality, and higher-value on-site services.
Potential risks should not be overlooked. Regulatory fragmentation could slow cross-border expansion if privacy, payment, and access requirements diverge further across regions. Hardware durability and vandalism resistance remain practical concerns in high-traffic public locations, and software downtime or payment failures can quickly damage trust in unattended systems. Overbuilding in low-utilization sites remains a financial hazard, especially where deployment decisions are driven by expansion targets rather than demand evidence. Companies that treat these risks as design and governance issues—rather than isolated operational problems—will be better prepared to sustain growth.
Actionable Recommendations for Decision-Makers
For locker manufacturers and hardware suppliers, the priority is to align product roadmaps with the operational realities of unattended, multi-site deployments. This means investing in modular designs, vandal-resistant construction, reliable payment and access interfaces, and software platforms that support remote monitoring and fleet management. Differentiation will increasingly come from how easily a system can be integrated into existing transit, retail, or hospitality environments without demanding heavy customization at every site.
PW Consulting
For investors and strategic acquirers, the attractive thesis lies in platforms that combine hardware credibility with service-oriented ecosystems. Companies that can demonstrate recurring utilization, scalable compliance capabilities, and partnership channels into airports, railway stations, tourist locations, and retail hubs are better positioned to capture the steady growth expected through the end of the decade. Due diligence should focus not only on unit sales but on deployment economics, uptime performance, data-security maturity, and the durability of channel relationships.
For procurement teams and venue operators evaluating storage solutions, the decision should start with use-case clarity. Airports, railway stations, museums, malls, and retail environments have different traffic patterns, security expectations, and customer experience goals, so the right locker configuration depends on more than capacity alone. Key evaluation criteria should include unattended availability, integration with payment and access systems, compliance posture across relevant jurisdictions, maintenance responsiveness, and the ability to scale or reconfigure as demand changes. Exploring the full segmentation and deployment data behind these trends can help narrow the choice between mechanical, electronic, and smart locker options for each site. A detailed market report can provide the deeper regional breakdowns, application-specific sizing, and company-level benchmarks needed to turn these strategic directions into concrete procurement or investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Luggage Storage Locker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com