

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Car Video Monitors Market: Why 7.45% CAGR Reshapes Growth Through 2032

Worldwide Car Video Monitors Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The global car video monitors market has entered a phase of sustained expansion, driven by the convergence of passenger entertainment expectations, advanced driver-assistance requirements, and vehicle electrification. From 2020 to 2025, revenue climbed from approximately USD 712 million to over USD 1,010 million, establishing a consistent upward trajectory that extends through the 2026–2032 forecast horizon. Compounding annual growth of roughly 7.45 percent positions the sector to approach USD 1,670 million by 2032. This growth is not merely linear; it reflects a structural shift in how vehicles are designed, sold, and experienced. Passengers increasingly view in-cabin video capabilities as standard amenities rather than premium add-ons, while manufacturers leverage displays to differentiate cabin experiences and support digital service ecosystems.
Despite the favorable macroeconomic and demand backdrop, the industry is navigating several inflection points. First, regulatory fragmentation around connected vehicle components is reshaping sourcing strategies. Recent guidance from the U.S. Department of Commerce targeting information and communications technology transactions involving certain foreign entities has introduced compliance complexity, prompting automakers and Tier-1 suppliers to reassess supply chain dependencies and certification pathways. This is particularly relevant for systems that combine video monitoring with connectivity, telematics, and cloud-linked entertainment services.
Second, material and component availability is tightening. Export controls on rare earth materials and associated processing equipment, alongside updates to critical minerals definitions that now include silicon used in semiconductor components for displays, are adding cost volatility and lead-time uncertainty. These dynamics affect both entry-level LCD/TFT panels and premium OLED modules, forcing designers to balance performance targets with supply resilience.
Driving Recorder (Car Dashcam) Market
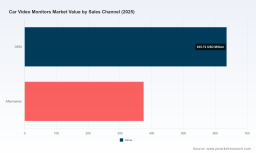
Third, the market is split between integrated OEM deployments and aftermarket installations, each with distinct economics and risk profiles. OEM channels benefit from scale, brand alignment, and long validation cycles, while aftermarket channels offer faster time-to-market and greater flexibility in feature packaging. Navigating both channels requires distinct go-to-market models, pricing architectures, and partner ecosystems. The interplay between these channels, combined with regulation and material constraints, defines the current competitive environment and separates companies that can orchestrate cross-functional capabilities from those that remain siloed.
TV & Monitor Mounts Market
Key Demand and Supply Drivers
Technological innovation remains the most visible driver of market change. Display form factors have expanded beyond conventional rectangular panels to include round, foldable, rollable, and transparent designs, enabling manufacturers to integrate video monitors into headrests, roofs, dashboards, and consoles without compromising interior aesthetics. Advanced automotive displays now support higher brightness, wider viewing angles, and improved thermal management, which are prerequisites for rear seat entertainment (RSE) systems that must function under varied cabin conditions. In parallel, interactive and mixed-reality capabilities are emerging as differentiators. For example, recent demonstrations have showcased XR-aware rear seat interfaces powered by on-device computing, allowing passengers to engage with video content and ambient cockpit functions through more immersive, context-aware experiences. These advances are not cosmetic; they create new usage scenarios that increase perceived value and support premium pricing tiers.
Policy and regulatory environments are shaping both opportunities and constraints. Safety-oriented regulations continue to influence display placement, brightness limits, and distraction mitigation, especially for driver-facing and center-console interfaces. At the same time, connected-vehicle security rules are accelerating decisions about component provenance, software certification, and data handling. The net effect is a market where compliance capability has become a competitive asset. Suppliers that can document traceability, maintain approved sourcing lists, and navigate regional requirements are better positioned to secure long-term OEM contracts, while those with concentrated dependencies face higher scrutiny and potential delays.
Demand-side behavior is evolving across both consumer and enterprise segments. In premium and mid-tier passenger vehicles, rear seat video has transitioned from a luxury feature to a family and ride-hailing expectation, particularly in markets where long commutes and vehicle-based leisure time are common. Fleet operators and mobility service providers are also exploring cabin displays to enhance passenger experience, support route-based content, and enable service branding. This broad demand base is pulling product roadmaps toward modular architectures that can be configured by cabin size, vehicle segment, and channel. Pricing stratification reflects this diversity: entry-level panels in the 5–7 inch range typically occupy a lower price band, while premium OEM solutions above 10 inches with advanced features command substantially higher unit values. This spread encourages tiered product strategies and allows suppliers to address multiple vehicle classes without fragmenting their manufacturing footprint excessively.
Supply chain and cost structures are undergoing recalibration. The concentration of display panel manufacturing, semiconductor content, and specialty materials in a limited set of geographies has made end-to-end visibility a priority. Automakers and Tier-1s are diversifying sourcing, qualifying alternative materials where feasible, and negotiating longer-term agreements to stabilize costs amid evolving export controls and minerals definitions. At the same time, integration complexity is rising as video monitors become part of broader cockpit and infotainment platforms. Suppliers that combine display hardware, software interfaces, and system integration services reduce friction for OEMs, shorten validation cycles, and create stickier relationships. The cost equation increasingly favors partners who can deliver coordinated solutions rather than isolated components, especially as vehicles move toward domain-controlled architectures and centralized compute.
Competitive Landscape and Leading Strategies
The competitive field spans display specialists, Tier-1 system integrators, and infotainment-focused electronics manufacturers. Display leaders such as LG Display, Samsung Display, AU Optronics, and BOE Technology Group bring deep panel engineering capabilities, broad size ranges, and growing portfolios of automotive-grade OLED, microLED, and transformable form factors. Their strategies emphasize differentiation through form factor innovation, premium image quality, and cockpit-wide integration concepts. By offering rear seat entertainment options alongside cockpit displays, these companies position themselves as enablers of unified cabin experiences rather than isolated screen suppliers. Samsung Display has highlighted rooftop and round OLED configurations designed for immersive passenger entertainment, while AU Optronics has advanced interactive cockpit concepts that blend rear seat video with mixed-reality interactions. BOE’s wide span of automotive display sizes supports flexible cabin packaging across vehicle segments. These approaches reflect a broader industry shift toward displays that serve both functional monitoring and experiential entertainment roles.
Tier-1 integrators including Continental AG, Denso Corporation, Bosch, Hyundai Mobis, Visteon Corporation, and Panasonic Corporation add system-level value by embedding video monitors within infotainment, instrument cluster, and connected cockpit architectures. Their differentiation lies in software integration, validation expertise, and the ability to align displays with vehicle electrical architectures and safety requirements. For OEMs, this reduces integration risk and accelerates program timing. Companies such as Visteon and Bosch emphasize connected interfaces and cabin-wide user experiences, while Denso and Continental focus on robust automotive-grade delivery and cross-domain compatibility. Hyundai Mobis leverages its position across global vehicle programs to scale integrated electronics and display solutions, including video monitor integration for entertainment and interface applications.
Aftermarket and audio-visual specialists such as Pioneer Corporation, Alpine Electronics, and Panasonic further broaden the market by serving both OEM and retrofit channels. Their strengths include consumer-facing brand recognition, configurable product lines, and faster iteration cycles for headrest and rear seat video monitors. This channel diversity gives automakers and fleets flexibility to address different price points and vehicle lifecycles, while also enabling faster adoption in segments where full OEM redesign cycles are not feasible.
Recent developments illustrate how strategies are converging around experience-led differentiation. AU Optronics demonstrated an XR interactive window feature for rear seats, using on-device computing to support interactive video and mixed reality within smart cockpit concepts. Samsung Display later showcased new RSE options, including a compact round display and a larger rooftop OLED configuration, signaling a push toward immersive, form-factor-diverse passenger entertainment. These moves underscore a common theme: value is shifting from basic video output toward integrated, interactive cabin experiences that combine display hardware, compute, and software.
Market structure is evolving along multiple axes. Concentration remains moderate, with the top three firms capturing a meaningful share and the top five collectively representing the majority of revenue, which indicates room for differentiation but also a baseline of scale advantages. The landscape is simultaneously consolidating where integration and compliance capabilities matter most, and fragmenting where niche form factors, regional programs, and aftermarket flexibility create openings. New entrants and second-tier suppliers can gain traction by specializing in specific cabin zones, developing cost-optimized panels for volume segments, or offering rapid-turn aftermarket solutions. However, sustained leadership increasingly depends on the ability to manage regulatory complexity, secure material streams, and deliver coordinated hardware-plus-software offerings that align with OEM program timing and validation cycles.
Future Outlook and Strategic Trends
Over the next three to five years, the market is likely to be shaped by three interconnected trends. First, cabin video systems will increasingly function as part of broader digital cockpit platforms rather than standalone accessories. Displays in headrests, roofs, dashboards, and consoles will be coordinated through shared software layers, enabling consistent user experiences, unified content services, and more efficient hardware utilization. This creates opportunities for suppliers that can deliver end-to-end cockpit integration and for automakers that can leverage video monitors as anchors for in-vehicle services.
Second, form-factor diversity and interactive capabilities will become more mainstream across segments. Round, foldable, rollable, and transparent displays will move from showcase concepts toward selected production applications, especially in premium cabins and mobility services targeting passenger engagement. Mixed-reality and context-aware interfaces will expand where compute and content ecosystems support them, creating premium features that differentiate models and support higher unit values. Commercial opportunities will emerge for companies that can translate these capabilities into reliable, automotive-grade products with clear cost and validation pathways.
Third, supply chain resilience and compliance readiness will increasingly determine winning positions. Ongoing export controls on specialty materials, evolving definitions of critical minerals, and connected-vehicle transaction rules will continue to influence sourcing decisions and program timelines. Suppliers that maintain diversified sourcing, clear traceability, and regional compliance competence will be better equipped to secure long-term contracts and reduce program risk. Potential uncertainties include further regulatory tightening, cost pressure from material constraints, and the risk that premium features remain confined to high-end segments if validation and pricing challenges persist. These forces will reward disciplined portfolio management and agile channel strategies.
Actionable Guidance for Decision-Makers
For display and component manufacturers, the priority is to align portfolios with cabin-wide integration trends while strengthening compliance and sourcing resilience. This means investing in modular architectures that can serve headrest, roof, dashboard, and console applications, and ensuring that hardware roadmaps account for regional regulations and material constraints. Partnerships that combine panel technology with software interfaces and system validation can shorten OEM adoption cycles and increase stickiness.
For investors, the most durable value creation is likely to come from companies that blend differentiated display technology with integration capability and channel flexibility. Exposure to premium RSE solutions, cockpit-platform providers, and suppliers with transparent compliance and sourcing practices offers a balanced risk-return profile. Monitoring product launches that expand interactive or immersive features, alongside supply-side developments affecting materials and semiconductors, can provide early signals of competitive shifts.
PW Consulting
For procurement and program leaders, building multi-source strategies and clear qualification pathways is essential. Balancing OEM and aftermarket channels, targeting tiered pricing structures that match vehicle segments, and validating suppliers on both technical and regulatory criteria will reduce exposure to disruption. Full-report data on segment sizing, regional dynamics, pricing bands, and company-level market positions can support more precise sourcing decisions and investment prioritization.
For detailed analysis of this topic, please visit the official page: Worldwide Car Video Monitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com