

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Capsule Endoscope Attitude Controller Market: Why 10.45% CAGR Redefines 2032 Value

Worldwide Capsule Endoscope Attitude Controller Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The global market for capsule endoscope attitude controllers has transitioned from a niche diagnostic adjunct to a structurally important category within gastrointestinal imaging. Historical data from 2020 through 2025 shows a consistent expansion trajectory, with cumulative revenue rising from approximately USD 175.4 million to USD 285.8 million. The forward-looking horizon through 2032 points to a sustained compounding path, reaching an estimated USD 573.1 million by the end of the forecast period and reflecting a compound annual growth rate of 10.45 percent. This scale of movement matters because it indicates that attitude control hardware—controllers, magnetic guidance units, robotic navigation interfaces, and related software—is becoming a commercial center of gravity rather than a peripheral accessory.
Two structural challenges define the current inflection point. First, the category is characterized by high market concentration. The top three players account for roughly 68.45 percent of total revenue, while the top five capture about 82.1 percent. Such concentration typically signals mature distribution channels, entrenched clinical relationships, and regulatory familiarity on the part of incumbents. At the same time, it compresses the strategic room for new entrants, especially in regions where reimbursement pathways and hospital procurement habits favor established vendors. For decision-makers, this means that raw clinical promise is insufficient; commercial traction requires alignment with purchasing committees, integration into existing diagnostic workflows, and demonstrable operational efficiency.
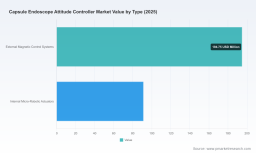
Second, the category is navigating a tension between technical capability and real-world adoption. External magnetic control systems and internal micro-robotic actuators represent different philosophies of how a capsule should be maneuvered inside the body. The former offers strong directional control at a system level, often with robotic or joystick interfaces, while the latter emphasizes miniaturization and in-capsule actuation. Neither approach has fully resolved the operational trade-off between control precision, procedure time, staff training burden, and cost per exam. In practice, this shows up as uneven uptake across institutions, with some early-adopter centers integrating active control into routine pathways and others treating it as a specialized tool for difficult cases. The challenge for leadership is to avoid overgeneralizing early success and instead evaluate where controlled navigation genuinely changes clinical throughput, diagnostic yield, or patient experience.
A third, subtler challenge is the regulatory and reimbursement environment. Certain systems have earned clearances or approvals for specific indications and patient populations, yet coverage policies have not always evolved in lockstep. As a result, even technically capable platforms can face uncertainty when hospitals attempt to scale usage beyond initial pilot programs. The implication is that commercial success depends as much on evidence generation, coding clarity, and procurement framing as on device sophistication. Organizations entering or expanding in this space need to plan for a prolonged validation cycle, not just a product launch milestone.
Key Drivers Reshaping the Market
The first and most visible driver is technological innovation that broadens what a capsule can do under active control. The category is moving beyond simple passive transit to systems that can adjust orientation, position, and viewing angles in real time. This shift matters because visualization quality and procedural flexibility are increasingly tied to how well a clinician can direct the capsule through complex anatomy. Recent product activity illustrates this trend: a magnetically controlled capsule system has expanded its commercial footprint by introducing a small bowel platform built around aspherical lens technology intended to widen the field of view and reduce distortion. Alongside that, the same platform has progressed through regulatory clearances and indication expansions that make it usable across broader age ranges and body types, including updated access for pediatric and higher-BMI populations in certain systems. These moves are not isolated hardware upgrades; they signal a deliberate attempt to make active control clinically practical across more patients and more gastrointestinal segments.
A second driver is the evolving regulatory and reimbursement landscape, which is becoming both an enabler and a gating factor. Some magnetically controlled systems have established regulatory status for active locomotion in gastrointestinal diagnostics, while others have secured approvals for stomach visualization or small bowel use with successive indication expansions. This staggered approval pattern shapes adoption because hospitals tend to prioritize platforms with clear regulatory standing and the strongest documentation for the procedures they perform most often. At the same time, reimbursement realities differ across settings. In some healthcare systems, standard wireless capsule endoscopy already has an established coverage framework for small bowel visualization, while advanced magnetic control options may still be treated as investigational for certain upper abdominal indications. The commercial implication is that vendors and adopters alike must treat evidence generation and policy engagement as integral to product strategy, not as after-the-fact activities.
The third driver is demand-side change, especially the growing pressure on healthcare providers to improve diagnostic efficiency while limiting invasive procedures. Capsule endoscopy already offers a less invasive alternative for many patients, but attitude control adds a more compelling value proposition: the ability to steer, pause, and reorient imaging in targeted regions rather than relying entirely on chance transit. For hospitals and imaging centers, this can translate into better coverage of suspicious areas, more consistent procedure quality, and potentially fewer repeat studies. For patients, the appeal may include reduced discomfort and greater confidence that the examination is being actively guided. Demand is therefore being shaped not only by clinical performance, but also by operational goals such as throughput, staff utilization, and procedural predictability.
Worldwide Ultra HD Endoscope Market
The fourth driver involves supply chain and cost structure dynamics. Active control platforms require a broader ecosystem than capsules alone: controllers, magnets, robotics, software, calibration support, maintenance, and training. This increases the importance of manufacturing consistency, component sourcing, service networks, and software reliability. In parallel, the market's concentration pattern suggests that incumbents are building durable relationships around service contracts, clinical training, and system integration. For competitors, this means that competing on capsule hardware alone is unlikely to be sufficient; differentiation is increasingly tied to total cost of ownership, workflow compatibility, and post-sale support. The market is gradually rewarding organizations that can reduce the friction of adoption across an entire institution rather than a single department.
PW Consulting
Competitive Landscape and Leading Strategies
The competitive environment is dominated by companies that have pursued different positions along the control, indication, and market-access dimensions. One U.S.-headquartered firm with operations in China has emphasized a magnetically controlled capsule endoscopy system designed for precise translational and rotational control, particularly in stomach and gastrointestinal segments. Its recent activities show a blend of product progression and regulatory expansion: a small bowel system with aspherical lens technology was launched commercially, the small bowel platform received FDA clearance for expanded indications, and the stomach capsule indications were broadened to include younger patients and higher BMI ranges. This sequence reflects a strategy of extending a single control platform into multiple anatomical use cases while widening the addressable patient population. In practical terms, the company is positioning its technology not as a single-purpose tool, but as a shared navigation backbone that can support several examination types.
Another prominent player, based in Korea, has pursued a more compact control model with a hand-held magnetic controller for real-time navigation of its capsule in the esophagus, stomach, and duodenum. This approach highlights a different value proposition: the controller is designed to be intuitive and immediately usable, which can lower training barriers and make active control feel less like a specialized robotics project and more like an extension of existing endoscopic practice. The strategic message is that usability and direct clinician control can be as important as automation. For health systems that want magnetic control without a major operational overhaul, this type of design can be attractive because it reduces complexity and potentially accelerates adoption.
In China, multiple firms have advanced magnetically controlled systems that leverage either standing-type or robotic magnetic guidance. One Shenzhen-based company has moved forward with hospital deployment partnerships, including a strategic arrangement to introduce its magnetic controlled capsule endoscopy system at a major hospital. Another Chongqing-based group has developed capsule series with magnetically controlled variants and a fully automated magnetic control system for robotic attitude and navigation. These moves illustrate two parallel competitive themes: first, the importance of local distribution, clinical relationships, and institutional pilot programs in building credibility; and second, the growing divergence between systems that prioritize robotic automation and those that emphasize clinician-directed control. The Chinese market's scale and speed of adoption offer early evidence of how quickly magnetic control can move from niche trials into routine diagnostic pathways when supported by strong local partnerships.
Across these players, a few strategic patterns are emerging. First, the leaders are not competing solely on capsule optics or sensor quality; they are competing on control interfaces, procedural integration, and indication breadth. Second, regulatory milestones and clinical partnerships are being used as differentiators, especially where coverage policies and hospital procurement remain cautious. Third, the market is likely to see further consolidation pressure over time, not necessarily through mergers alone, but through adoption choices that favor platforms with wider indication coverage, established service networks, and clearer reimbursement positioning. At the same time, new entrants may still find room in specialty niches such as dedicated esophageal applications, pediatric use, or hybrid control solutions that blend clinician guidance with automated assistance. The overall landscape is therefore becoming less about a single winning architecture and more about the ability to match a control strategy to a defined clinical and commercial context.
Outlook for the Next Three to Five Years
Over the next three to five years, one likely trend is the continued widening of indications for active control platforms. As more systems gain clearances and as clinical experience accumulates, the market should move toward broader patient eligibility, more flexible use across gastrointestinal segments, and greater institutional comfort with magnetically guided procedures. This trajectory creates commercial opportunities for vendors that can document consistent performance across populations and settings, and for adopters that can standardize the technology into repeatable service lines rather than isolated pilot programs.
A second trend is the growing importance of workflow integration and automation balance. Hospitals are likely to favor systems that fit cleanly into scheduling, staffing, documentation, and data management processes. That does not mean every platform needs full automation; rather, it means the most successful offerings will probably be those that make clinician effort, training time, and reporting burden predictable. Hybrid models that combine guided control with decision support, image triage, or reporting assistance may gain traction because they address both clinical control and operational efficiency. The commercial opportunity lies in reducing the hidden costs of adoption: staff retraining, procedure variability, and administrative complexity.
A third trend concerns market structure and geographic divergence. Concentration at the top of the market is likely to persist in the near term, especially where incumbents have strong relationships, proven support infrastructure, and regulatory familiarity. However, regional dynamics will differ. In some markets, local champions with hospital partnerships and domestic approvals may strengthen their position quickly, while in others, global platforms may gain ground through broader indication coverage and international clinical evidence. The associated risk is that over-reliance on any single control paradigm or regulatory pathway could limit flexibility if reimbursement policies shift or if new evidence changes clinical preferences. Decision-makers should therefore treat geographic expansion and indication growth as interconnected, not independent, strategic choices.
Actionable Considerations for Decision-Makers
For manufacturers, the strategic priority is to define a control architecture that aligns with a clear clinical use case and then build the surrounding evidence, service, and integration model to support it. Competing on technical novelty alone leaves too much open to procurement scrutiny. It is more effective to target a well-defined patient population or procedure type, demonstrate measurable operational benefits, and prepare for the reimbursement and training requirements that determine whether a pilot can scale. Companies should also evaluate whether their platform is best positioned as a clinically focused tool, a workflow-integrated system, or an automation-enhanced solution, because each path implies a different go-to-market and support strategy.
Worldwide Robotic Scope Holder Market
For investors, the key question is how durable a company's differentiation will be once early regulatory and product milestones are achieved. Indications, hospital partnerships, and commercial launch activity are important, but they need to be evaluated alongside reimbursement positioning, concentration risk, and the cost of scaling service and training infrastructure. Preference should be given to businesses that show progress in converting clinical capability into repeatable revenue, not just product announcements. Geographic exposure is also worth scrutinizing, because market adoption can vary sharply depending on local approval status and purchasing practices.
For procurement and clinical strategy teams, the practical task is to assess attitude control not as a standalone device purchase, but as a change in diagnostic workflow. The right evaluation framework should consider procedure time, staff training requirements, intended patient populations, maintenance and service obligations, and the likelihood of reimbursement support for the targeted indications. Where possible, pilot programs should be designed to test operational fit and integration with existing reporting and data systems, rather than focusing solely on image quality. Detailed segmentation data on regional uptake, application mix, and type-level adoption patterns can help narrow these decisions, but the strategic value lies in connecting that information to institutional priorities and revenue models.
For organizations seeking a fuller picture of where the market is heading, deeper segmentation detail, competitive benchmarking, and indication-level context can clarify which opportunities are most realistic under current regulatory and reimbursement conditions. The commercial prize in this category is unlikely to go to the most ambitious technology in isolation; it will go to the players that can make active capsule control clinically credible, operationally manageable, and economically sustainable at scale.
For detailed analysis of this topic, please visit the official page: Worldwide Capsule Endoscope Attitude Controller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com