

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide 6-Tert-butyl-0-cresol Market: What the 4.45% CAGR Trajectory Really Means

Navigating the Global 6-Tert-butyl-0-cresol Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The global market for 6-Tert-butyl-0-cresol, widely recognized for its role as a high-performance antioxidant, has demonstrated consistent expansion over the past five years. Valued at approximately USD 275.5 million in 2020, the market reached USD 340.0 million by 2025. Projections indicate the market will expand to USD 462.69 million by 2032, growing at a Compound Annual Growth Rate (CAGR) of 4.45 percent throughout the forecast period from 2026 to 2032. This trajectory underscores the compound's entrenched position in industrial supply chains, particularly within polymer stabilization and fuel additive sectors. Revenue figures are primarily denominated in USD Million, reflecting the commodity-like nature of the chemical while highlighting significant margins available through specialization.
Despite this positive growth outlook, the industry stands at a critical juncture defined by three converging challenges. First, regulatory scrutiny regarding chemical safety has intensified, particularly regarding downstream applications in food packaging and consumer plastics. Compliance requirements such as EU REACH authorization for use above certain thresholds in plastics have created friction for manufacturers who previously relied on established legacy formulations. This regulatory pressure forces a reevaluation of supply chains and product specifications, potentially slowing adoption in sensitive regions while creating opportunities for certified, high-purity alternatives.
Second, supply chain volatility poses a significant risk to margin stability. Raw material inputs, specifically phenol feedstocks, have experienced price fluctuations due to geopolitical tensions and supply disruptions in key production hubs. For instance, recent data indicates an 8 percent rise in phenol feedstock prices in the first quarter of 2025 driven by these disruptions. Such volatility complicates cost forecasting for producers and can erode profitability if hedging strategies are not robust. Manufacturers must navigate these cost pressures without passing excessive burdens to downstream customers who are themselves facing economic headwinds.
Third, the market exhibits moderate concentration, with the top five players commanding a significant share of total revenue. This structure creates a barrier to entry for new competitors but also concentrates risk. Any production outage or strategic misalignment among key suppliers can ripple through the global supply network. Furthermore, trade policies, such as specific duty codes applied to imported chemical grades in major economies, add layers of complexity to international logistics and pricing strategies. Companies must balance local production advantages against the efficiency of globalized supply networks.
Key Drivers of Market Evolution
Several foundational factors are driving the momentum observed in the 6-Tert-butyl-0-cresol sector. Understanding these drivers is essential for stakeholders looking to capitalize on emerging opportunities or mitigate potential risks.
Technological Innovation and Material Performance
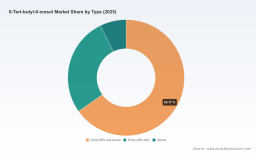
The primary engine of demand remains the critical need for material durability in high-performance applications. 6-Tert-butyl-0-cresol serves as a vital antioxidant, preventing degradation in polymers, rubbers, and petroleum products exposed to harsh environmental conditions. As industries push for longer-lasting materials to reduce waste and lifecycle costs, the specification for higher purity grades is becoming standard. The market segmentation reflects this shift, with the segment requiring purity levels of 99 percent and above representing the largest revenue share. This trend is not merely about meeting minimum standards but about enhancing performance efficiency in automotive plastics and industrial rubber components where failure is not an option.
Innovation is also extending beyond traditional rubber and plastic uses. There is growing interest in specialized grades tailored for specific polymer matrices where standard antioxidants may interfere with curing processes or color stability. Manufacturers who invest in refining purification technologies to deliver consistent high-purity outputs gain a competitive edge, allowing them to command premium pricing and secure long-term contracts with demanding original equipment manufacturers (OEMs).
Di-tert-Butyl Peroxide (DTBP) Market
Policy and Regulatory Environment
Regulatory frameworks are reshaping how 6-Tert-butyl-0-cresol is sourced, processed, and applied. In Europe, stricter authorization requirements under REACH for uses above 0.1 percent in plastics have forced producers to ensure comprehensive documentation and safety data. Similarly, restrictions on food contact applications in various jurisdictions require clear separation between industrial grades and those approved for consumer-facing products. This bifurcation creates a need for distinct production lines and rigorous quality control protocols.
Trade policies also influence market dynamics. For example, specific duty classifications in the United States apply differential rates to imported chemical grades depending on their country of origin and trade agreement status. These tariffs influence sourcing decisions, encouraging buyers to seek suppliers within free trade zones or local manufacturers to avoid cost penalties. Consequently, regulatory compliance is no longer just a legal requirement but a strategic lever that determines market access and cost structures.
Demand-Side Shifts in Manufacturing
Downstream demand is evolving as composite industries modernize. The automotive sector, a major consumer of polymer stabilizers, is shifting toward lightweight materials to improve fuel efficiency and support electrification. These new material formulations often require precise antioxidant protection to maintain structural integrity over extended lifecycles. Similarly, the construction and infrastructure sectors are increasingly utilizing synthetic rubbers and engineered plastics that rely on effective stabilization to withstand weathering and UV exposure. This demand for durability translates directly into sustained consumption of high-performance antioxidants.
Additionally, there is a growing emphasis on supply chain resilience among procurement teams. Following recent global disruptions, industrial buyers are prioritizing suppliers who can guarantee consistent availability over those who offer only the lowest spot prices. This shift benefits established manufacturers with robust production capacities and diversified supply chains, allowing them to build stronger partnerships with key accounts in the polymer and fuel additive sectors.
Supply Chain and Cost Structure Dynamics
The cost structure of 6-Tert-butyl-0-cresol production is closely tied to petrochemical feedstock availability and energy costs. Fluctuations in phenol prices, often driven by upstream capacity constraints in Asia-Pacific regions, directly impact production margins. Suppliers must manage these input costs carefully, often utilizing long-term feedstock contracts or vertical integration strategies to stabilize expenses. Energy intensity in the manufacturing process also means that regional energy prices and carbon regulations can affect the competitiveness of production facilities in different geographies.
Logistics and distribution networks further influence the cost landscape. Regions with established chemical infrastructure benefit from lower handling and transportation costs, while remote markets may face higher landed costs due to freight and storage requirements. Efficient supply chain management, including strategic inventory positioning, becomes a key differentiator for suppliers aiming to offer reliable delivery schedules despite global logistical complexities.
Competitive Landscape and Leading Strategies
The competitive environment for 6-Tert-butyl-0-cresol is characterized by a mix of global specialty chemical producers and regional manufacturers who have expanded their capabilities to meet international standards. The market concentration, indicated by a combined share of over 48 percent held by the top five entities, suggests a mature landscape where scale and expertise provide significant defensive moats.
PW Consulting
SI Group, headquartered in the USA, stands as a leading global producer, marketing the compound primarily as antioxidant BHT for plastics, rubber, and petroleum applications. Their strategic positioning relies on broad global reach and established brand recognition within the industrial additives community. By maintaining high production standards and diverse application support, they secure a strong foothold in North American and international markets where reliability is paramount.
In Asia, Songnox Antioxidants, part of the Songwon Industrial Group based in South Korea, supplies the compound as a high-performance antioxidant for polymer stabilization and industrial uses. Their approach emphasizes technical service and integration into broader polymer additive solutions. This allows them to capture value not just from the chemical itself but from the performance improvements they enable for downstream polymer processors.
Chinese manufacturers play a substantial role in the supply base, with companies like Beijing Tiangang Auxiliary, Zhejiang Friends Chemical, and Chihon Industry actively producing grades for antioxidants in plastics, synthetic rubber, food packaging, and rubber processing. Beijing Tiangang Auxiliary focuses on antioxidants for plastics and synthetic rubber, including food packaging applications where regulatory compliance is critical. Zhejiang Friends Chemical produces pharmaceutical and industrial grades, catering to sectors that require exceptional purity and documentation. Chihon Industry serves the rubber processing and polymer additives market, leveraging regional manufacturing efficiencies to compete on cost and availability.
The market is evolving through both consolidation and specialization. Larger players are likely to pursue strategic acquisitions or partnerships to secure feedstock supply chains and expand geographic coverage. Meanwhile, smaller or regional producers may differentiate by focusing on niche purity specifications or localized service capabilities. The barrier to entry remains high due to the technical knowledge required for consistent high-purity production and the capital intensity of the manufacturing process. New entrants must navigate not only production challenges but also the complex web of trade duties and regulatory authorizations that govern cross-border chemical trade. Differentiation strategies increasingly revolve around the ability to provide certified, traceable supply chains that meet the stringent requirements of regulated industries.
O-Cresol (CAS 95-48-7) Market
Future Trends and Commercial Opportunities
Looking ahead to the 2026 to 2032 period, several trends will define the trajectory of the 6-Tert-butyl-0-cresol market. Stakeholders should anticipate shifts in demand patterns, regulatory frameworks, and competitive dynamics that will create both risks and opportunities.
First, the demand for high-purity grades is expected to outpace the general market growth rate. As polymers and composites are used in more demanding environments, such as electric vehicle components and advanced construction materials, the tolerance for impurities decreases. This trend favors producers with advanced purification capabilities and robust quality assurance systems. Companies that can reliably supply 99 percent purity and above will likely capture greater value share, while commodity-grade segments may face margin compression due to competition and substitution risks.
Second, regulatory divergence between regions will create a multi-tiered market structure. While some regions tighten restrictions on specific applications, others may maintain more permissive standards for industrial uses. Manufacturers with the flexibility to adjust formulations and documentation for different regional requirements will gain a strategic advantage. This could lead to a scenario where supply chains are segmented by compliance level, with premium, fully certified streams serving sensitive markets and standard streams serving industrial applications with less restrictive oversight.
Third, supply chain localization and regionalization trends may accelerate. Trade policies, including duties on imports from non-free trade agreement countries, combined with the desire for supply security, may encourage buyers to source closer to end markets. This presents an opportunity for regional producers to expand their footprint and capture demand that previously flowed through global logistics networks. However, it also requires investment in local production capacity and compliance infrastructure to meet regional standards.
Potential risks include further tightening of chemical safety regulations that could restrict certain application areas, particularly those involving consumer contact. Additionally, volatility in raw material costs could remain a persistent challenge, requiring agile procurement and pricing strategies. Companies must remain vigilant about geopolitical developments that could disrupt feedstock supply or alter trade dynamics, as these factors can quickly change the competitive calculus.
Strategic Recommendations for Decision Makers
For manufacturers, the priority should be investing in purification technologies and certification capabilities to access high-value segments. Aligning production processes with evolving regulatory requirements, such as REACH authorization and food contact restrictions, will protect market access and enable premium positioning. Strengthening supply chain resilience through diversified feedstock sourcing and strategic inventory management will also mitigate cost volatility risks.
Investors should focus on companies with proven high-purity production capabilities and strong compliance frameworks. Evaluating exposure to regulatory risks and the ability to navigate trade policies will be critical in assessing long-term value. Opportunities may exist in consolidation plays where scale and geographic diversification can drive efficiency and market share gains in a growing market.
Procurement and supply chain leaders should prioritize supplier partnerships based on reliability and compliance assurance rather than price alone. Diversifying the supplier base to include both global and regional sources can reduce vulnerability to disruptions and trade barriers. Engaging early with suppliers to understand their capacity for meeting future purity and regulatory requirements will ensure continuity of supply for critical applications.
For stakeholders seeking detailed segmentation data, regional breakdowns, and customized strategic scenarios, comprehensive industry research reports provide the granular intelligence needed to refine these strategies. Deep-dive analysis into production capacity, capacity utilization, and specific regional demand drivers can further validate investment theses and operational plans.
For detailed analysis of this topic, please visit the official page: Worldwide 6-Tert-butyl-0-cresol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com